


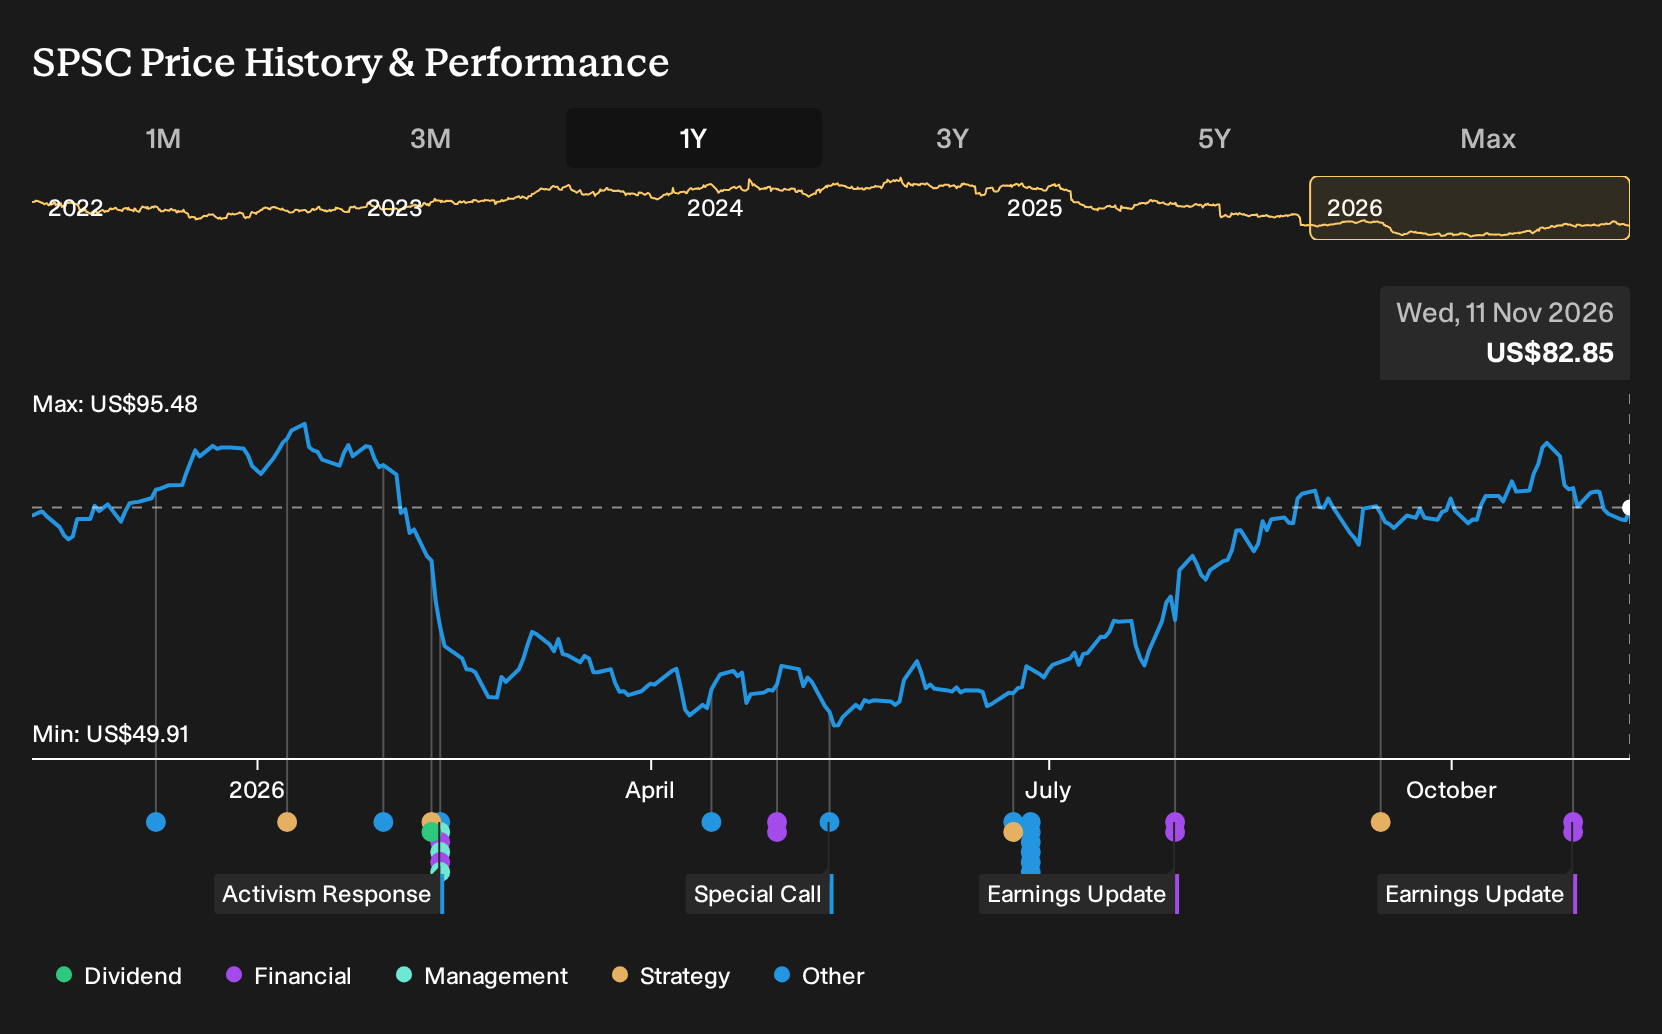
- SPS Commerce reported third quarter 2026 sales of US$197.65 million and net income of US$30.68 million, with both basic and diluted EPS at US$0.85, and released nine month results to 30 September 2026.
- The nine month period showed sales of US$587.58 million with net income of US$57.28 million. Management issued 2026 guidance that focuses on revenue and earnings per diluted share ranges based on its existing network economics.
- We will examine how SPS Commerce's updated full year 2026 EPS guidance influences the investment narrative centered on ARPU driven expansion.
Compare how SPS Commerce stacks up against hand-picked peers by scanning 19 high quality undiscovered gems that could be setting up for their next earnings driven rerating.
SPS Commerce Investment Narrative Recap
SPS Commerce still hinges on a simple belief. The platform needs to keep lifting revenue per customer on a relatively flat user base while holding on to its strong subscription economics. The latest quarter fits that story in a fairly steady way. Q3 earnings and the updated full year EPS guidance frame 2026 as a consolidation year rather than a reset.
The key near term catalyst remains execution on ARPU driven expansion and MAX AI adoption, as highlighted in the analyst consensus Narrative on Simply Wall St. The main risk has not changed. Customer scrutiny on spend and any further contract downsizing among suppliers could pressure that ARPU focus and keep profit growth choppy.
The fresh full year 2026 outlook ties directly to those catalysts. Management now guides revenue to US$786.9 million to US$788.9 million and EPS to US$2.29 to US$2.35. That range helps investors focus on modest top line progress while monitoring whether mix, automation and ARPU work can support earnings quality.
Q4 guidance of US$199.3 million to US$201.3 million in revenue and US$0.74 to US$0.79 EPS also matters for timing. It sets a near term bar for how effectively SPS Commerce is backfilling the Amazon 3P revenue gap, scaling its 1P recovery focus and absorbing macro caution from supplier customers without further margin strain.
SPS Commerce's narrative projects US$927.0 million revenue and US$172.5 million earnings by 2029, based on analysts assuming 5.9% yearly revenue growth and roughly a 2x earnings increase from US$83.1 million today.
Uncover why SPS Commerce's fair value aligns with its current price.
Exploring Other Perspectives
One alternate story around SPS Commerce focuses on weaker MAX AI monetization. The most bearish analysts were penciling in around US$925.2 million in revenue and US$154.3 million in earnings for 2029 before this Q3 update. That view is clearly more cautious. Use it as a prompt to compare several narratives instead of relying on just one.
Explore 5 other SPS Commerce fair value estimates, including one that suggests as much as 42% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SPS Commerce research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for SPS Commerce. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SPS Commerce's overall financial health at a glance.
Looking for more SPS Commerce sized investment ideas?
If the SPS Commerce story has sharpened your thinking and you want to test that framework on other opportunities, the Simply Wall St Screener can help you quickly filter for stocks that line up with your own risk tolerance and return goals.
- If capital protection sits high on your list, start with companies that score well on resilience and balance sheet strength using the 30 resilient stocks with low risk scores.
- For investors who want quality businesses that may be trading below their estimated worth, scan the 32 high quality undervalued stocks and see which tickers merit a closer look.
- If you care most about financial solidity and fundamentals before anything else, build a watchlist straight from the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com