


Why Sanofi's flu COVID combo trial matters for the stock
Sanofi (ENXTPA:SAN) pushed its influenza COVID 19 combination vaccine into Phase 3 testing in Europe, a high profile respiratory vaccine project that triggered sizeable milestone payouts to partner Novavax.
For anyone tracking Sanofi shares, that single step does two things at once. It moves a late stage pipeline asset closer to potential commercialization, and it highlights how partnered vaccine platforms could affect future economics for both sides.
Sanofi shares have picked up momentum recently, with a 20.96% 1 month share price return and a 13.32% 3 month share price return helping lift the stock to €86.61. The 1 year total shareholder return of 1.47% and 5 year total shareholder return of 18.45% point to a steadier long run journey that sets current excitement around the flu COVID combo and the firm’s raised 2026 guidance alongside a more measured performance record.
Surf 568 high quality undiscovered gems that, like Sanofi’s flu COVID combo effort, are quietly building late stage pipelines and partnerships that could reshape their future economics.Bulls point to Sanofi’s respiratory pipeline and raised 2026 guidance. Bears focus on mixed nine month earnings. Which story shows up more clearly once you line that up against today’s valuation metrics?
Most Popular Narrative: 19.9% Overvalued
On the valuation side, the narrative fair value for Sanofi sits at €72.23 versus the recent €86.61 close. This highlights how much optimism is already in the price according to Szock, an investor in the Simply Wall St Community who set out a detailed view on the stock.
Der französische Pharmariese Sanofi bietet Anlegern derzeit eine interessante Kombination aus attraktiver Bewertung, starker Dividendenrendite und solider operativer Dynamik.
Wer jedoch ein substanzstarkes, krisenresistentes Unternehmen mit hohen Cashflows und einer starken Dividende sucht, findet in Sanofi derzeit einen attraktiven und fair bewerteten Titel.
See why 5 investors see Sanofi as 20% overvalued.
Result: Fair Value of €72.23 (OVERVALUED)
Still, the Sanofi narrative could be challenged if key drugs face faster than expected patent pressure, or if the flu COVID combo underdelivers in Phase 3.
Find out about the key risks to this Sanofi narrative.
Another View: Sanofi Through A Cash Flow Lens
That community fair value of €72.23 paints Sanofi as almost 20% overvalued. The SWS DCF model tells a very different story, with an estimate of future cash flow value around €268.02 per share versus the current €86.61 price, which frames the stock as heavily undervalued on that methodology.
For anyone weighing both approaches, the gap between a narrative price anchor and a cash flow driven figure raises a simple question. Which set of assumptions feels closer to how you think Sanofi will actually convert its pipeline and partnerships into cash over time, and which one are you more comfortable leaning on when the next headline hits?
Look into how the SWS DCF model arrives at its fair value.
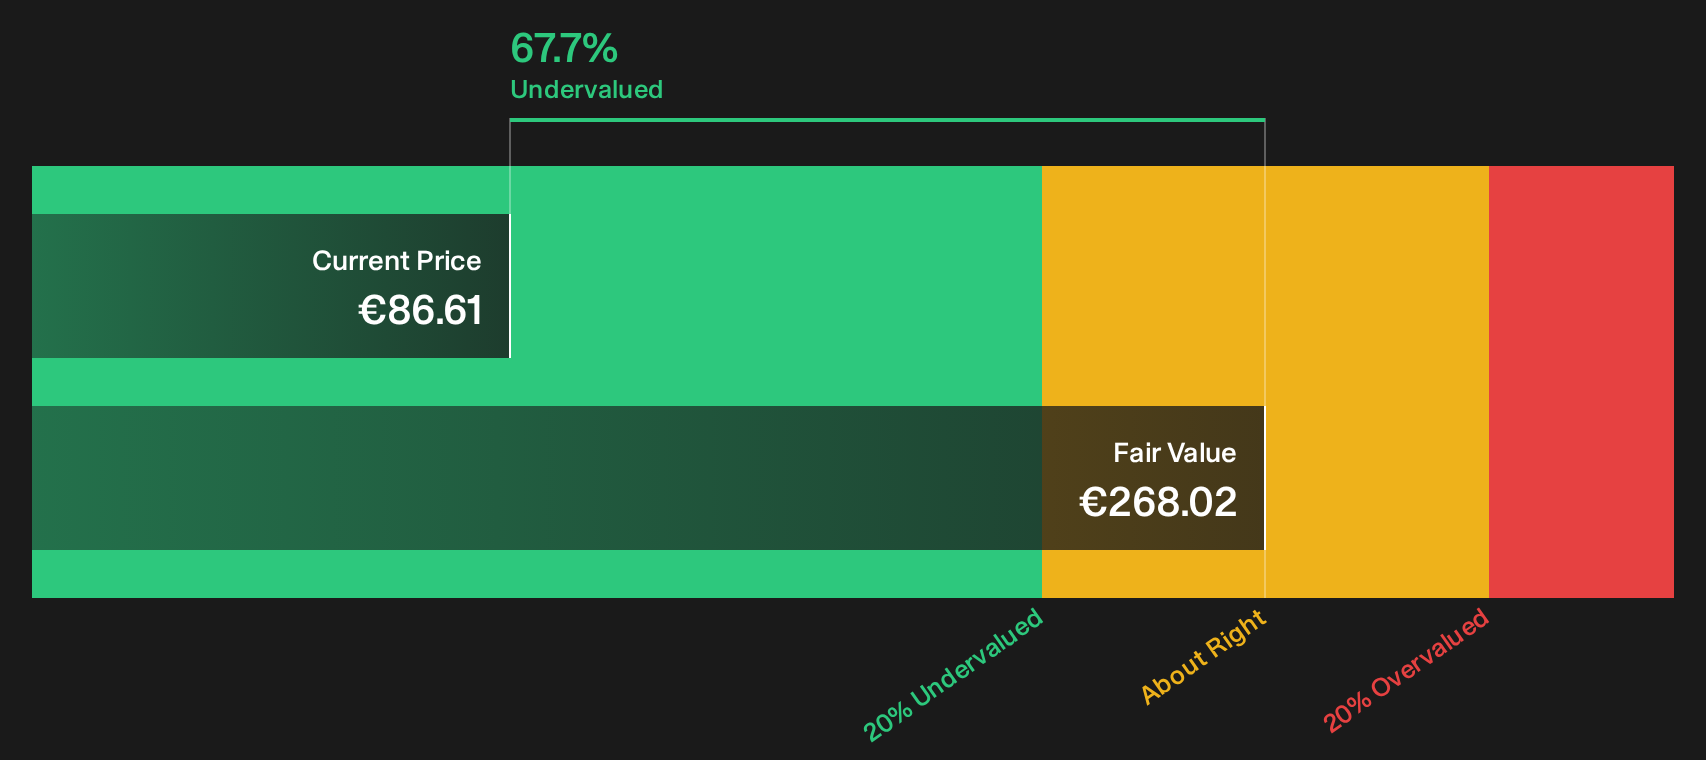
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanofi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sanofi so far, right? Take a moment to inspect the full picture yourself and weigh both sides of the debate through 2 key rewards and 3 important warning signs.
Want more ideas beyond Sanofi?
You have seen how different valuation lenses can change the story for Sanofi. Now use that same mindset to spot fresh opportunities elsewhere.
- Target durable income by scanning for companies built around reliable payouts through the 212 dividend fortresses.
- Hunt for quality at a discount by running the 195 high quality undervalued stocks and focusing on businesses with solid fundamentals trading below intrinsic estimates.
- Prioritize resilience by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (195 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com