


Hyatt Hotels (H) has been back in focus after its latest quarterly update showed a return to profit, fresh 2026 earnings guidance and continued growth in its fee-driven development pipeline.
Recent trading shows that the latest earnings, new 2026 guidance and a run of corporate actions are feeding into how investors view Hyatt Hotels. The share price is now at US$190.18, with a 30 day share price return of 17.99% and a year to date move of 14.86%. The 1 year total shareholder return of 21.68% and 5 year total shareholder return of 127.13% point to momentum that has been in place for some time.
Capitalize on Hyatt Hotels’ momentum shift by scanning our curated list of fee-rich hospitality and travel operators in the 19 high quality undiscovered gems.After that sharp move to US$190.18, Hyatt Hotels now trades only a touch below both analyst targets and intrinsic value estimates. Is this just fair value catching up, or has the pendulum already swung too far?
Most Popular Narrative: 6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Hyatt Hotels screens as modestly undervalued, with a fair value of $201.52 against the latest close at $190.18. That view leans heavily on the fee based model and room pipeline.
The shift toward an asset-light, fee driven model, supported by 9% to 11% expected gross fee growth in 2026 and at least 50% conversion of adjusted EBITDA to free cash flow, indicates a mix shift toward higher margin fee streams that can improve cash generation and earnings quality.
See why 6 investors see Hyatt Hotels as 6% undervalued.
Result: Fair Value of $201.52 (UNDERVALUED)
Still, weaker Middle East hotel revenues and softer Mexican all inclusive bookings, which already trim fee income by about US$25 million, could pressure the Hyatt Hotels thesis.
Find out about the key risks to this Hyatt Hotels narrative.
Another View: Hyatt Hotels On Earnings Multiples
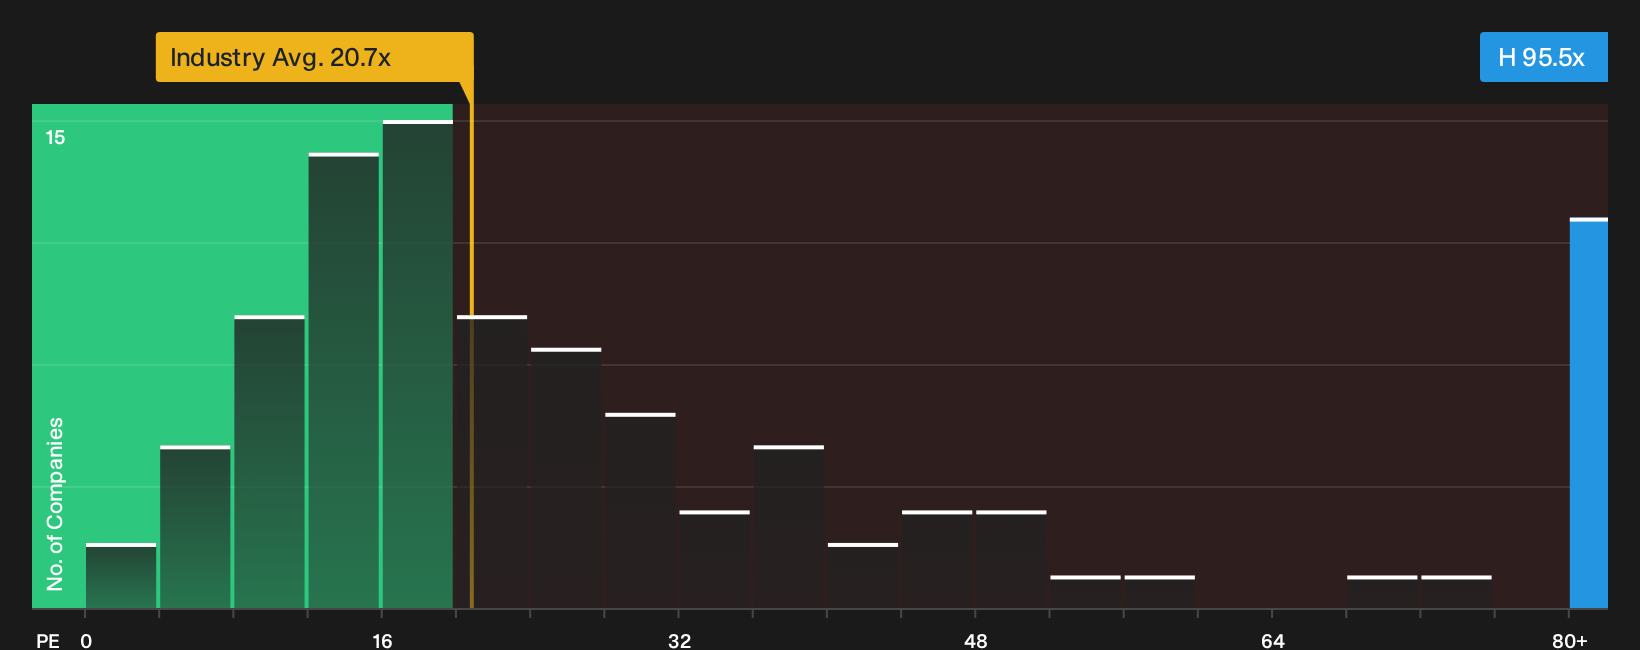
The cash flow workup suggests Hyatt Hotels is trading about 9.1% below an internal estimate of future cash flow value, yet the P/E ratio tells a very different story. At 95.5x earnings versus a fair ratio of 35.2x, buyers are paying almost triple the peer average of 13.2x for the same dollar of profit. This may be interpreted as a quality premium that some investors are comfortable with, or as valuation risk that others may prefer to avoid.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Hyatt Hotels valuation and quality often create valuable learning opportunities. Move quickly, review the full data set, and weigh both the upside and the weak spots through 3 key rewards and 3 important warning signs.
Ready For More Ideas Beyond Hyatt Hotels?
Hyatt Hotels might be front of mind today, but the next opportunity you act on could come from a very different corner of the market.
- Target steadier potential returns by focusing on resilient companies through a 30 resilient stocks with low risk scores that filters for businesses with lower risk scores.
- Hunt for quality at a reasonable price by scanning our 32 high quality undervalued stocks that highlights companies combining solid cash flows with attractive pricing.
- Prioritise financial strength and durability by reviewing a list of solid balance sheet and fundamentals (23 results) that surfaces businesses with healthier fundamentals than the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com