


Atlas Copco (OM:ATCO A) just finished Expansion Week US, a series of New York and South Carolina facility openings that push more compressor and vacuum pump production closer to American customers.
Atlas Copco’s Expansion Week US arrives alongside a mixed share price pattern, with a 1-day share price return of 2.5% and 7-day gain of 4.71% contrasting with a 30-day decline of 8.4%. At the same time, the 1-year total shareholder return of 24.22% and 5-year total shareholder return of 51.5% show momentum that has rewarded patient holders even as near term sentiment remains more cautious.
Scan other industrials repositioning production closer to key customers with the hand picked 42 power grid technology and infrastructure stocks that tie real assets to critical infrastructure themes, similar to Atlas Copco’s US expansion push.
The recent pullback after a strong multi year run leaves a simple tension. Are you looking at a solid Atlas Copco operation that is temporarily out of favor, or at a sentiment reset that now needs the valuation to catch up?
Most Popular Narrative: 14% Undervalued
On the analyst consensus Narrative on Simply Wall St, Atlas Copco screens as undervalued, with a fair value of SEK227.35 against the last close at SEK194.65. That gap reflects a set of expectations around growth, margins and capital deployment that extend well beyond the near term Expansion Week headlines.
Ongoing growth in service activity across all divisions and regions, including semi and industrial vacuum, compressors, Industrial Technique and Power Technique, continues to shift the mix toward higher margin aftermarket revenues that can support group operating margins around the low 20% level.
See why 34 investors see Atlas Copco as 14% undervalued.
Result: Fair Value of SEK227.35 (UNDERVALUED)
Still, the Atlas Copco story can change quickly if tariff costs bite harder than pricing can absorb, or if acquisition integration keeps margins stuck.
Find out about the key risks to this Atlas Copco narrative.
Another View: Atlas Copco Through The P/E Lens
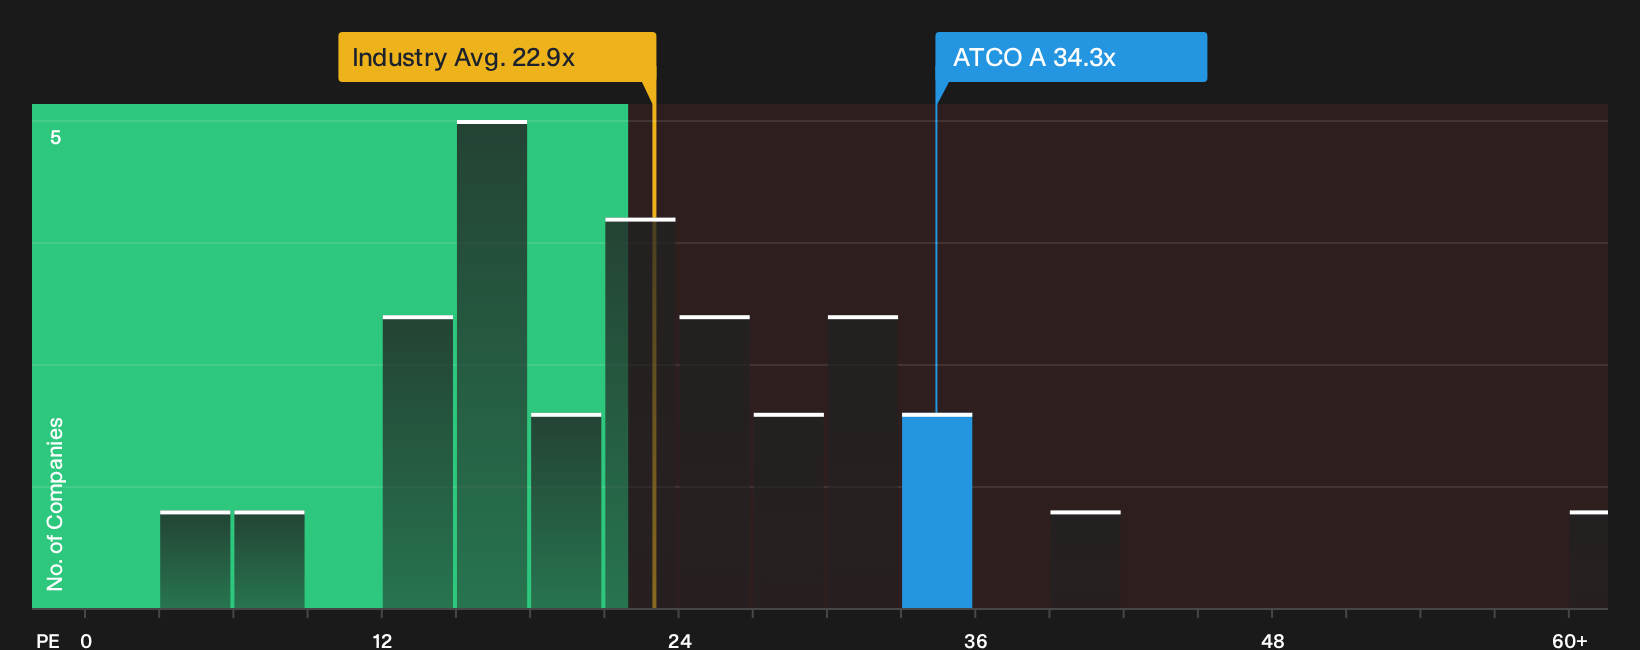
Atlas Copco may look undervalued on a cash flow basis, but its current P/E of 34.3x tells a tougher story. That ratio is richer than the Swedish Machinery industry at 22.7x, the wider peer group at 25.4x, and even above a fair ratio of 33.1x suggested by regression analysis.
In practice, that means a lot of good news is already built into the share price. If sentiment cools or earnings delivery slows, the market could push the multiple back toward that fair ratio. The real question for you is whether this premium feels like a margin of safety or a margin of risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between Atlas Copco’s premium P/E and the undervalued fair value narrative is normal. Move quickly and stress test the numbers yourself using the 3 key rewards.
Looking for more Atlas Copco style investment ideas?
If you stop with Atlas Copco, you risk missing other opportunities that match your style. Use the Simply Wall St Screener to hunt for ideas that fit your risk, income and value preferences.
- Target potential mispricings by scanning a 195 high quality undervalued stocks that highlight companies where fundamentals and current market prices appear out of sync.
- Strengthen your income stream by reviewing a 212 dividend fortresses built around higher yield opportunities that still keep financial resilience in focus.
- Prioritise resilience by working through a 206 resilient stocks with low risk scores that surfaces businesses with lower overall risk scores and steadier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com