


JetBlue Airways has seen its share price swing sharply in recent years, which puts a spotlight on a simple question for investors who care about the numbers: Is the current US$4.02 price tag adequately backed by the airline's sales, or is the market asking too much of the business today?
- Over the past 5 years the stock has fallen 72.2%. This puts pressure on the case that the present valuation can be supported by the revenue the airline is actually generating.
- Management's push into premium seating with the new BlueFirst product and the rapid expansion of the Fort Lauderdale hub can influence future ticket mix and route economics. This may affect how comfortably sales can support the current equity value.
- The analysts covering JetBlue Airways have run their own numbers. See what analysts think JetBlue Airways's shares could be worth.
The issue now is whether JetBlue Airways' recent share price level is justified by the sales the business is producing today and realistically aiming for over time.
If you are weighing whether JetBlue Airways’ US$4.02 price is well supported by its sales, it can help to compare it with a focused list of 32 high quality undervalued stocks.
Does JetBlue Airways Look Undervalued on Sales?
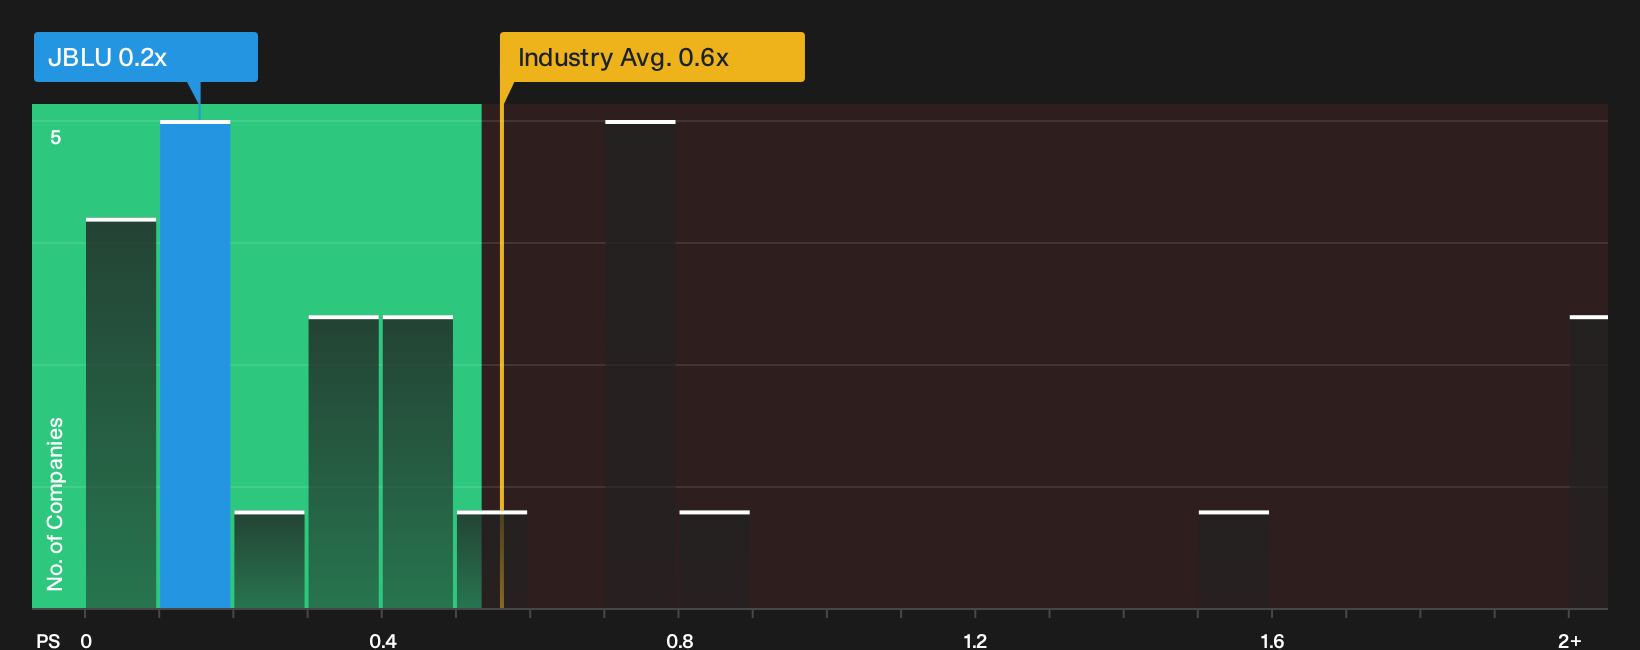
P/S works well for an airline like JetBlue Airways because investors often start by asking how much they are paying for each dollar of ticket and ancillary sales. Right now the stock trades at a P/S of about 0.2x, which is well below the broader airlines industry average of roughly 0.6x and also below peers around 0.5x. That gap means the market is valuing JetBlue’s revenue stream at a lower level than many comparable carriers.
Based on a more tailored fair multiple that factors in JetBlue’s business mix, size and risk profile, the current 0.2x P/S screens as undervalued rather than just different from the pack. Because the push into BlueFirst premium seating and the Fort Lauderdale hub buildout have focused attention on the turnaround plan, this lower P/S suggests that even with that news in play the stock price rests at a discount to what this framework would imply. Explore the numbers behind JetBlue Airways's P/S valuation.
The JetBlue Airways Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the JetBlue Airways valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth much more or much less than its current price, and they sit on the Community page. Each one treats JetBlue Airways' possible value as a thesis you can track over time, rather than a single frozen number.
Views on JetBlue Airways pull in opposite directions, with one group seeing meaningful upside and another arguing the risks still dominate.
Bull case: 42% undervalued
The bullish analyst Narrative on Simply Wall St leans on JetForward, Fort Lauderdale and premium cabins as the earnings swing factors.
"JetForward is now tracking toward approximately $1.2b of annual incremental EBIT and at least $1.00 EPS by 2028, which gives JetBlue Airways room to exceed current earnings expectations if mix shift, ancillary uptake and cost actions flow through more efficiently to net margins than models currently assume…"
Discover why this Narrative puts JetBlue Airways at 42% undervalued.
Bear case: 75% overvalued
The bearish analyst Narrative on Simply Wall St focuses on fuel costs, leverage and execution risk around those same JetForward targets.
"Although JetForward is on track to deliver around US$310 million of incremental EBIT in 2026 and a targeted US$1.2b annually by 2028, the company still guides to an operating margin loss of about 2% to 5% in 2026…"
Explore why this Narrative puts JetBlue Airways at 75% overvalued.
Before focusing on JetBlue Airways' price tag alone, there is one more angle to consider
Valuation is only one piece of the picture, and Simply Wall St's broader checks have picked up specific concerns around JetBlue Airways that prudent investors may want to review in detail before making any move. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com