


Amplitude (AMPL) just posted its third quarter 2026 results, giving investors a new snapshot of how its product analytics business is scaling while losses continue to weigh on the bottom line.
Amplitude's latest report lands after a strong run in the stock, with a 90-day share price return of 32.08% and a year-to-date gain of 57.46%. The 1-year total shareholder return of 58.91% contrasts with a much weaker 5-year total shareholder return of 74.86%, which reflects how much earlier investors have still given up over the longer stretch.
Scan how Amplitude compares with other fast-moving software and analytics plays by checking our hand picked 19 high quality undiscovered gems while this earnings momentum is front of mind.
After a 57.46% year-to-date surge and revenue still paired with meaningful losses, the question around Amplitude now is blunt. Is most of the easy upside already in the rear-view, or is the valuation still leaving real headroom?
Most Popular Narrative: 12% Overvalued
On the numbers, the analyst consensus Narrative on Simply Wall St pegs Amplitude's fair value at $15.36. This sits below the recent $17.21 close and frames the stock as pricing in a lot of good news already, even with revenue growth and AI adoption in the mix.
The rapid shift to a multiproduct platform, where 48% of customers use multiple products and over 26% of ARR comes from customers with five or more products, supports higher pricing uplifts that can push current valuation to assume continued expansion of ARR per customer and stronger free cash flow.
See why 10 investors see Amplitude as 12% overvalued.
Result: Fair Value of $15.36 (OVERVALUED)
Still, strong free cash flow at US$23.7 million and US$69 million of share repurchases could keep supporting confidence in Amplitude if those trends persist.
Find out about the key risks to this Amplitude narrative.
Another View: Cash Flow Says Amplitude Looks Cheap
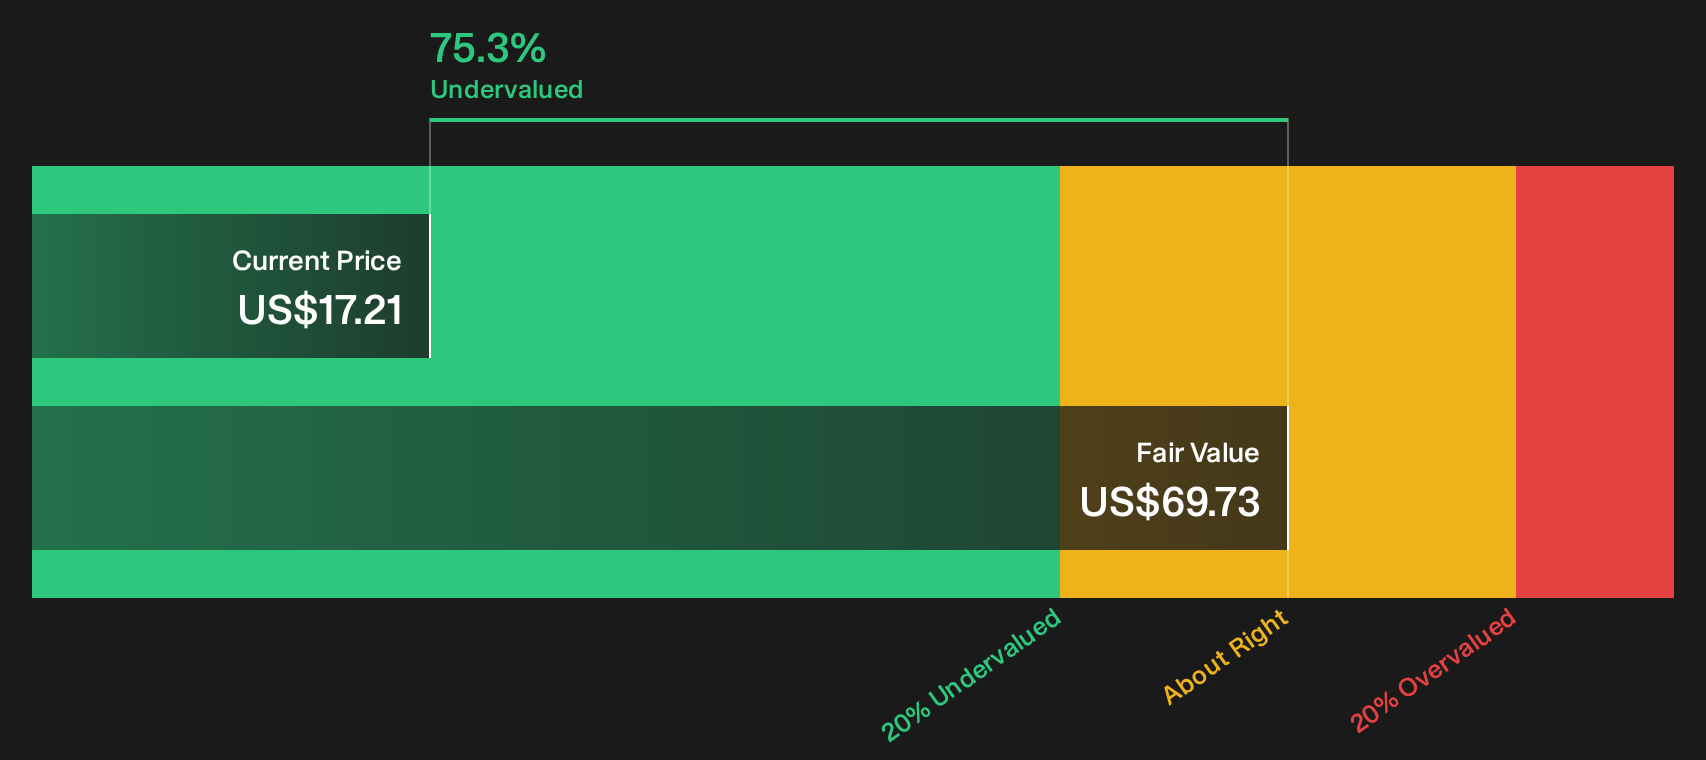
Price based signals point to Amplitude looking fully priced, yet the SWS DCF model paints a different picture. On that framework, the shares at $17.21 trade roughly 75% below an estimated future cash flow value of $69.73, which frames the debate less as upside chased and more as valuation gap. Which lens do you trust when the story and the spreadsheet disagree?
For investors who want to unpack how a cash flow model can land so far from a multiples driven fair value, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Amplitude so far. If this combination of potential upside and clear risk leaves you undecided, act quickly and compare both sides of the story with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Amplitude?
If Amplitude has your attention, now is the moment to broaden your watchlist with a few focused stock ideas that match how you like to invest.
- Target potential upside with companies that combine strong fundamentals and attractive pricing by scanning our 32 high quality undervalued stocks.
- Strengthen the income side of your portfolio by reviewing a curated set of higher yielding payers through the 6 dividend fortresses.
- Dial back risk without stepping away from opportunity by checking companies screened for sturdier finances using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com