


Suburban Propane Partners (SPH) recently drew fresh attention after its units closed at US$17.61, leaving the partnership with an equity value near US$1.18b and a long record in U.S. propane distribution.
Recent trading in Suburban Propane Partners has been subdued. The latest share price of US$17.61 comes after a small 1-day share price decline of 0.56% and a softer year-to-date share price return of 5.78% down. Longer term, total shareholder returns of 26.92% over three years and 68.73% over five years point to momentum that has been built over time rather than in the very recent past.
Scan other income plays showing similar long-run traction by comparing Suburban Propane Partners with our hand picked 6 dividend fortresses.
Suburban Propane Partners has already delivered solid multi-year gains, yet the units now sit slightly above the latest analyst target and at a large intrinsic discount. Is most of the upside already booked, or still in front of you as a holder of this stock?
Most Popular Narrative: 4% Overvalued
On the analyst consensus Narrative on Simply Wall St, Suburban Propane Partners screens as modestly overvalued, with a fair value of $17.00 against the latest close at $17.61. That view rests heavily on how renewable natural gas and related credits interact with the long running propane operation under a 7.39% discount rate.
Expanding renewable natural gas capacity toward anticipated annual injection of 750,000 to 800,000 MMBtu once all three facilities in Arizona, New York and Ohio are fully online is expected to add a distinct earnings stream that could support revenue and EBITDA while already being reflected in how Suburban Propane Partners is valued.
See why 6 investors see Suburban Propane Partners as 4% overvalued.
Result: Fair Value of $17.00 (OVERVALUED)
Still, that fair value case for Suburban Propane Partners depends heavily on policy support for RNG credits and on weather not repeating the warmer, volume hit periods analysts flagged.
Find out about the key risks to this Suburban Propane Partners narrative.
Another View on Suburban Propane Partners Valuation
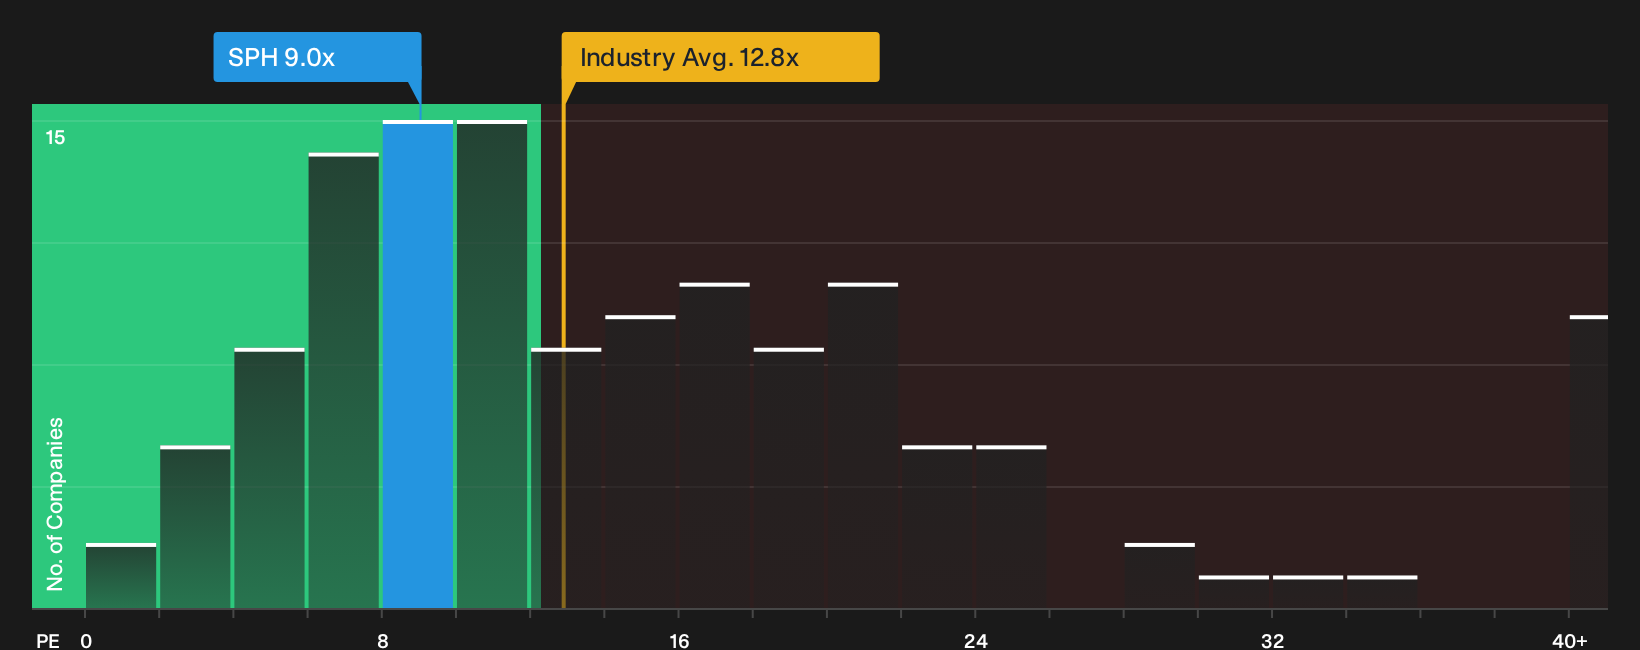
The analyst narrative treats Suburban Propane Partners as slightly overvalued at $17.61 against a $17.00 fair value. A simple earnings multiple offers a different perspective. The units trade on a P/E of 9x, while peers are near 16.9x and the industry around 12.5x, with a fair ratio of 13.5x. That gap points to a market that prices in meaningful risk, so the question is whether you see mispricing or justified caution.
To see how this earnings based picture compares with a fuller breakdown of the current price, review the See what the numbers say about this price — find out in our valuation breakdown. and consider where Suburban Propane Partners might gravitate relative to that fair ratio over time.
Next Steps
Mixed messages on Suburban Propane Partners so far, right. If you want to move quickly and build your own stance around the risk and reward balance, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Suburban Propane Partners?
If Suburban Propane Partners has your attention, do not stop here. Broadening your watchlist with fresh ideas can reshape your portfolio’s income, resilience, and growth potential.
- Lock in potential income resilience by comparing Suburban Propane Partners with our high yield 6 dividend fortresses that focus on durability alongside payout.
- Target better risk control by screening for 30 resilient stocks with low risk scores that may help steady your returns when individual positions move against you.
- Unearth fresh opportunities early by scanning 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com