


Triumph Financial (TFIN) has been drawing attention after recent share price moves, with the stock closing at US$60.80. Investors are weighing that level against the bank's latest revenue and profit figures.
Recent trading has been choppy for Triumph Financial. The 1-day share price return declined 1.27%, the 7-day move is down 6.32%, and the 90-day share price return is down 22.48%, even though the 1-year total shareholder return is positive at 11.99%.
Spot under-pressure financials like Triumph Financial and compare them with our hand picked 30 resilient stocks with low risk scores that pair resilient balance sheets with more muted share price swings.Bulls see Triumph Financial as a growing specialty lender whose recent pullback opens a window. Bears point to the longer term share price record. Which story fits the current valuation?
Most Popular Narrative: 19% Undervalued
On the analyst consensus Narrative on Simply Wall St, Triumph Financial is tagged with a fair value of $75 against a last close of $60.80. This frames the current pullback as a discount to the level implied by their long term cash generation assumptions and freight focused fee model.
The continued mix shift from traditional banking toward higher margin fintech and intelligence offerings, which are expected to represent a greater share of Triumph Financial’s revenue base, supports a higher contribution from fee income and potentially stronger returns on assets.
Ongoing repricing of transactions on Triumph Financial’s payments network onto per invoice fees, combined with broader use of audit services and LoadPay within the same customer base, can lift revenue per transaction and expand EBITDA margins in the core payments business.
See why 2 investors see Triumph Financial as 19% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, Triumph Financial’s reliance on freight linked factoring and payments, along with weaker core banking revenue, could quickly challenge this 19% undervalued narrative.
Find out about the key risks to this Triumph Financial narrative.
Another View: Triumph Financial Looks Pricey On Earnings
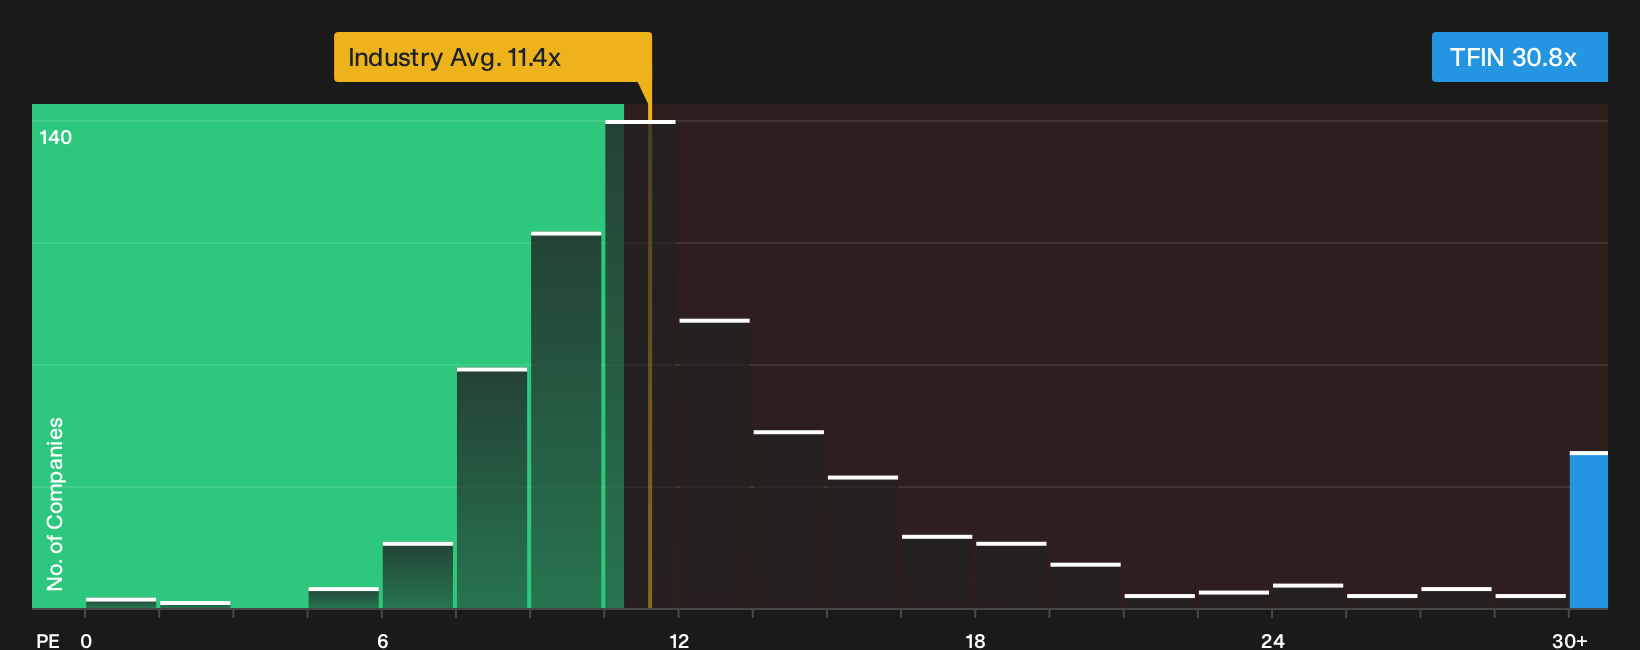
The fair value narrative pegs Triumph Financial at US$75, yet the share price already reflects a rich earnings multiple. The stock trades on a P/E of 30.8x, compared with about 11.6x for peers, 11.3x for the wider US Banks group, and a fair ratio estimate of 17.9x that our data suggests the market could move toward. That gap points to meaningful valuation risk if sentiment shifts away from freight focused fee stories.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages can leave Triumph Financial feeling hard to pin down, so move quickly, review the full data set, and weigh the 3 key rewards and 3 important warning signs.
Want more ideas beyond Triumph Financial?
If Triumph Financial feels finely balanced, do not stop there. Broaden your watchlist with other targeted ideas that fit different roles in your portfolio.
- Hunt for potential bargains using our data driven list of 32 high quality undervalued stocks that blend quality fundamentals with discounted share prices.
- Prioritize resilience by scanning a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when conditions turn tougher.
- Surface under-followed opportunities by sifting through 19 high quality undiscovered gems that pair strong financials with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com