


Veeco Instruments (VECO) is back on investors' radar after releasing third quarter 2026 results along with fresh guidance for the upcoming quarter and full year, giving the market new data to digest.
The immediate reaction has been strong, with Veeco Instruments' 1 day share price return of 3.46% and 7 day share price return of 13.69% reversing some of the recent pressure that left the 30 day share price return down 16.88% and the 90 day share price return down 23.61%.
Even with that short term volatility, the stock still carries a year to date share price return of 34.02%. Longer term investors have seen a 1 year total shareholder return of 34.90% and a 5 year total shareholder return of 53.35%, during which time the market has gradually adjusted its view on Veeco Instruments' risks and opportunities.
Scan how Veeco Instruments compares to other chip equipment players under fresh earnings pressure by reviewing the hand picked 53 AI infrastructure stocks now shaping investor watchlists.
After Veeco Instruments’ sharp bounce, the share price now sits well below both analyst targets and intrinsic estimates. Is that discount pointing to mispricing, or simply reflecting the risk profile investors see today?
Most Popular Narrative: 30% Undervalued
On the analyst consensus Narrative on Simply Wall St, Veeco Instruments screens as undervalued, with a fair value of about $58.67 versus the last close at $40.93. This frames today’s rebound inside a much larger valuation gap built on specific growth and margin assumptions.
Ongoing AI and high performance computing build outs are feeding multi year demand for Veeco Instruments annealing and advanced packaging tools. Management points to served markets that they size at about US$1.3b for annealing and about US$1b for advanced packaging by 2030, which directly targets future equipment revenue and earnings. Broader exposure to memory, data storage and GaN power tools is giving Veeco Instruments additional drivers beyond core logic and foundry. This includes expectations for compound semiconductor revenue to approximately double in 2026, a US$250m GaN power market by 2030 and full HDD system bookings into 2027, all of which are directed at future revenue diversification and earnings durability.
See why 10 investors see Veeco Instruments as 30% undervalued.
Result: Fair Value of $58.67 (UNDERVALUED)
Still, the Veeco Instruments story depends on smooth capacity expansion and clean export approvals, and setbacks on either front could quickly challenge that 30% undervalued narrative.
Find out about the key risks to this Veeco Instruments narrative.
Another View: What Multiples Say About Veeco Instruments
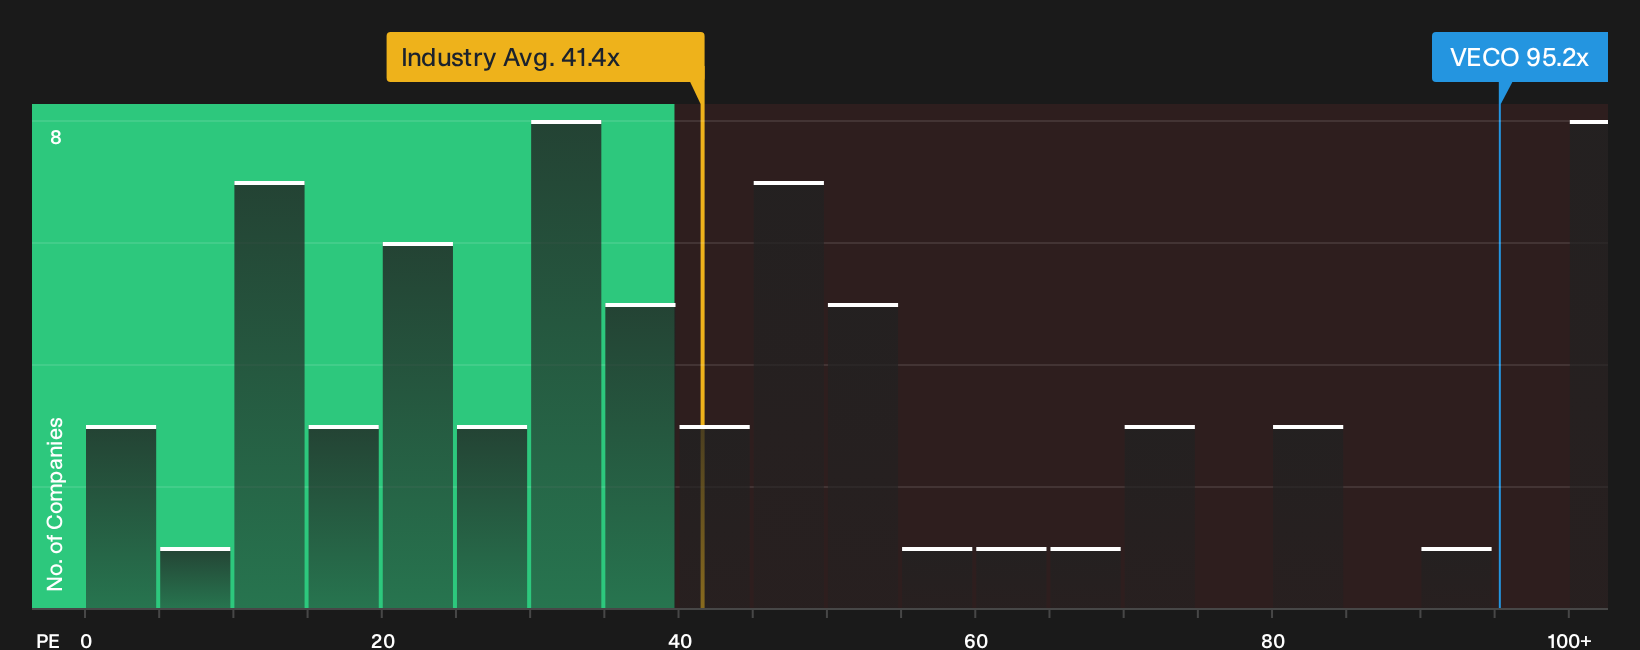
The first story around Veeco Instruments leans heavily on fair value estimates and cash flow assumptions. A simpler lens looks at the current P/E of 95.2x versus the US Semiconductor industry on 39.1x and peers on 57.2x, while the fair ratio sits even higher at 105x.
That mix tells a different story. On one hand, the stock trades at a premium to both sector and peer averages, which raises the bar for future delivery. On the other hand, the fair ratio suggests the market could still shift higher if earnings unfold as expected. Which signal do you treat as more important right now: the premium to the group or the gap to that fair ratio target?
For a closer look at how this valuation lines up against earnings expectations and peer pricing, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Veeco Instruments so far. If you want to move fast and base your decision on the data, consider both perspectives with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Veeco Instruments?
Do not stop at Veeco Instruments. Some opportunities may come from comparing this story with other stocks that show different strengths and risk profiles.
- Look for potential mispricing by scanning companies that currently screen as high quality and undervalued through the 32 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses that appear to have robust finances and low risk scores using the 30 resilient stocks with low risk scores.
- Explore possible future leaders by checking out stocks that look like high quality undiscovered ideas inside the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com