


Eagle Materials (EXP) just posted quarterly results that showed higher sales but lower profit compared with a year earlier, a mix that often forces investors to reassess how much they are willing to pay for the stock.
Eagle Materials shares have pulled back, with a 7 day share price return of down 7.0% and a 90 day share price return of down 11.8%, even though the 30 day share price return is up 12.6% and the 5 year total shareholder return is 18.2%.
Scan how Eagle Materials compares with other construction and materials plays by tracking a curated set of resilient balance-sheet stocks in our list of solid balance sheet and fundamentals (23 results).
Eagle Materials now trades below both analyst targets and some intrinsic estimates after that pullback. Is the fair value closer to the market’s cooler view, or to the richer modelled range investors are eyeing next?
Most Popular Narrative: 6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Eagle Materials screens as modestly undervalued, with a fair value of $195.50 against a last close of $184.24. This puts the share price at a single digit discount to those modelled cash flows.
Substantial ongoing federal and state infrastructure funding, together with robust data center and nonresidential construction that now make up about 80% of Eagle Materials heavy side exposure, is supporting strong cement and aggregates volumes and can continue to underpin revenue and earnings as these multi year project pipelines are worked through.
See why 7 investors see Eagle Materials as 6% undervalued.
Result: Fair Value of $195.50 (UNDERVALUED)
Still, the analyst story around Eagle Materials can break if housing demand stays weak for longer or if the big Mountain Cement and Duke Wallboard upgrades miss cost saving goals.
Find out about the key risks to this Eagle Materials narrative.
Another View: Eagle Materials Through The P/E Lens
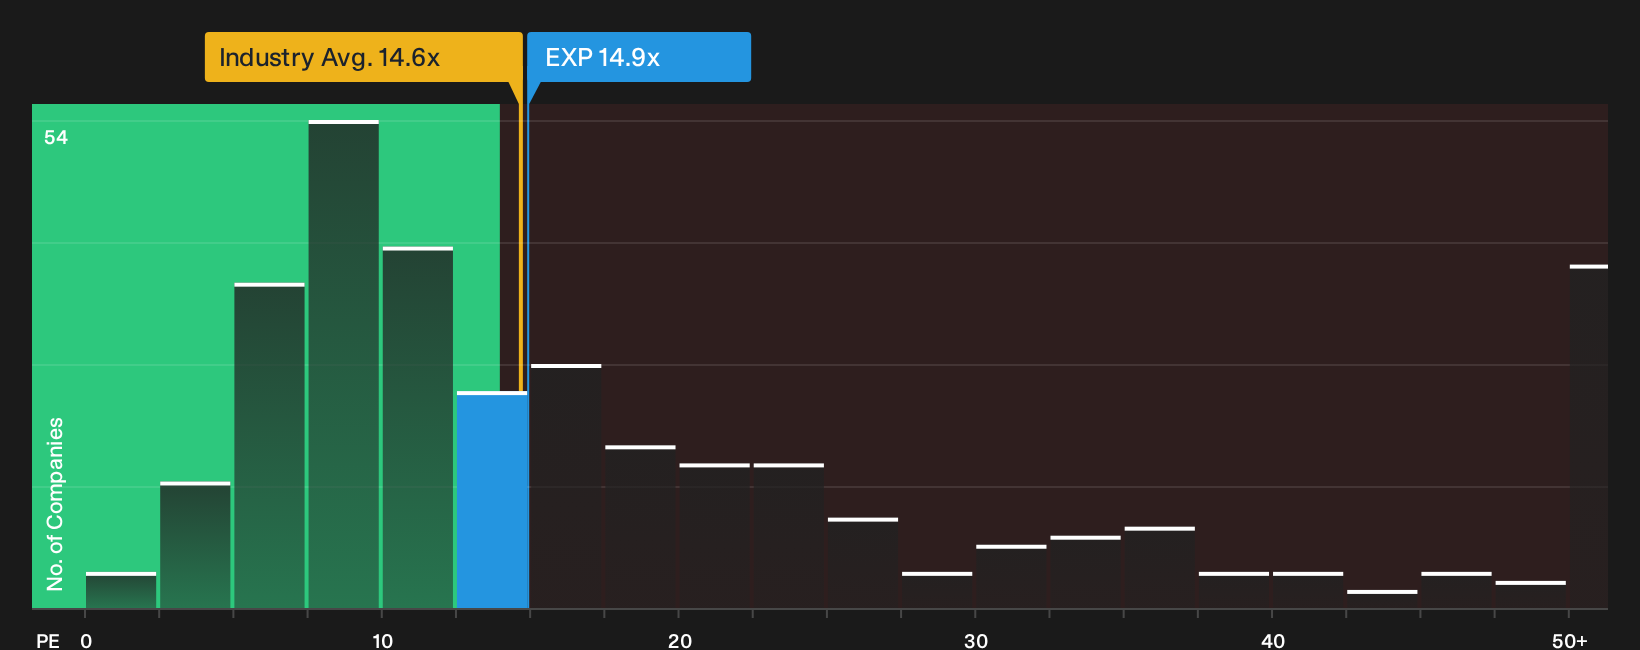
The SWS DCF workup points to Eagle Materials trading at a 36% discount to an estimate of future cash flow value, while the P/E picture looks tighter. The stock sits at 14.9x earnings, fractionally above the global Basic Materials group at 14.8x and roughly in line with a 14.8x fair ratio, which keeps the question open. Is this really a discount story, or just fairly priced with solid execution risk on top?
For a closer look at how that single earnings multiple stacks up against peers and the fair ratio, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Eagle Materials valuation can feel confusing. Move quickly, review the numbers yourself, and weigh both the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Eagle Materials?
Do not stop with Eagle Materials. Broaden your watchlist with a few targeted stock ideas that match your risk comfort and return ambitions using focused screeners.
- Target potential mispricing by checking companies that pass quality filters yet still trade at a discount in the 32 high quality undervalued stocks.
- Prioritize capital protection first and search for businesses that score well on resilience and risk metrics through the 30 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities by reviewing financially sound businesses that remain off most radars in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com