


- Insulet reported third quarter 2026 revenue of US$842 million and net income of US$141.1 million, with earnings per share from continuing operations of US$2.03, and paired these results with a new US$1.0b share repurchase program running through 2028.
- The company narrowed full year 2026 revenue guidance to the high end of its prior range and issued double digit growth expectations for fourth quarter sales. This points to management prioritising consistent execution and capital returns alongside heavier investment in Omnipod adoption, type 2 diabetes penetration, and international expansion.
- We will now look at how Insulet's stronger third quarter earnings and higher full year guidance could influence its broader investment narrative.
Scan Insulet's latest update alongside a curated field of peers and see which other growth-focused healthcare stocks are breaking out in our 37 healthcare AI stocks.
Insulet Investment Narrative Recap
To own Insulet, you need to believe the Omnipod ecosystem can keep adding users across type 1 and type 2 diabetes, and then keep them. The analyst consensus Narrative on Simply Wall St leans on that recurring pod stream and margin profile. The third quarter beat and tighter full year guidance support that operating story rather than reshaping it.
The short term swing factor still sits in type 2 adoption and retention, where utilization remains weaker than type 1. That pressure, plus recall and lawsuit overhangs, is the biggest risk. Stronger earnings and cash generation help Insulet absorb these issues but do not remove them.
The new US$1.0b share repurchase program running through 2028 is the announcement that ties closest to this earnings release. It signals that Insulet expects to generate enough cash from Omnipod growth to fund both reinvestment and buybacks while maintaining its current operating priorities.
For you, the key question is how this plan interacts with the existing catalysts. If Omnipod 5 expansion, type 2 penetration, and international rollouts track the analyst consensus Narrative on Simply Wall St, a shrinking share count could amplify per share metrics. If type 2 attrition, pricing pressure, or recall related costs worsen, this capital allocation choice could become more of a constraint than a tailwind.
What the Current Insulet Forecasts Assume
Insulet's narrative projects US$4.4b in revenue and US$666.5m in earnings by 2029. That profile aligns with analyst assumptions of 11.7% yearly revenue growth and an earnings increase of about US$237.8m, from current earnings of US$428.7m to the 2029 consensus figure.
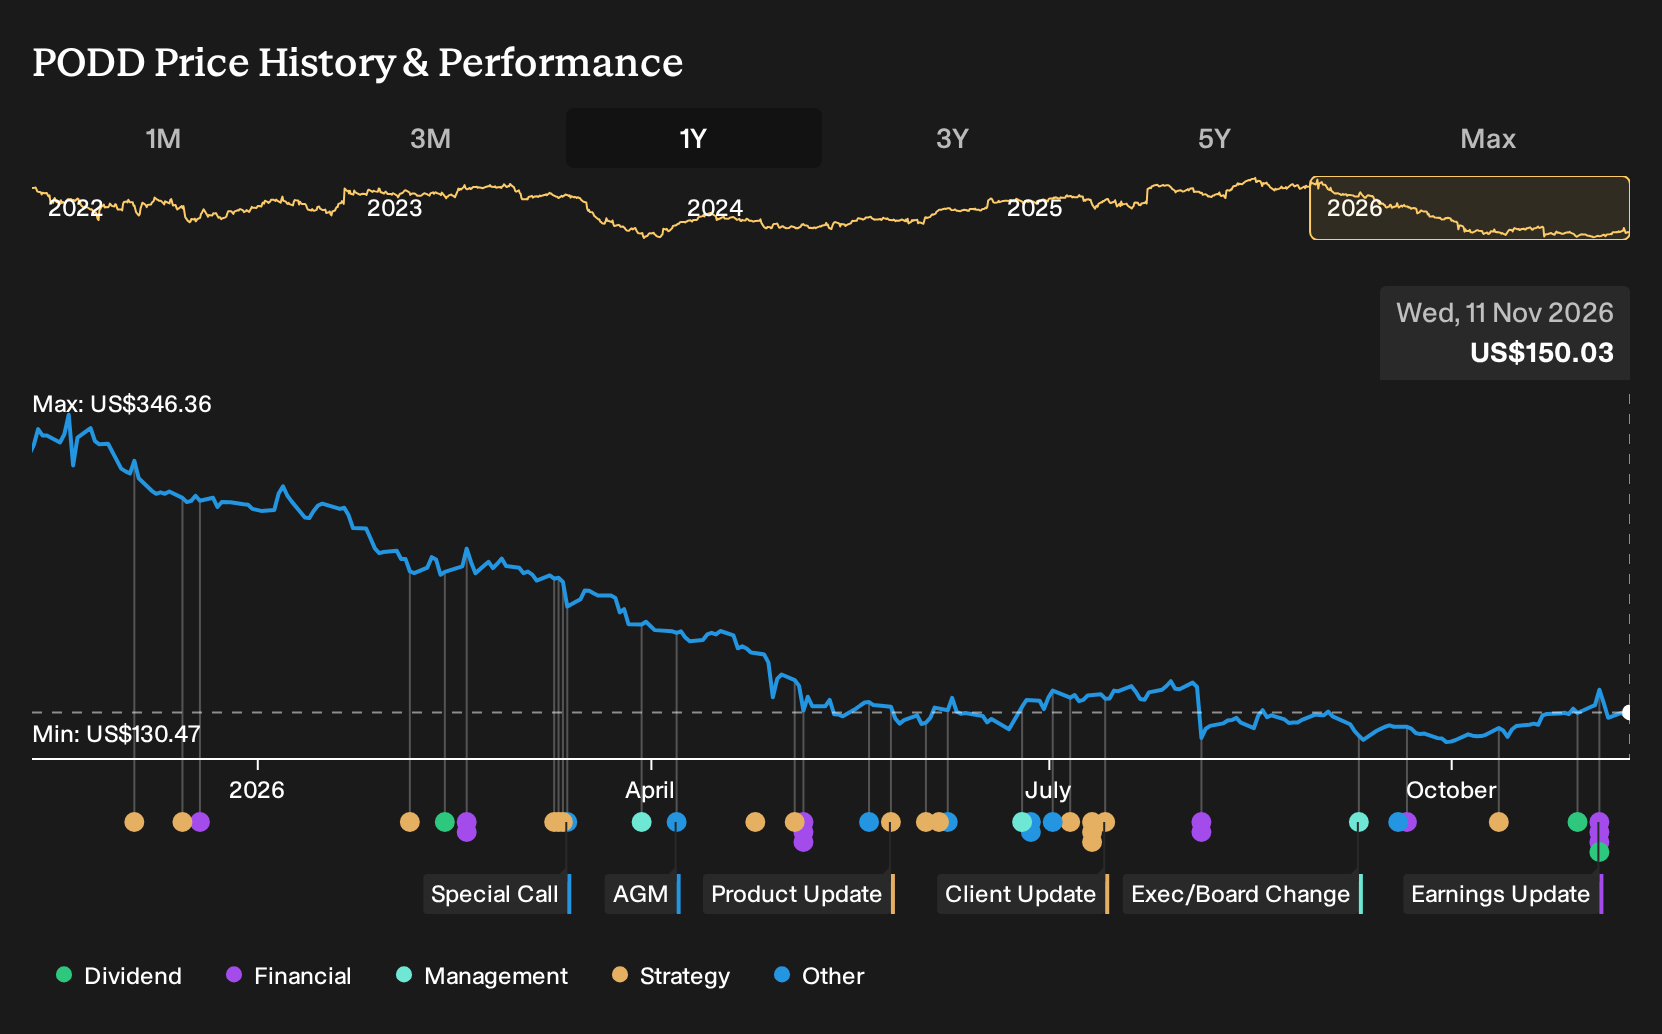
Uncover why Insulet's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Insulet leans heavily on a slower Omnipod ramp in type 1 diabetes. The most cautious analysts were only penciling in about US$4.2b of revenue and US$616.8m of earnings by 2029 before this report. That is a much more muted story. Use the new earnings beat and buyback news to test which narrative you find more convincing.
Explore 4 other Insulet fair value estimates, including one that suggests as much as 20% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Insulet research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Insulet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insulet's overall financial health at a glance.
Looking for more investment ideas beyond Insulet?
Once you have formed a view on Insulet, it often helps to stack that thesis against other opportunities so you can decide where your next dollar of capital should go.
- If you want to focus on stability first and returns second, start with a 30 resilient stocks with low risk scores to see which businesses our models flag as more resilient.
- For investors hunting for quality at a reasonable price, a 32 high quality undervalued stocks can spotlight companies where fundamentals and pricing currently look out of sync.
- When your priority is balance sheet strength and durable fundamentals, run a list of solid balance sheet and fundamentals (23 results) to find candidates that may better withstand tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com