


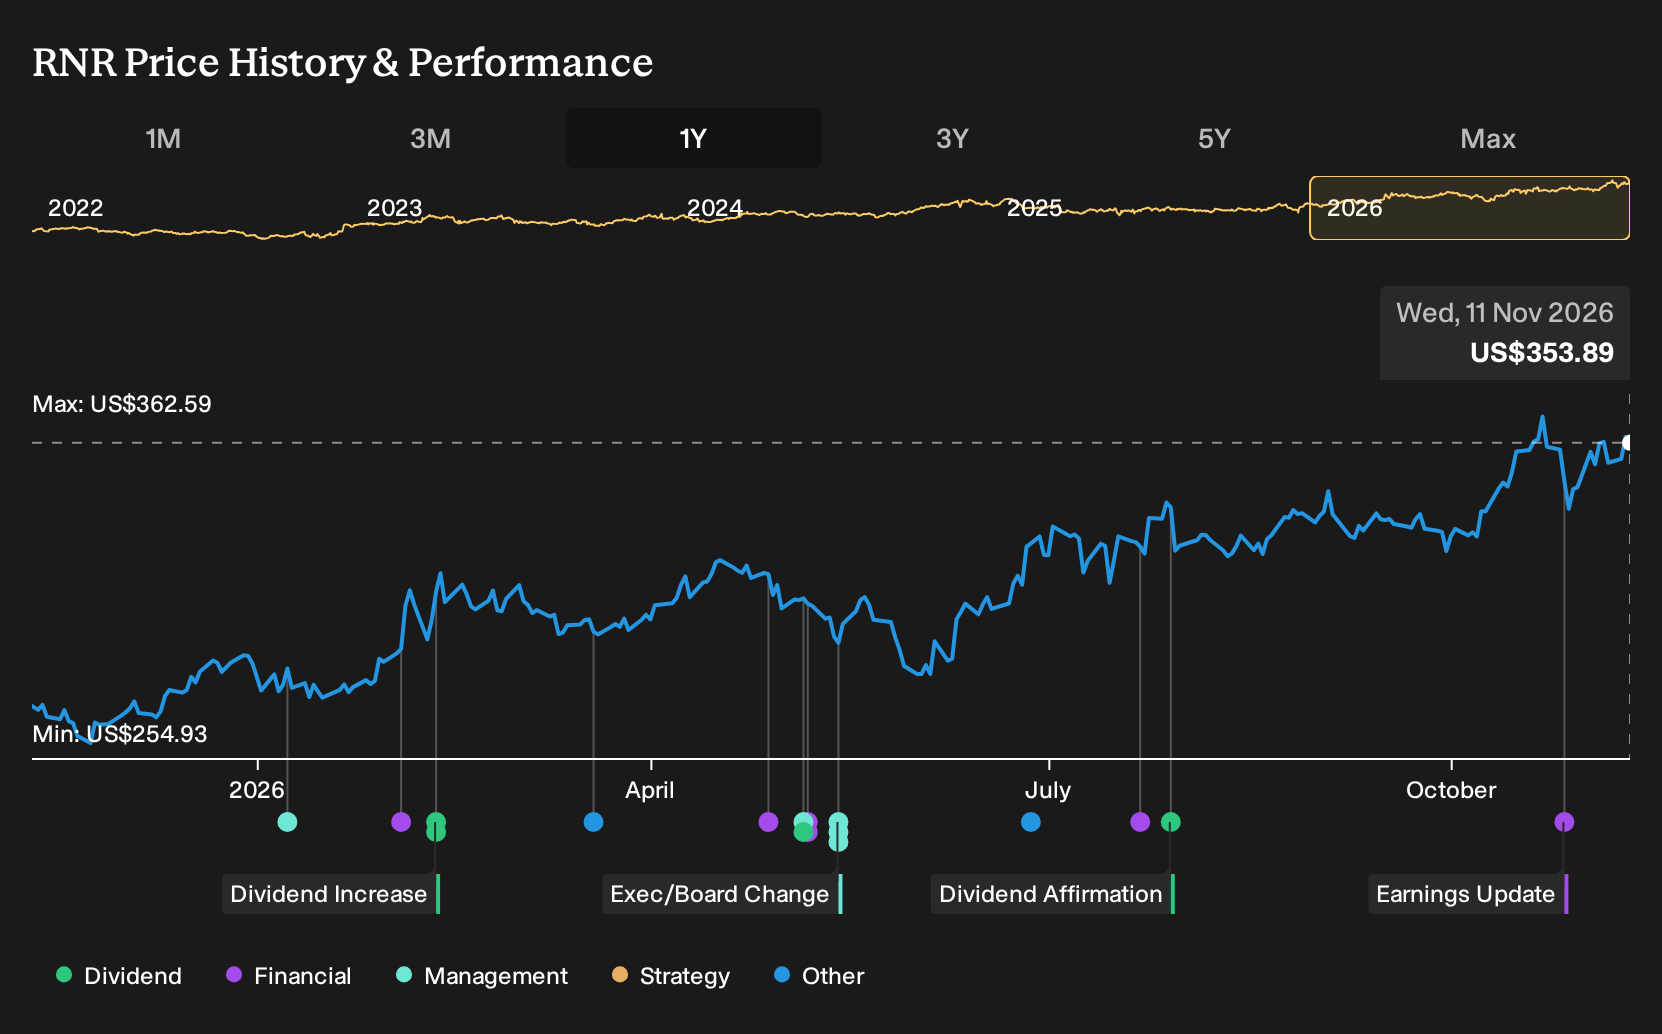
If you had been weighing RenaissanceRe in November 2025, you were looking at analysts who saw a hard reinsurance market as both an opportunity and a threat. For RenaissanceRe shareholders, the return over the past year was 33.8%, including dividends. Early buyers had to decide if shrinking revenue forecasts, higher catastrophe exposure, and growing alternative capital were acceptable trade-offs for fee income growth, capital strength, and new underwriting tools. Which of those moving pieces would have mattered most to you?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made RenaissanceRe harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Two Stories Investors Were Arguing Over On RenaissanceRe
The shares cost US$267 at the start of the period, and RenaissanceRe sat between two credible stories about what might come next.
On the optimistic side, one Narrative saw Fair Value at US$281, about 5% above the start price. That view leaned on fee income growth and assumed revenue would decline 7.2% a year while profit margin settled near 14.4%, supported by a future P/E of 8.5x in three years.
The more cautious camp put Fair Value closer to US$237, about 11% below the start price. That bear case stressed catastrophe exposure and integration risk, and assumed revenue would fall 9.0% annually with margins around 14.5% and a future P/E of 7.5x.
What The Results Changed For The RenaissanceRe Narrative
RenaissanceRe’s Q3 2026 report showed revenue of US$1.69b against US$3.20b a year earlier, with net income swinging from a US$892.6m profit to a US$162.0m loss and net margin moving from 27.9% to -9.6%. That outcome challenged the optimistic case built on resilient profitability and the evidence leaned toward the cautious story on earnings risk.
The lesson is simple. When a thesis leans on margin stability, track net margin and absolute profit first, then ask whether one rough quarter reflects underwriting choices or a deeper change in the business model.
What RenaissanceRe’s Run Leaves You Paying For Today
Today RenaissanceRe trades at US$354 after a 33.8% gain over the past year. The bearish analyst Narrative on Simply Wall St sets its Fair Value below that level and frames the current tag as already baking in a strong balance sheet, solid recent ROE and healthy fee and investment income.
To pay that price, you need to ask what must keep going right and whether RenaissanceRe’s multi driver earnings mix can offset expense pressure, casualty volatility and softer property catastrophe pricing without eroding returns.
"The main thing that has to go right is that RenaissanceRe Holdings needs its multi driver earnings model, including underwriting, fee income and record retained net investment income, to offset higher expense ratios and the impact of casualty and specialty volatility so that returns on equity remain attractive."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond RenaissanceRe’s Playbook
If RenaissanceRe has you thinking about underwriting quality and capital strength, you are not alone. The next step is asking who tackles those same problems differently.
One large insurer is building an AI ready technology stack. It wants underwriting, claims and customer contact connected by data rather than manual work.
The goal is straightforward. Use those tools to manage costs, refine pricing and handle high frequency risks with greater precision.
Life and health contracts add another angle. Here, the focus is reshaping portfolios so earnings lean on releasing expected profit over time instead of chasing headline volumes.
If that mix of AI driven efficiency and reworked life business takes hold, the earnings profile may eventually diverge sharply from RenaissanceRe’s catastrophe tilted story.
That argument has a Narrative and a number behind it. → See the company one Narrative values 43% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com