


- Schrödinger reported third quarter 2026 sales of US$26.34 million and revenue of US$64.49 million, with a net loss of US$37.71 million and basic loss per share from continuing operations of US$0.50.
- Over the first nine months of 2026, Schrödinger’s revenue reached US$181.97 million, while the reported net loss of US$91.76 million and lower basic loss per share of US$1.23 point to a business still investing heavily but showing different loss dynamics compared with the same period a year earlier.
- We will now look at how Schrödinger’s larger nine month revenue base and changing loss profile could influence its investment narrative.
Compare Schrödinger’s heavy R&D spend with peers and scan for other research driven stories using our curated list of 37 healthcare AI stocks.
Schrödinger Investment Narrative Recap
To own Schrödinger, you need to believe its physics based and AI heavy discovery engine can eventually turn today’s high R&D and hosted software focus into a more self funding model. The latest quarter shows a larger revenue base but also a net loss of US$37.71 million, so the firm remains in investment mode.
In the near term, the key catalyst flagged in the analyst consensus Narrative on Simply Wall St is execution on drug discovery milestones and hosted software adoption that can support more recurring revenue. The biggest current risk is that compressed software margins and continued reported losses persist, which this quarter’s higher loss per share does not meaningfully reduce.
The same analyst consensus Narrative on Simply Wall St points to over US$750 million of realized economics from partnered programs and guidance for about US$150 million of drug discovery revenue over three years as a core part of the story. This matters when you look at the latest results because the drug discovery segment sits alongside software as a second engine.
If milestones and collaboration payments arrive in line with that guidance, they could help offset some of the pressure from hosted mix headwinds and swings from equity holdings that affected Q3. If they disappoint, the burden stays on software margin improvement and cost control to narrow losses while Schrödinger continues to invest in agentic AI and predictive toxicology.
Schrödinger's current earnings are a loss of US$59.3 million. Analysts are assuming revenue will grow by 12.9% annually, with expectations for 2029 revenue of US$387.5 million and earnings of US$29.6 million. That implies an earnings swing of about US$88.9 million from today to the 2029 forecast.
Uncover why Schrödinger's fair value is essentially aligned with its current price.
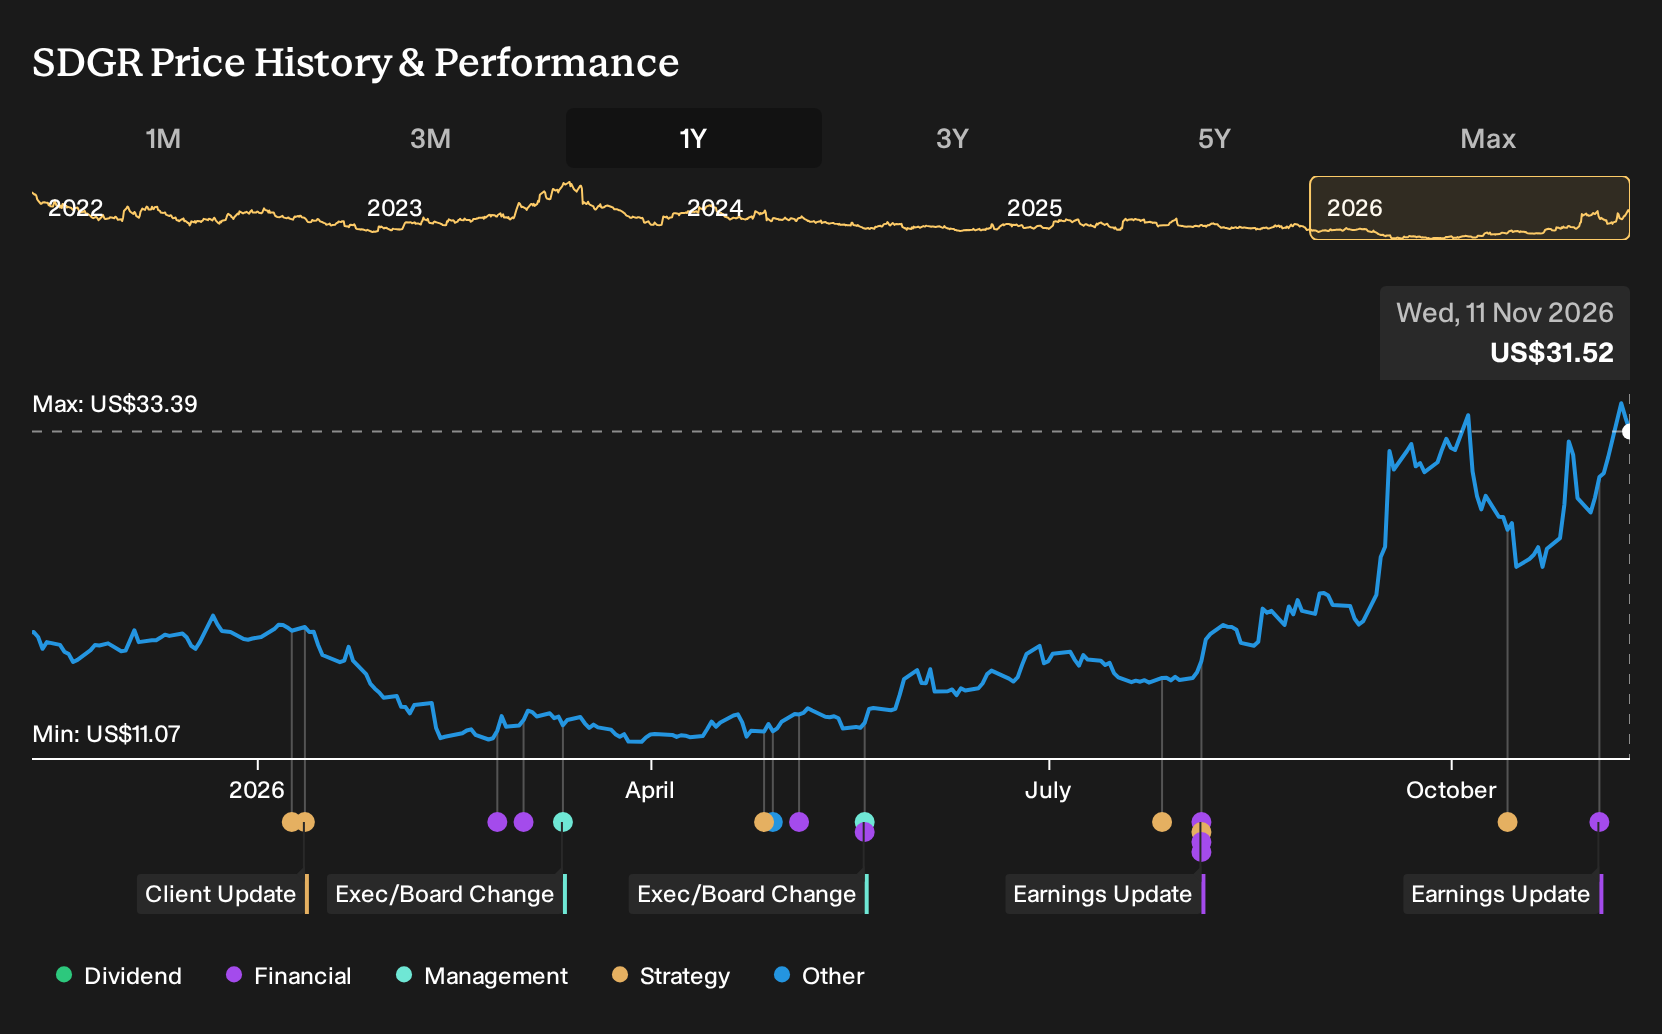
Exploring Other Perspectives
One alternate view focuses on hosted software pressure. The most cautious analysts were assuming Schrödinger’s revenue in 2029 might reach about US$267.9 million with earnings of roughly US$20.3 million, which is well below the consensus. That camp signals a flatter path and suggests this latest earnings update could shift expectations again.
Explore 3 other Schrödinger fair value estimates, including one that suggests it could be worth just $31.14.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Schrödinger research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Schrödinger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Schrödinger's overall financial health at a glance.
Looking for more Schrödinger investment ideas?
If this update on Schrödinger has sharpened your thinking and you want fresh angles beyond a single stock, the Simply Wall St Screener can help you map out a broader watchlist that fits your approach to risk, quality, and income.
- If capital preservation matters most to you, start with a group of companies screened for resilience and lower risk using our 30 resilient stocks with low risk scores.
- If attractive entry points are your focus, scan a curated set of businesses that pair quality fundamentals with appealing valuations through the 32 high quality undervalued stocks.
- If you are building a portfolio around dependable balance sheets and solid fundamentals, filter for financially robust stocks using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com