


ImmunityBio has seen its share price swing sharply, yet the real question now is whether the current valuation is properly anchored to the sales the business is actually generating. After a volatile run, the issue for anyone looking at ImmunityBio stock is how the revenue line stacks up against the market value being placed on those shares.
- ImmunityBio is up 233.5% over the past year, which puts a lot of pressure on its sales to justify the market value now attached to the company.
- Recent progress with ANKTIVA, including expanded approvals and new market launches, may support expectations for higher future product revenue, and it also raises questions about the spending and funding required to support that growth path.
- There is a second opinion on ImmunityBio worth weighing. See what analysts think ImmunityBio's shares could be worth.
The stock's next move may depend on whether the current share price looks reasonable when lined up against ImmunityBio's sales performance.
If you want to stress test the same sales versus valuation question driving ImmunityBio across a wider field, it helps to compare it with 32 high quality undervalued stocks.
Has ImmunityBio Run Too Far on Sales?
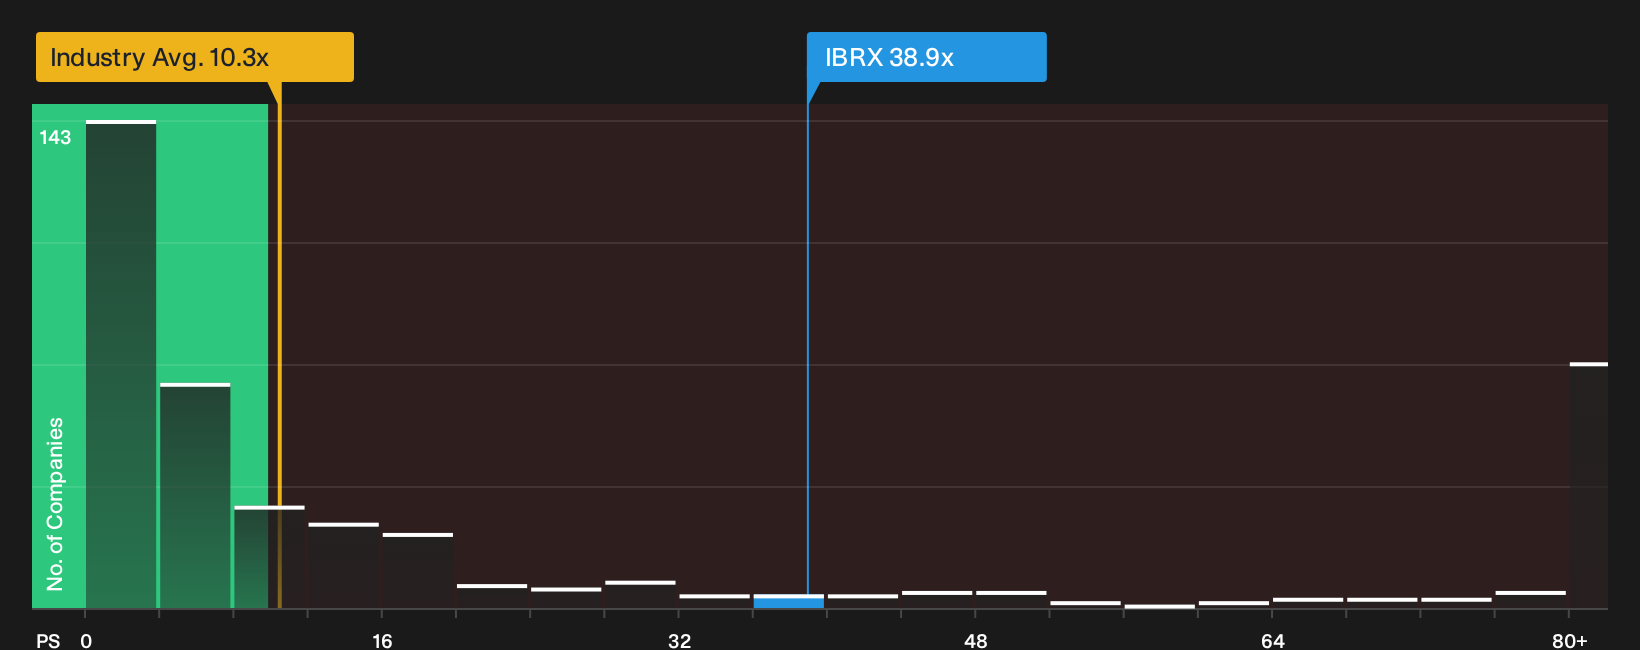
P/S tends to matter most for a biotech like ImmunityBio where reported earnings are still shaped heavily by research and commercialization costs. On this yardstick, the stock currently trades on a P/S of 38.9x, compared with a Biotechs industry average of 10.3x and a peer group average of 13.3x, so the share price implies a much richer valuation per dollar of sales than many rivals.
Because the Fair Ratio blends factors like growth expectations, profitability potential, size and risk, it indicates a lower P/S than where ImmunityBio actually trades. This points to the stock screening as overvalued on this framework. In light of the recent Anktiva trial result and label expansion, that gap suggests investors would require strong conviction about future product uptake and funding plans to view the current P/S level as reasonable relative to alternative biotech opportunities. Explore the numbers behind ImmunityBio's P/S valuation.
The ImmunityBio Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the ImmunityBio valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each scenario links its number to a clear view on how ImmunityBio's expansion, profitability and risk profile might evolve, giving you something concrete to revisit as new information arrives.
One of the top narratives on ImmunityBio: 53% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St. It compiles analysts' consensus price target and revenue and earnings forecasts, rather than reflecting one person's view.
"The decade long shortage of BCG for bladder cancer and ImmunityBio’s recombinant BCG program, already serving hundreds of patients under expanded access, position the company to address a chronic supply issue in urology…"
Discover why this Narrative puts ImmunityBio at 53% undervalued.
One more ImmunityBio check that belongs beside the price tag
Price and sales only tell part of the story for ImmunityBio, because our broader review has also flagged specific risk checks that could change how you see the whole picture. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com