


Willdan Group has been on a long, volatile ride, with the share price moving sharply over recent years while short term returns have been weak. With fresh earnings news and a bigger energy services footprint, the key question is whether the current market value is properly supported by the business's earning power.
- Over the past 3 years the stock has gained 229.1%, which puts real pressure on the underlying earnings story to justify how far the price has come.
- The completed US$285m purchase of Mantis Innovation gives Willdan a larger platform in energy efficiency and advisory work, which can influence future profit margins and the timing of cash generation that investors plug into earnings based valuation frameworks.
- Your read on Willdan Group is one view; the desks covering it have another. See what analysts think Willdan Group's shares could be worth.
The issue now is whether Willdan Group's current price is reasonable when weighed against the earnings it produces today and what investors expect it to produce in the future.
If you want to test the same earnings based valuation question you are asking of Willdan Group across a broader set of ideas in the energy and infrastructure ecosystem, take a look at 42 power grid technology and infrastructure stocks.
Where Does Willdan Group Sit on Earnings?
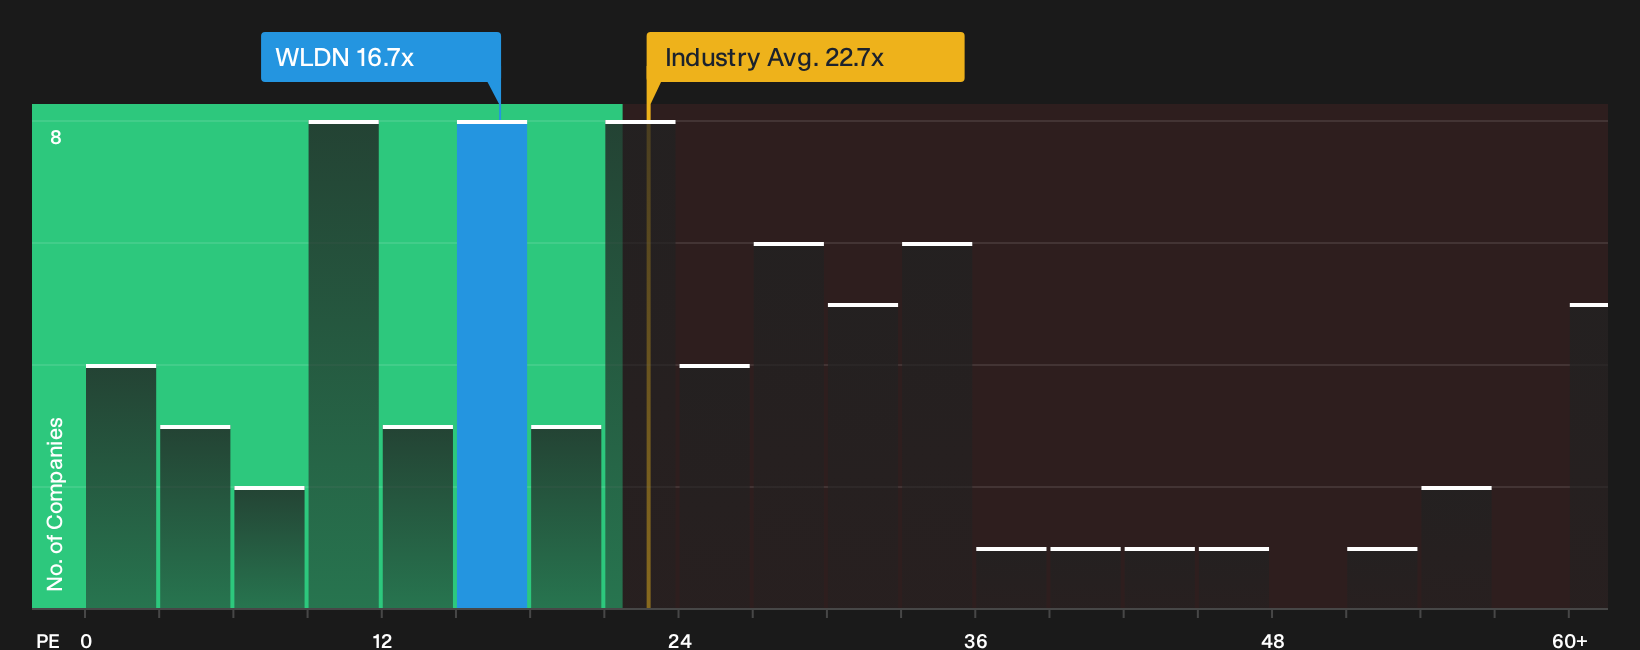
The P/E ratio is a clean way to see what you are paying today for each dollar of Willdan Group earnings. On this measure, the stock trades on about 16.7x, which is below both the Professional Services industry average of roughly 22.7x and a broader peer group near 27.4x.
The current multiple also sits close to the level implied by a tailored fair-value P/E, which factors in Willdan Group's sector, business mix and risk profile. Because the Mantis Innovation deal expands the energy efficiency platform and recent earnings guidance has sharpened expectations, this pricing suggests the market is asking you to pay roughly in line with what those fundamentals support rather than placing a clear premium or discount on the shares. Explore the numbers behind Willdan Group's P/E valuation.
The Willdan Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion on Willdan Group leaves off. They spell out the specific growth, margin and earnings paths that would need to play out for the stock to end up meaningfully above or below its current price. Rather than relying on a single multiple or model result, each narrative lays out the key assumptions behind its fair value so you can compare those expectations with actual numbers as quarterly results arrive on the Community page.
One of the top narratives on Willdan Group: 50% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Willdan Group's shift toward higher-margin commercial customers, with commercial activity expected to reach about 25% of the business in 2026 and a major contribution from data center electricity work..."
Discover why this Narrative puts Willdan Group at 50% undervalued.
One more thing about Willdan Group that could change how you see it
Everything here has focused on what Willdan Group looks like right now, but professional earnings projections a few years out give you another lens to compare with today’s valuation and assumptions. Explore where analysts expect Willdan Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com