


Veeva Systems (VEEV) is back in focus after UCB committed to its Vault CRM platform, highlighting how the software maker is using industry specific AI to support life sciences commercial teams.
These customer wins are landing at a time when Veeva Systems’ recent 90-day share price return of 20.63% and year to date share price gain of 38.85% point to building momentum, while the 3-year total shareholder return of 72.40% contrasts with a relatively modest 1-year total shareholder return of 2.63%, hinting at investors reassessing both growth potential and risk around its AI driven CRM strategy.
Scan beyond Veeva Systems and compare its momentum and AI driven CRM story with a curated set of 42 profitable AI stocks that aren't just burning cash.
After a near 21% climb in 90 days, Veeva Systems now trades only around 6% below both analyst targets and intrinsic estimates. Is that a cautious market underrating its AI push, or correctly pricing the risks?
Most Popular Narrative: 20.5% Undervalued
Against Veeva Systems’ last close of $304.77, the leading narrative fair value of $383.14 points to a material valuation gap. The author frames that difference through a detailed margin of safety lens built on cash flow work and risk adjustments.
My valuation framework estimates a fair enterprise value of roughly $320 per share, based on approximately $1.4 billion in projected free cash flow, 16% growth over years one through five, 12% growth over years six through ten, a 3.5% terminal-growth rate, a 9% discount rate, and roughly $4.5 billion of net cash. This is an investor estimate, not company guidance.
See why 53 investors see Veeva Systems as 20% undervalued.
Based on that fair value of $383.14 and the discount rate of about 8.0%, Veeva Systems is presented as a high quality life sciences software platform. The current share price is described as not yet reflecting the author’s assumptions on cash generation, durability of customer relationships, and measured AI monetisation through Falcon over time.
Result: Fair Value of $383.14 (UNDERVALUED)
Still, Veeva Systems faces real pressure if pharmaceutical mergers slow software decisions, or if Falcon adoption fails to translate into meaningful, repeatable commercial revenue.
Find out about the key risks to this Veeva Systems narrative.
Another View: What Veeva Systems’ P/E Is Telling You
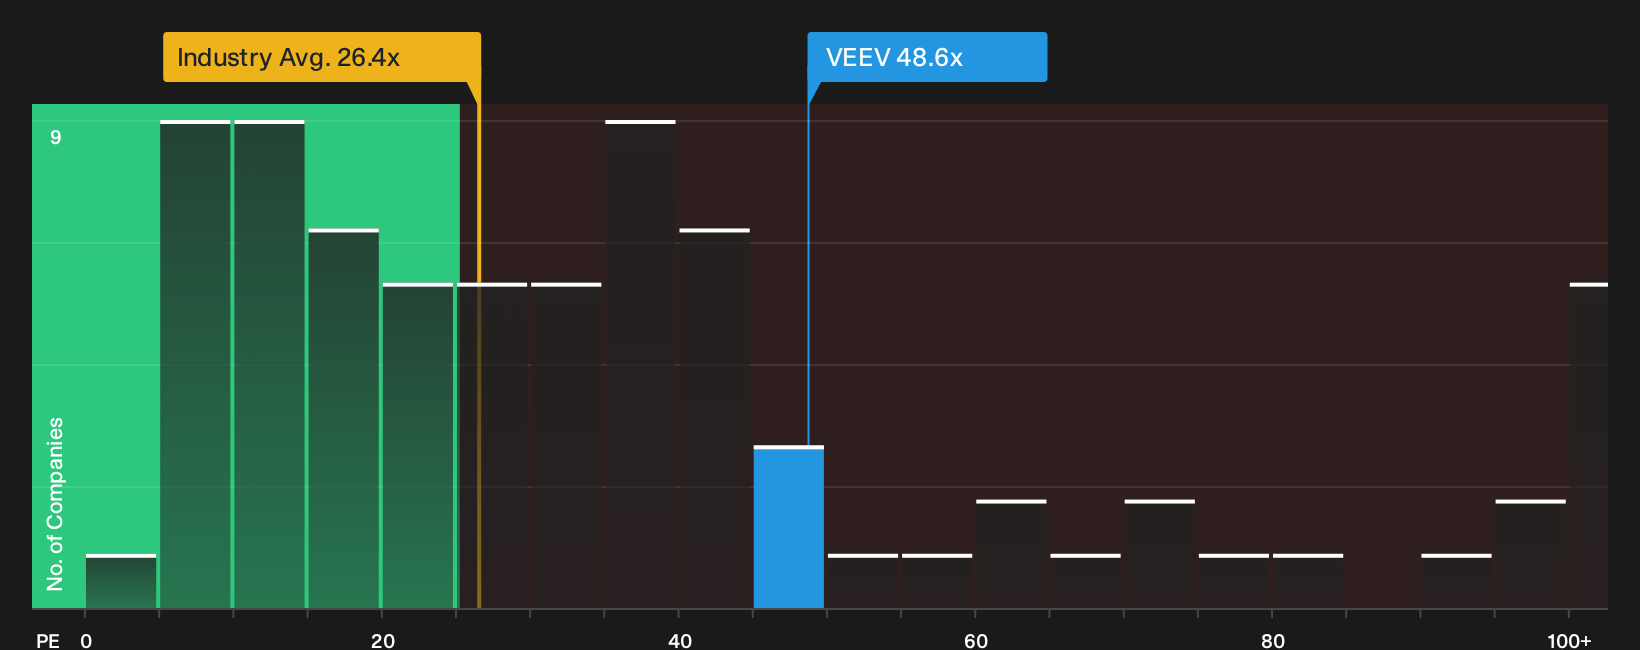
Veeva Systems screens as undervalued on cash flow work, yet the market is asking a premium on earnings. The stock trades on a P/E of 48.6x, compared with a 26.4x average for the global Healthcare Services group and a fair ratio of 34.1x that our model suggests the market could gravitate toward over time.
That gap means you are paying a higher upfront price for each dollar of earnings, even though Veeva looks cheaper than a 59.1x peer average. The key question is whether high quality past earnings and solid growth justify this richer multiple, or whether valuation risk eats into the upside that cash flow models point to.
To see how this earnings multiple stacks up against the detailed assumptions behind Veeva Systems’ cash flow valuation, take a closer look at our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty of optimism sits alongside real question marks in this Veeva Systems story, so move fast, review the full picture, and weigh both sides through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Veeva Systems?
If Veeva Systems has sharpened your focus on quality, do not stop here. Broaden your watchlist with a few targeted idea lists that can surface fresh opportunities before they are crowded.
- Target resilient balance sheets by scanning companies on our list of solid balance sheet and fundamentals (23 results) that pair steady finances with room for future decisions.
- Hunt for potential mispricings by reviewing our 32 high quality undervalued stocks and see which businesses combine quality fundamentals with compressed valuations.
- Stack income potential on top of capital appreciation by studying our 6 dividend fortresses and spot higher yielding options with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com