


Megaport (ASX:MP1) has put a clear marker down by shifting from pure network services to an integrated platform aimed at higher margin recurring products, a move that reshapes how investors might think about its earnings mix.
The recent shift in Megaport's product mix is landing against a strong backdrop, with the share price delivering a 52.11% year to date return and a 27.81% total shareholder return over one year. This comes even after a 12.76% decline in the 3 month share price that hints momentum has cooled short term, while the 84.60% total shareholder return over three years still points to a powerful longer run story.
Scan other high-growth, recurring revenue plays that echo Megaport's platform shift by reviewing the curated 14 high quality undiscovered gems.
Megaport now trades at a clear discount to both analyst targets and estimated fair value, yet the business is still loss making and mid transition. Is the market simply cautious, or correctly pricing that execution risk?
Most Popular Narrative: 33% Undervalued
On the analyst consensus Narrative on Simply Wall St, Megaport screens as undervalued, with a fair value of about A$27.89 against the last close at A$18.74. This puts the focus firmly on whether the AI and platform expansion thesis holds up.
Acceleration of AI infrastructure demand with Megaport signing about $1.3b of total contract value since April 2026 that is expected to convert into $435m of annual recurring revenue once deployed. This could support higher long-term revenue and operating leverage if the associated $826m of capex is efficiently absorbed.
See why 63 investors see Megaport as 33% undervalued.
Result: Fair Value of A$27.89 (UNDERVALUED)
Still, the Megaport story leans on heavy AI capex and new debt and equity funding, so weak utilisation or slower ARR conversion could quickly challenge this upbeat narrative.
Find out about the key risks to this Megaport narrative.
Another View On Megaport’s Valuation
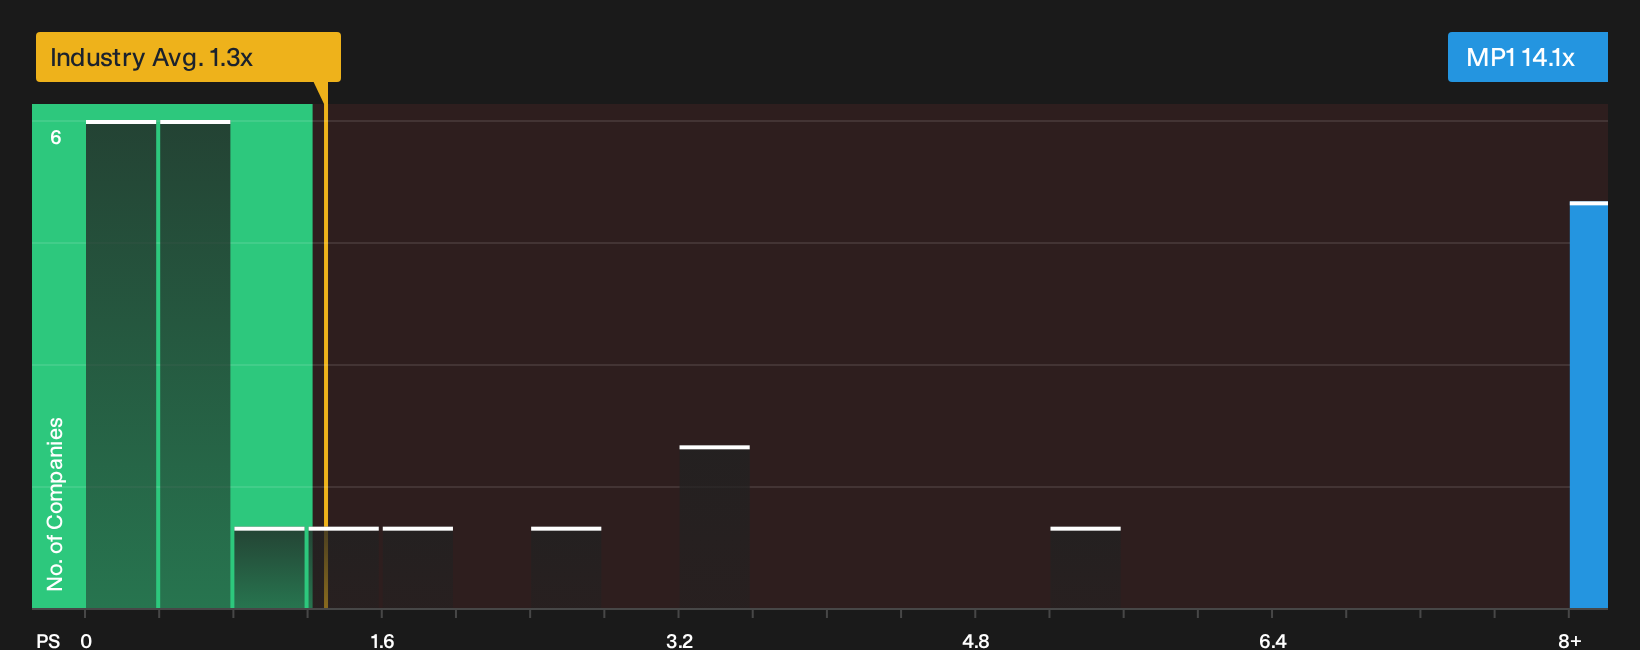
That upbeat fair value story meets a very different signal once you look at price based ratios. Megaport trades on a P/S of 14.1x compared with 1.3x for the global IT group and 12.9x for peers, even though the firm is still loss making. The fair ratio of 15.7x suggests the market already prices in a lot of future success, so how comfortable are you paying a premium today for profits that are still on the horizon?
For a closer look at how this pricing gap lines up with earnings potential, read the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals like these rarely stay unresolved for long. Consider moving quickly, review the underlying numbers yourself and stress test your thesis against both the 3 key rewards and 3 important warning signs.
Looking for more Megaport style investment ideas?
If you like the risk reward trade off around Megaport, do not stop here. Broaden your watchlist with focused screens that highlight different types of opportunity.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing valuations through the 2 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (12 results).
- Hunt for under followed potential by filtering for quieter opportunities that still show strong underlying metrics with the 14 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com