


Ducommun (DCO) just paired a return to profitability with tighter full year guidance, backing a revenue range of US$885 million to US$890 million for 2026 after its latest quarterly update.
Recent trading has turned choppy for Ducommun, with the share price slipping around 14% over the past month and roughly 27% over the last quarter, even after a year-to-date share price return close to 50% and a 1-year total shareholder return of about 51%. That pullback comes as the market digests the fresh earnings beat, refined 2026 revenue guidance and management’s push to use its US$650 million facility to pursue acquisitions. Taken together, these factors suggest that expectations and perceived risk around the stock are being reset rather than simply marching higher in a straight line.
Scan beyond Ducommun and see how other engineered-product players with similar momentum and acquisition capacity stack up using our curated 19 high quality undiscovered gems
Ducommun just flipped back to profit while the share price has cooled hard from its highs. Is this the moment to lean in, or does patience on a better entry make more sense once the valuation math is on the table?
Most Popular Narrative: 32% Undervalued
On the analyst consensus Narrative on Simply Wall St, Ducommun screens as undervalued, with a fair value of $212 against the latest close around $145, which puts a spotlight on whether the long term story justifies that gap.
Ongoing mix shift toward higher margin engineered products and aftermarket, with engineered products rising from 9% of revenue in 2017 to 23% over the past 12 months and management aiming for roughly 25% by 2027 and 40% with 20% aftermarket by 2032, supports the view that Ducommun can continue to lift gross margin and adjusted EBITDA margin from the current 17.1% level.
See why 14 investors see Ducommun as 32% undervalued.
Result: Fair Value of $212 (UNDERVALUED)
Still, the narrative around Ducommun can change quickly if internal control issues resurface or if the reported backlog decline limits the degree to which margins can recover.
Find out about the key risks to this Ducommun narrative.
Another View: What Ducommun’s P/E Is Telling You
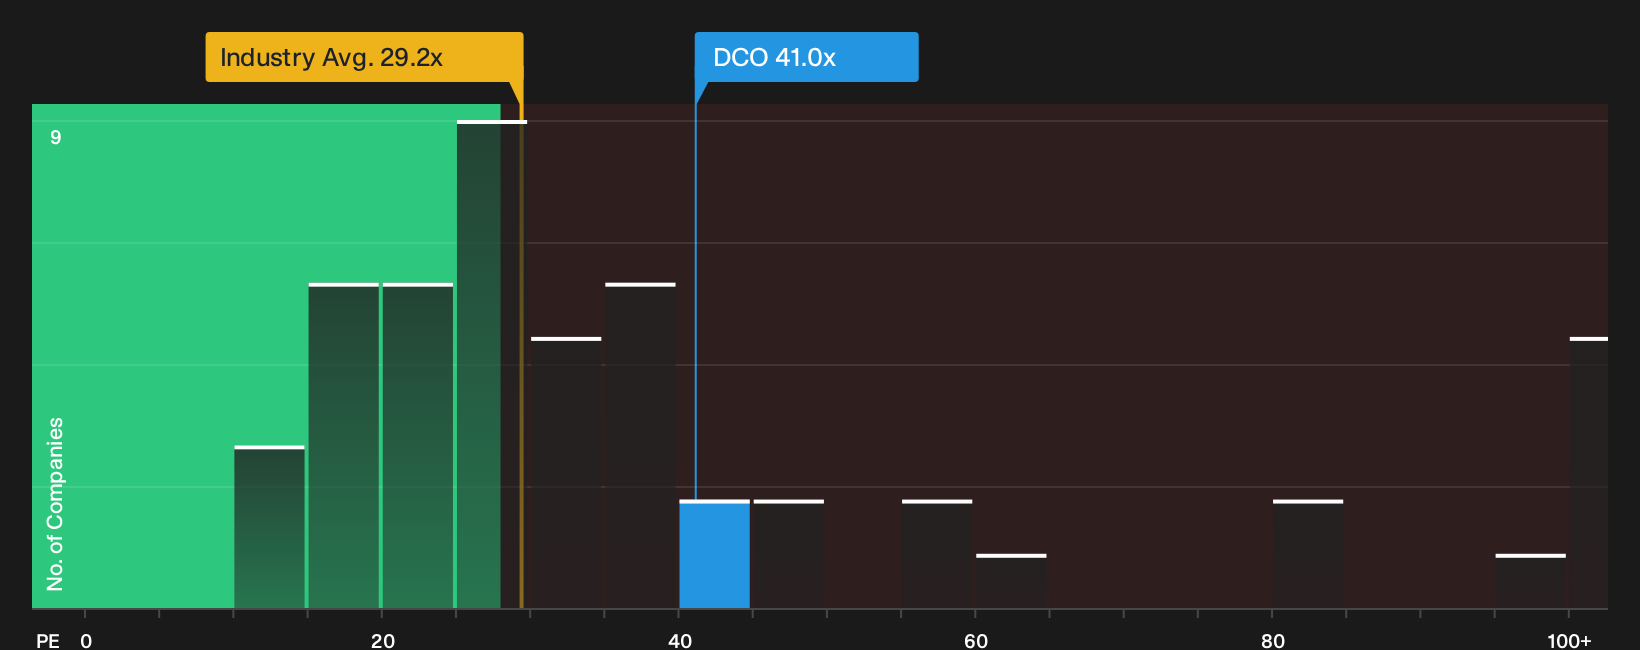
Ducommun may screen as undervalued on a fair value of $212, yet the current P/E of 41x tells a very different story. The stock trades well above the US Aerospace & Defense average of 29.2x and the 27.6x fair ratio, which points to richer expectations and less margin for error. If the market drifts back toward that lower fair ratio, what does that mean for your upside and downside?
For a closer look at how this valuation gap compares with peers and how the fair ratio might influence the share price over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Ducommun is split, and that is exactly when fresh data matters most. Move quickly, review the full fundamentals, and see why some investors are focusing on its 4 key rewards
Looking for more Ducommun-sized investment ideas?
Do not stop with Ducommun. Cast the net wider using targeted screeners so you spot quality opportunities early instead of hearing about them after the move.
- Zero in on potential mispricings by comparing quality, balance sheets, and valuations through a focused set of 32 high quality undervalued stocks.
- Lock in potential income ideas by filtering for resilient payers inside a curated pool of 6 dividend fortresses.
- Dial down portfolio stress by concentrating on companies that pass strict balance sheet checks using a practical list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com