


International Bancshares (IBOC) has drawn attention after reporting third quarter and nine month 2026 results, with net interest income and net income both above the figures recorded a year earlier.
The share price of International Bancshares trades at $68.02, with a modest 1.8% year to date share price gain, a stronger 6.5% total shareholder return over the past year, and more substantial 3 year and 5 year total returns. This points to momentum built up over a longer horizon rather than in recent months.
Scan how International Bancshares compares with other profitable regional lenders by reviewing a curated list of bank stocks with disciplined balance sheets in our list of solid balance sheet and fundamentals (23 results)
International Bancshares now trades at a sizeable discount to both analyst targets and one intrinsic value estimate, despite a steady share price climb over several years. Is that market caution sensible or mispriced before looking at valuation?
Preferred P/E of 10.1x: Is it justified?
International Bancshares changes hands at $68.02 with a P/E of 10.1x, which sits below both peer and broader US Banks averages. This means the market is assigning a lower price tag to each dollar of current earnings than it does for many competitors.
The P/E ratio tells you how much investors are paying for $1 of earnings. For a regional lender like International Bancshares it becomes a shorthand for expectations on profitability and risk. A 10.1x multiple suggests the market is not paying a premium for the business, despite high quality earnings and a track record of profit growth over the past 5 years.
IBOC trades on 10.1x earnings while the US Banks industry is on 11.3x and the peer set averages 12.9x. This is a clear gap that points to the stock being priced more cautiously than many rivals. If that discount closed even part of the way toward peer levels, the valuation could look very different to today.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 10.1x (UNDERVALUED)
Still, the recent 7.3% share price pullback over 90 days, along with any shift in regional credit quality, could quickly challenge the current discount thesis on International Bancshares.
Find out about the key risks to this International Bancshares narrative.
Another view on International Bancshares valuation
The earnings multiple paints International Bancshares as modestly priced, yet the SWS DCF model is far more aggressive. Under that framework, the shares trade around 50.9% below an estimated future cash flow value of $138.48. That leads to a simple question for investors: which lens feels more realistic for a regional lender with current data gaps on future growth?
Look into how the SWS DCF model arrives at its fair value.
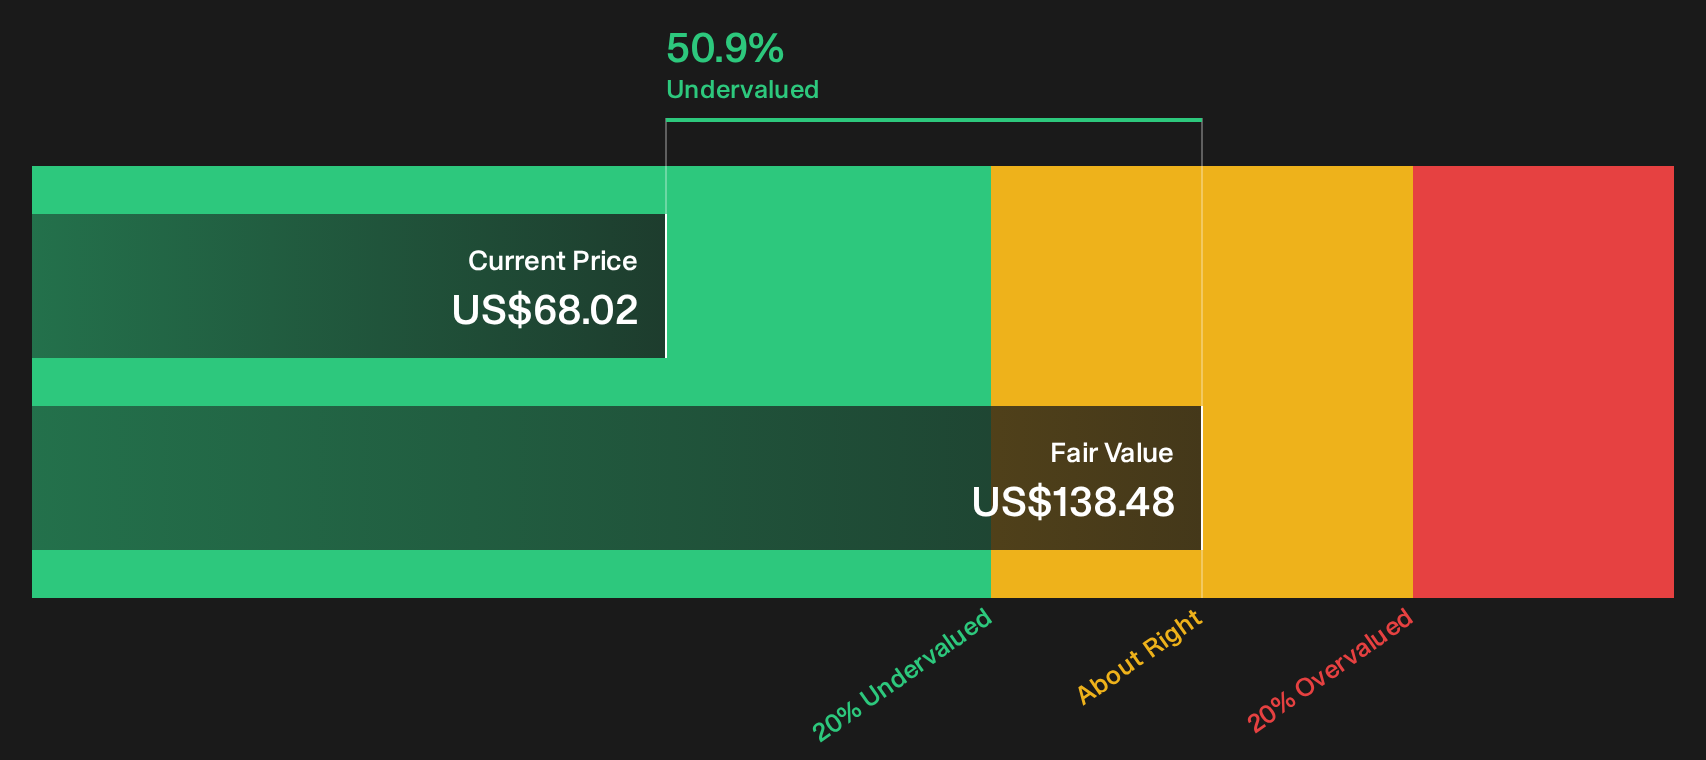
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out International Bancshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around International Bancshares valuation and market sentiment make this a good moment to check the underlying data yourself and act quickly before opinions settle. To weigh both the concerns and the potential upside, review the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond International Bancshares?
If you want to stress test your thinking and avoid getting anchored on a single regional lender, line up fresh ideas with the Simply Wall Street Screener.
- Target resilience by scanning for businesses with sturdier balance sheets and consistent fundamentals using the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced potential by reviewing the 19 high quality undiscovered gems that combine solid metrics with relatively low market attention.
- Prioritize stability and capital protection by filtering for 30 resilient stocks with low risk scores that may better match a cautious approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com