


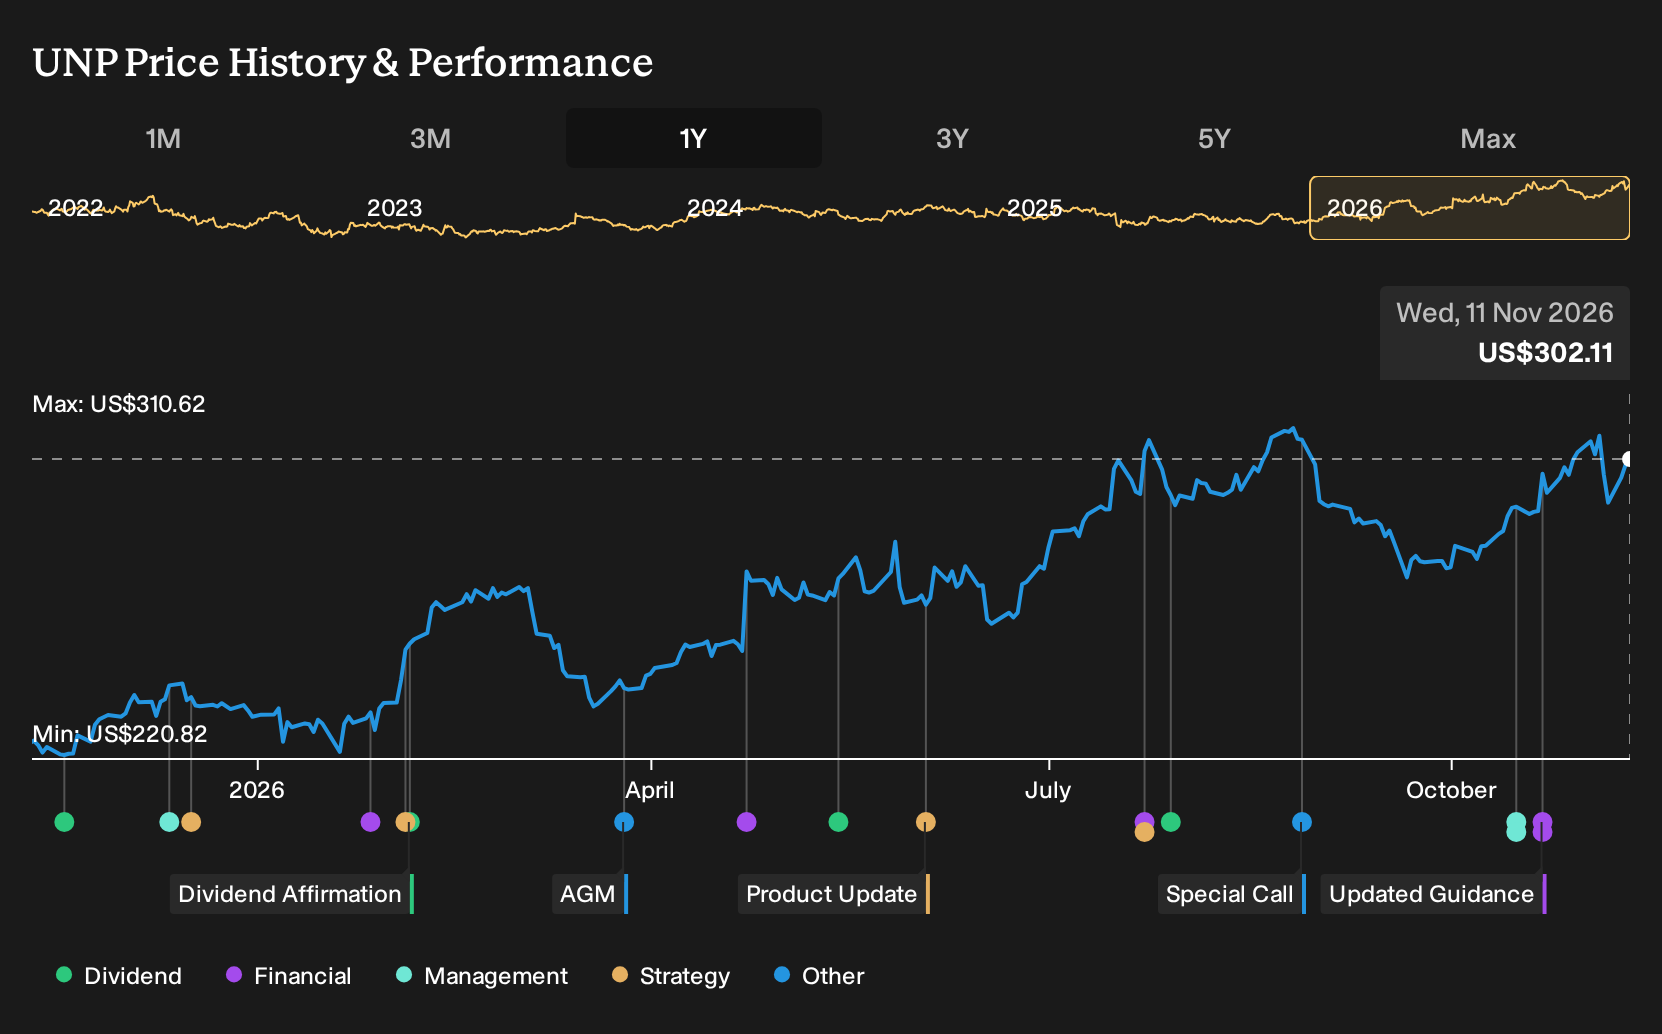
- Union Pacific recently moved above its 20 day moving average and has seen multiple upward earnings estimate revisions over the past two months, supported by ongoing efficiency projects, intermodal investments and shareholder return programs.
- The unusual combination of stronger earnings expectations, no downward revisions and continued capital returns suggests analysts see Union Pacific’s current cost, fuel and wage pressures as manageable within its long term operating plan.
- We will now look at how Union Pacific’s upgraded earnings estimates might reshape the longer term investment narrative already in place.
Scan how Union Pacific’s momentum and earnings revisions compare with a hand picked set of rails and industrials in the list of solid balance sheet and fundamentals (23 results).
Union Pacific Investment Narrative Recap
Owning Union Pacific means believing the freight network can keep earning solid returns while fuel, wage and regulatory pressures are kept in check. The analyst consensus Narrative on Simply Wall St leans heavily on efficiency projects, intermodal growth and the Norfolk Southern merger plan. The recent move above the 20 day average and higher earnings estimates point to near term operating momentum, but do not fundamentally change that long term thesis.
The most important short term swing factor is still how Union Pacific handles higher diesel and roughly 6% wage inflation alongside its efficiency and pricing efforts. Fuel and labour costs remain the clearest near term margin risk. The updated earnings outlook suggests these pressures are currently viewed as manageable rather than thesis breaking.
The most relevant recent development is the cluster of upward earnings revisions with no cuts, tied to Union Pacific’s ongoing efficiency work and intermodal focus. That matters for you because the core catalysts in the analyst consensus Narrative on Simply Wall St, such as energy management systems and optimization tools, only pay off if they show up in profit expectations.
This revision trend also connects to the bigger projects already in motion. Investments in the Houston complex, the Sunset Route and domestic intermodal, plus the proposed Norfolk Southern merger with targeted revenue and cost synergies, all depend on disciplined execution while fuel and wage costs stay under control. The market reaction around the 20 day moving average reflects how investors are weighing those execution risks against the potential upside of that plan.
Union Pacific's current analyst narrative points to forecast revenue of US$29.9b and expected earnings of US$9.4b by 2029, which implies annual top line growth of 5.5% and an earnings increase of about US$2.1b from US$7.3b today.
Uncover why Union Pacific's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Union Pacific attracts only two fair value estimates from the Simply Wall St Community, yet they already stretch from about US$266 to just under US$330. That spread shows how far private investors can disagree. When you set those opinions against rising diesel and wage costs or potential Norfolk Southern merger synergies, you can arrive at very different long term outcomes. Explore those contrasting Community views before deciding how Union Pacific fits your own expectations.
Explore another Union Pacific fair value estimate, including one that suggests as much as 9% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Union Pacific research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Union Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Union Pacific's overall financial health at a glance.
Looking for more Union Pacific investment ideas?
Once you have a view on Union Pacific, it helps to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you scan for shares that match the kind of portfolio you are trying to build, rather than forcing your goals to fit a single stock.
- If you want potential growth at lower price points, review the 12 elite penny stocks with strong financials that pair smaller market values with stronger balance sheets and fundamentals than many investors expect.
- For those hunting for quality at a sensible entry point, start with a 32 high quality undervalued stocks that blends cash flow strength with cleaner finances.
- Income focused investors who still care about resilience can screen for 6 dividend fortresses that aim to combine higher yields with sturdier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com