


Once a darling of the artificial intelligence (AI) boom, CoreWeave (CRWV) is finding it increasingly difficult to keep investors on board as Wall Street grows more skeptical of the AI trade. Rising concerns about the enormous costs of building AI infrastructure have rattled both equity and bond markets, putting debt-laden neocloud providers like CoreWeave under the microscope. Investors are increasingly questioning whether the company can sustain its aggressive expansion plans without exposing itself to excessive financial risk.
However, CoreWeave has managed to deliver a fresh catalyst for optimism. On Monday, the company announced a multi-year agreement with Wayve to supply the cloud computing capacity needed to train and evaluate its autonomous driving models. Headquartered in the U.K., Wayve develops autonomous driving technology for several major automakers, including Mercedes-Benz (MBGYY), Nissan (NSANY), and Stellantis (STLA). The company also maintains a strategic partnership with Uber.
Under the agreement, Wayve will train its foundation models on CoreWeave Cloud, powered by Nvidia's (NVDA) Blackwell GPUs. Wayve, which already leveraged Weights & Biases, was acquired by CoreWeave last year and is now expanding its operations onto CoreWeave Cloud. Wayve's SVP of Engineering, Silvius Rus, highlighted how the partnership would support its AI Driver development process, which relies on continuously collecting real-world driving data, training, and evaluating models, and deploying improved versions.
He noted that access to CoreWeave's AI infrastructure, specifically designed for demanding workloads, would help accelerate the technology's commercial rollout. Echoing that optimism, CoreWeave's managing director of EMEA, Gavin Jackson, described the agreement as a significant milestone, bringing one of the world's most demanding physical AI initiatives onto infrastructure purpose-built to support it. Investors responded positively to the announcement, with CoreWeave shares surging nearly 5.6% on Monday. So given this latest development, let's take a closer look at CoreWeave stock.
About CoreWeave Stock
Established in 2017, CoreWeave has carved out a niche in the cloud computing market by building infrastructure specifically designed for the intensive demands of artificial intelligence. Its platform brings together high-performance computing (HPC) infrastructure, specialized software, and technical expertise, enabling AI developers to build, train, and scale increasingly sophisticated models. Its clientele spans prominent AI research labs, emerging startups, and large global enterprises seeking the computing muscle to power their next-generation applications.
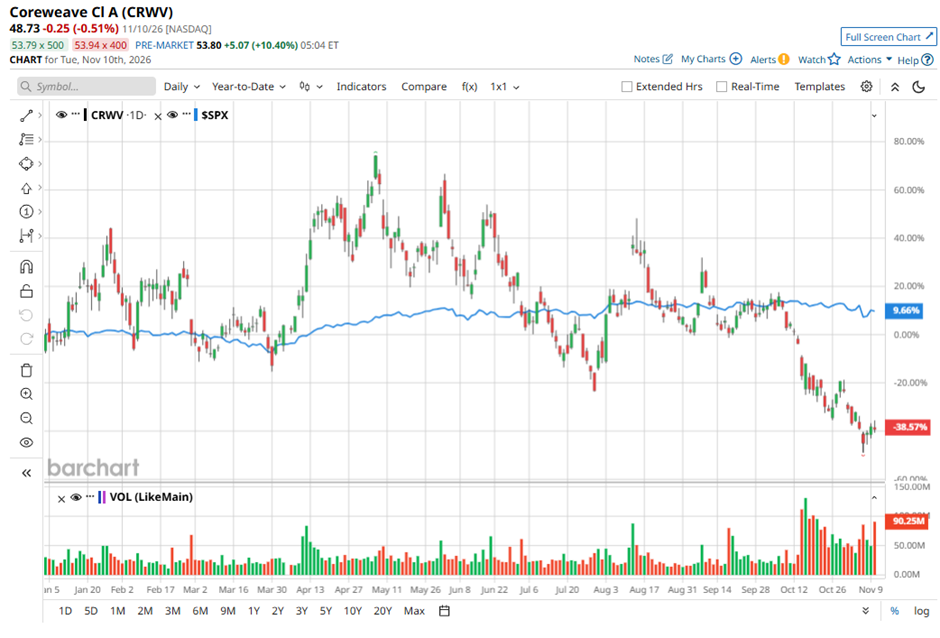
CoreWeave made its Nasdaq debut in March 2025, riding the wave of surging demand for AI-focused cloud infrastructure. However, its journey as a public company has been anything but smooth. Currently valued at approximately $26.88 billion, the company is facing growing investor anxiety over its aggressive, debt-funded infrastructure expansion, compounded by a selloff in its bonds. The resulting pressure has sent CRWV shares tumbling 54% over the past year, including a steep 32% decline in 2026 alone.
The extent of the damage becomes even clearer when compared with the broader market. Over the same period, the S&P 500 Index ($SPX) has advanced 10.1%, with gains of 9.9% so far in 2026. CoreWeave's underperformance is particularly striking given the enthusiasm that once surrounded AI infrastructure stocks. After scaling to a 52-week high of $138.25 in May, CRWV has surrendered approximately 64.8% of its value from that peak.
CoreWeave’s Q3 Earnings Snapshot
While CoreWeave shares have taken a beating on Wall Street, the company's latest financial results tell a much stronger story. The company’s fiscal 2026 third-quarter earnings report, published on Nov. 10, showed that demand for AI computing capacity continues to fuel impressive business growth, with quarterly revenue topping analyst expectations and management lifting its full-year outlook.
Revenue jumped a massive 168% year-over-year to $3.66 billion, comfortably ahead of Wall Street's estimate of approximately $3.54 billion. Co-founder and CEO Michael Intrator called it a “breakout quarter,” pointing to more than $1 billion in sequential revenue growth and growing customer adoption of the company's advanced GPU cloud solutions. CoreWeave also delivered solid growth in adjusted profitability.
Adjusted EBITDA climbed to $2.26 billion, with a margin of 62%, compared with $838 million and a 61% margin in the same quarter last year. However, the company's GAAP performance painted a different picture. Its net loss widened to $709 million, or $1.27 per share, from $110 million, or $0.22 per share, a year earlier. The larger loss was largely driven by heavy spending on data center expansion, depreciation costs, and net interest expenses, which amounted to $846 million.
Despite the substantial funding requirements of its expansion plans, management believes CoreWeave has several sources of capital to support its growth. These include financing backed by customer contracts, operating cash flow, and approximately $9 billion in customer prepayments and deposits expected over the next three months alone.
Management said this financial flexibility would help the company continue building and delivering the infrastructure and software customers need to develop, run, and scale AI applications. Meanwhile, its revenue backlog stood at approximately $132.5 billion as of Sept. 30, providing significant visibility into future demand. Reflecting this strong momentum, CoreWeave raised its full-year 2026 financial guidance.
The company now expects revenue of $13 billion to $13.3 billion and has also increased its adjusted operating income projections. However, meeting that demand will require substantial investment. CoreWeave expects capital expenditures to reach between $37 billion and $39 billion this year as it ramps up the deployment of high-density server clusters, including NVIDIA GB300 NVL72 racks, to keep pace with growing enterprise demand for AI computing power.
How Do Analysts View CoreWeave Stock?
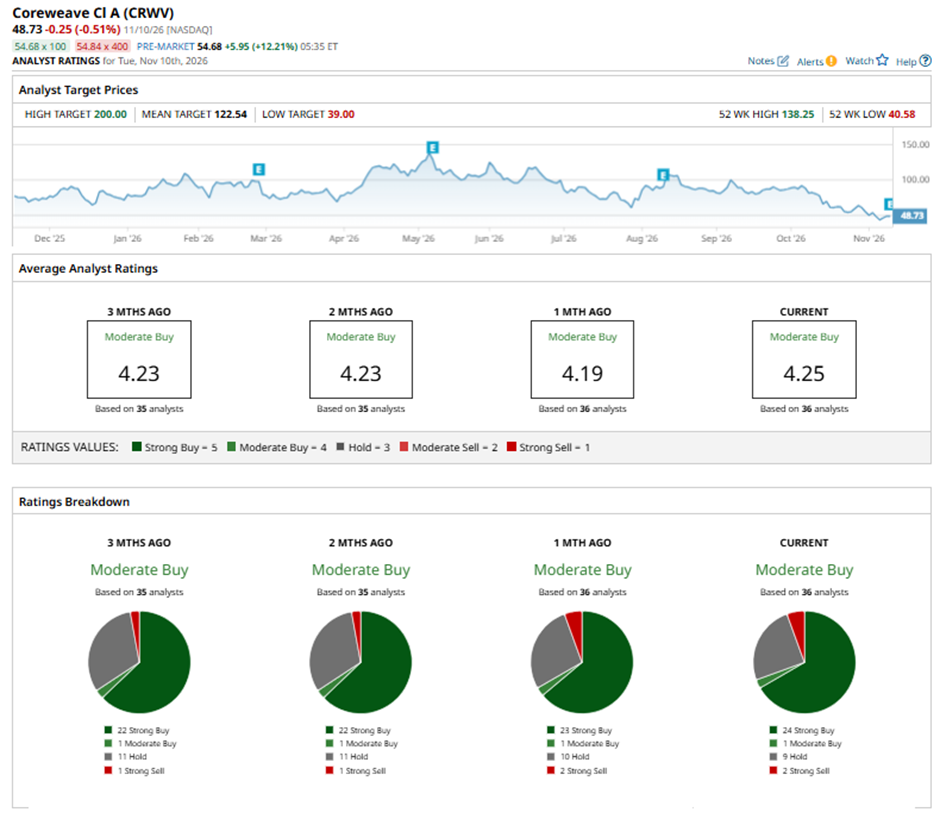
Despite the stock's steep decline, Wall Street hasn't given up on CoreWeave. Analysts maintain a consensus “Moderate Buy” rating, reflecting considerable optimism about its recovery potential. Of the 36 analysts covering the stock, 24 rate it a “Strong Buy,” one recommends a “Moderate Buy,” nine have a “Hold” rating, and two advise a “Strong Sell.” The average price target of $122.54 points to a potential upside of approximately 151.5%, while the Street-high target of $200 suggests an impressive 310.4% rally from current levels.
On the date of publication, Anushka Mukherji did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.