


CRA International (CRAI) just paired a third quarter earnings update with a higher cash payout, reporting increased sales and net income alongside a 17.5% bump in its quarterly dividend.
Investors have reacted positively to the latest update, with CRA International’s share price delivering an 11.8% gain over the past month and an 18.9% rise over 90 days. The 1 year total shareholder return of 11.8% sits on top of a 3 year total shareholder return of roughly 121%, suggesting momentum has been building over time despite some shorter term volatility.
Scan how CRA International’s latest earnings and dividend move compares with other consultancies and service providers using our hand picked list of solid balance sheet and fundamentals (23 results) as a starting universe.
CRA International now trades about 20% below analyst targets and at a deeper implied discount to some fair value estimates after this latest jump. Is that a market safety margin, or a sign of lingering caution that investors should heed as they weigh valuation next?
Most Popular Narrative: 20% Undervalued
Against CRA International’s last close of $200.14, the analyst consensus Narrative on Simply Wall St anchors its fair value at $250.50, which implies a meaningful valuation gap based on detailed revenue and earnings forecasts built into that work.
CRA International is investing heavily in expert recruitment and retention, with tens of millions of dollars in forgivable loans and retention awards, and around 30 new vice presidents ramping ahead of expectations. This can support future utilization, revenue growth and EBITDA dollars once these hires fully mature.
See why 7 investors see CRA International as 20% undervalued.
Result: Fair Value of $250.50 (UNDERVALUED)
Still, the story can change quickly if CRA International case flow slows with weaker M&A, or if heavy senior hiring fails to translate into strong utilization.
Find out about the key risks to this CRA International narrative.
Another View: CRA International Through The P/E Lens
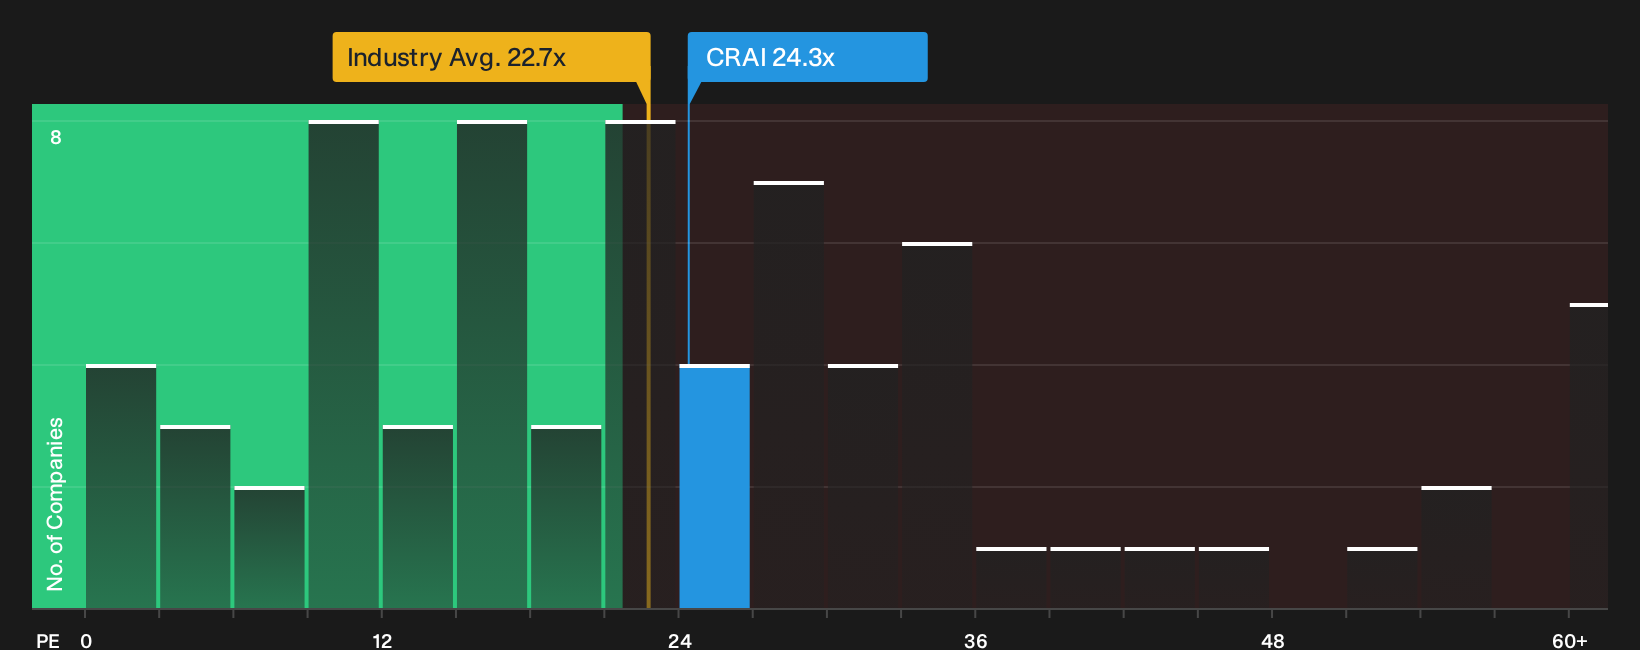
That DCF based fair value of $324.80 paints CRA International as undervalued, yet the simple P/E check tells a cooler story. CRAI trades on 24.3x earnings compared with 22.7x for the US Professional Services group and a fair ratio of 16.2x that our model suggests the market could move toward. That richer multiple can either be a premium you think is justified or a reminder that downside risk is not only an abstract concept.
Before leaning too heavily on any single approach, it is worth considering how the earnings multiple, peer comparison and fair ratio line up in the detailed work behind our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So does this mostly upbeat read on CRA International match your own take, or does it feel too generous given the mix of risks and rewards that have surfaced? To pressure test the bullish narrative against the bears and see both sides laid out clearly, review the 2 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond CRA International?
If CRA International has sharpened your thinking, do not stop here. Use focused screeners to uncover other opportunities that fit your risk style and goals.
- Target undervalued quality by scanning a curated pool of companies with strong fundamentals using the 32 high quality undervalued stocks.
- Prioritise resilience and seek out businesses with sturdier finances through the 30 resilient stocks with low risk scores.
- Hunt for lesser known potential by reviewing a tightly filtered 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com