


StubHub Holdings has seen its share price fall sharply over the past year, which puts fresh attention on what investors are paying for its sales today. With mixed recent returns and active corporate changes, the question now is how well the current market value lines up with the revenue base behind the ticketing platform.
- The stock has fallen 70.7% over the past year, so anyone looking at StubHub Holdings now is effectively reassessing what the market thinks its sales are worth.
- Recent reports of higher adjusted profitability and lower debt can support a view that more of each dollar of sales may turn into cash that is available to equity holders.
- The analysts covering StubHub Holdings have run their own numbers. See what analysts think StubHub Holdings's shares could be worth.
The issue now is whether StubHub Holdings' current share price is justified by its sales when set against the Fair Ratio benchmark.
To put StubHub Holdings' recent share price reset in context and see how other businesses are being valued on similar principles, it can help to compare it with 32 high quality undervalued stocks.
Is StubHub Holdings Still Cheap on Sales?
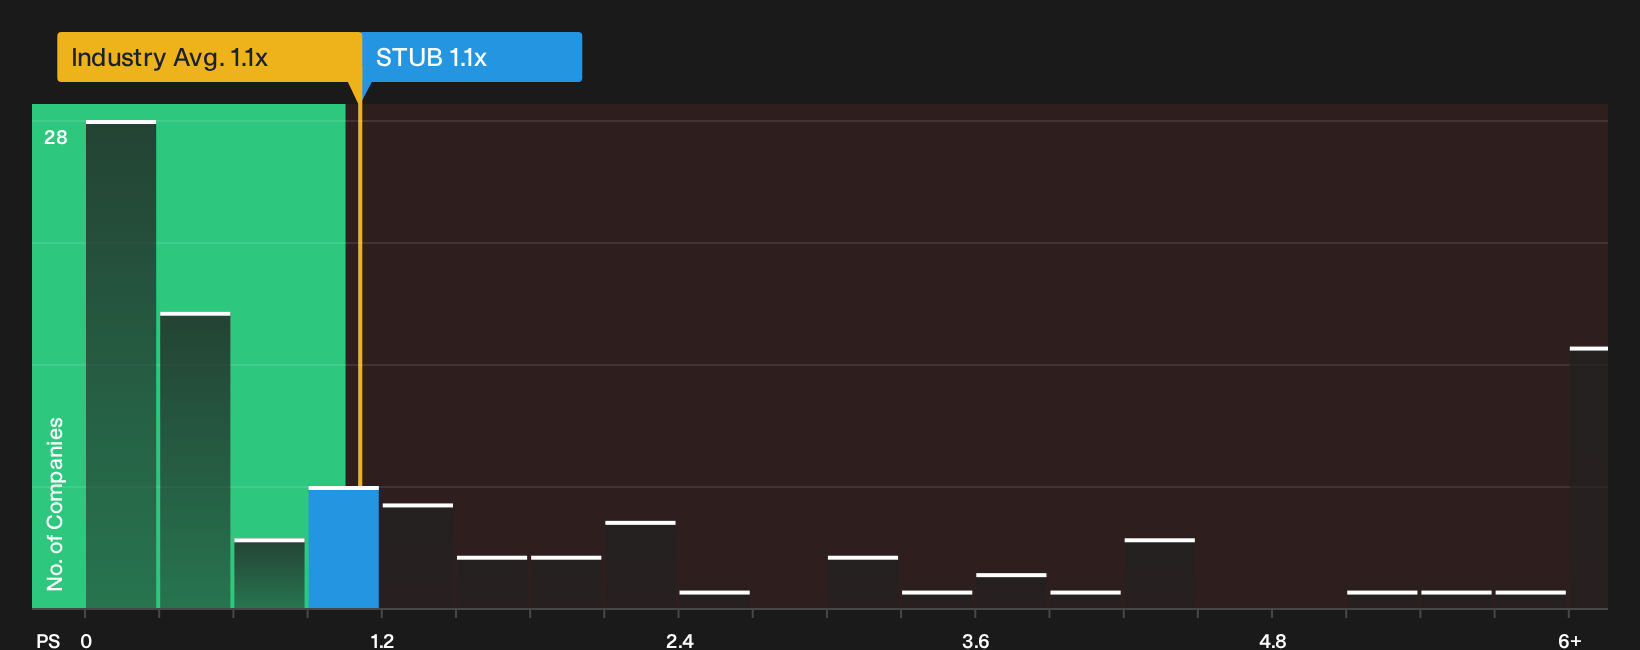
P/S is a useful lens for StubHub Holdings because the business is closely tied to ticket sales volume and revenue throughput. On this measure, the stock trades at about 1.1x P/S, which is very similar to the wider Entertainment industry average of roughly 1.1x. Against a group of peers on around 3.5x, the current tag implies investors are paying a much lower price for each dollar of StubHub Holdings' sales than for comparable platforms.
Because the Fair Ratio model suggests a higher P/S would be typical given StubHub Holdings' profile, the present 1.1x level screens as undervalued on this framework. Recent reports of stronger adjusted EBITDA margins and lower debt mean the market is assigning this discount despite some improvement in how revenue converts into cash and balance sheet strength. For anyone comparing alternatives in ticketing and online experiences, the key question is whether that gap to the Fair Ratio reflects lingering worries about future execution or an opportunity where expectations have been reset aggressively. Explore the numbers behind StubHub Holdings's P/S valuation.
The StubHub Holdings Narrative: What Would Justify Today's Price?
Narratives on StubHub Holdings' Community page pick up where the P/S puzzle leaves off by spelling out which paths for revenue, margins and earnings would need to play out for the equity to be worth materially more or less than the current price. Each scenario turns fair value into a concrete, testable idea about StubHub Holdings' business, so you can track how the underlying case holds up as new information arrives.
One of the top narratives on StubHub Holdings: 20% undervalued
This comes from the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"While the company is pursuing open distribution with rights holders, ongoing investigations into alleged ghost ticketing at the World Cup raise the risk that partners and regulators demand tighter controls..."
Discover why this Narrative puts StubHub Holdings at 20% undervalued.
One more StubHub Holdings check that sits outside the P/S story
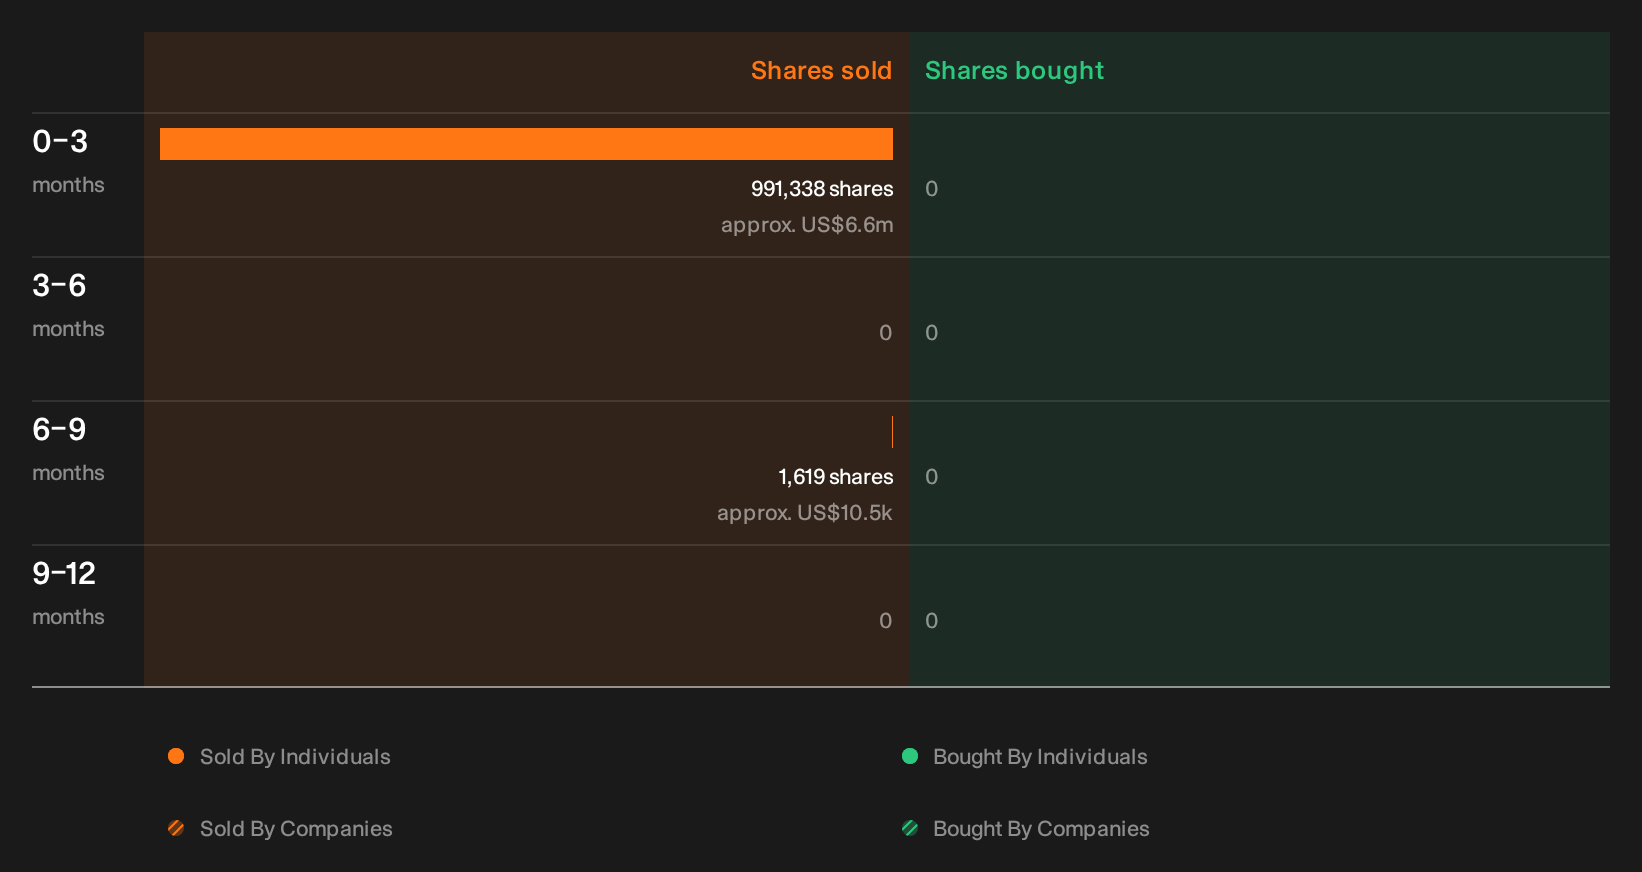
Price tags and revenue multiples only tell part of the picture for StubHub Holdings, because recent trades by people inside the business can add another layer that readers may want to unpack. See the recent insider selling flagged for StubHub Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com