


Modine Manufacturing (MOD) has started commercial production of Airedale chillers at a new 682,000 square foot facility in Grand Prairie, Texas, expanding its US data center cooling footprint.
For investors watching Modine Manufacturing, the story in the share chart has been choppy. The stock has rebounded with a 1-day share price return of 3.49% and a 7-day gain of 8.23%, yet momentum over the past few months has faded, with the 30-day share price return down 38.16% and the 90-day move down 47.58%. Over a longer stretch, the picture is different, with the 3-year total shareholder return at 134.25% and the 5-year figure very large at roughly 9x. This gives useful context for the recent 1-year total shareholder return decline of 21.4% as the market reassesses earnings guidance, margin trends, and execution risk around new projects like the Grand Prairie data center facility.
Compare Modine Manufacturing's data center cooling push with a curated set of infrastructure players by scanning the 42 power grid technology and infrastructure stocks that is shaping the next leg of digital capacity build-out.
Modine Manufacturing now trades at a wide discount to both analyst targets and some intrinsic value estimates after a sharp pullback. Is that gap mispricing execution risk, or is it fairly pricing a tougher road ahead?
Most Popular Narrative: 63% Undervalued
On the Simply Wall St analyst consensus Narrative, Modine Manufacturing is framed as worth $290.78 a share, compared with a last close of $106.67. That view leans on detailed revenue and earnings forecasts compiled from analyst models, not a single opinion.
The main thing that has to go right is execution on the climate solutions pivot, including the Performance Technologies spin-off and the ramp of new data center and Commercial HVAC capacity, while supply chain and integration issues are brought under tighter control.
The numbers imply that Modine Manufacturing’s share price reflects a business still priced below what current data center growth, margin targets, and the move toward a pure-play climate solutions profile would suggest for a more fully valued stock.
See why 58 investors see Modine Manufacturing as 63% undervalued.
Result: Fair Value of $290.78 (UNDERVALUED)
Still, two pressure points could reverse that undervalued narrative for Modine Manufacturing: extended supply chain friction and lower margin data center or HVAC contract terms.
Find out about the key risks to this Modine Manufacturing narrative.
Another View: What Modine Manufacturing’s P/E Is Telling You
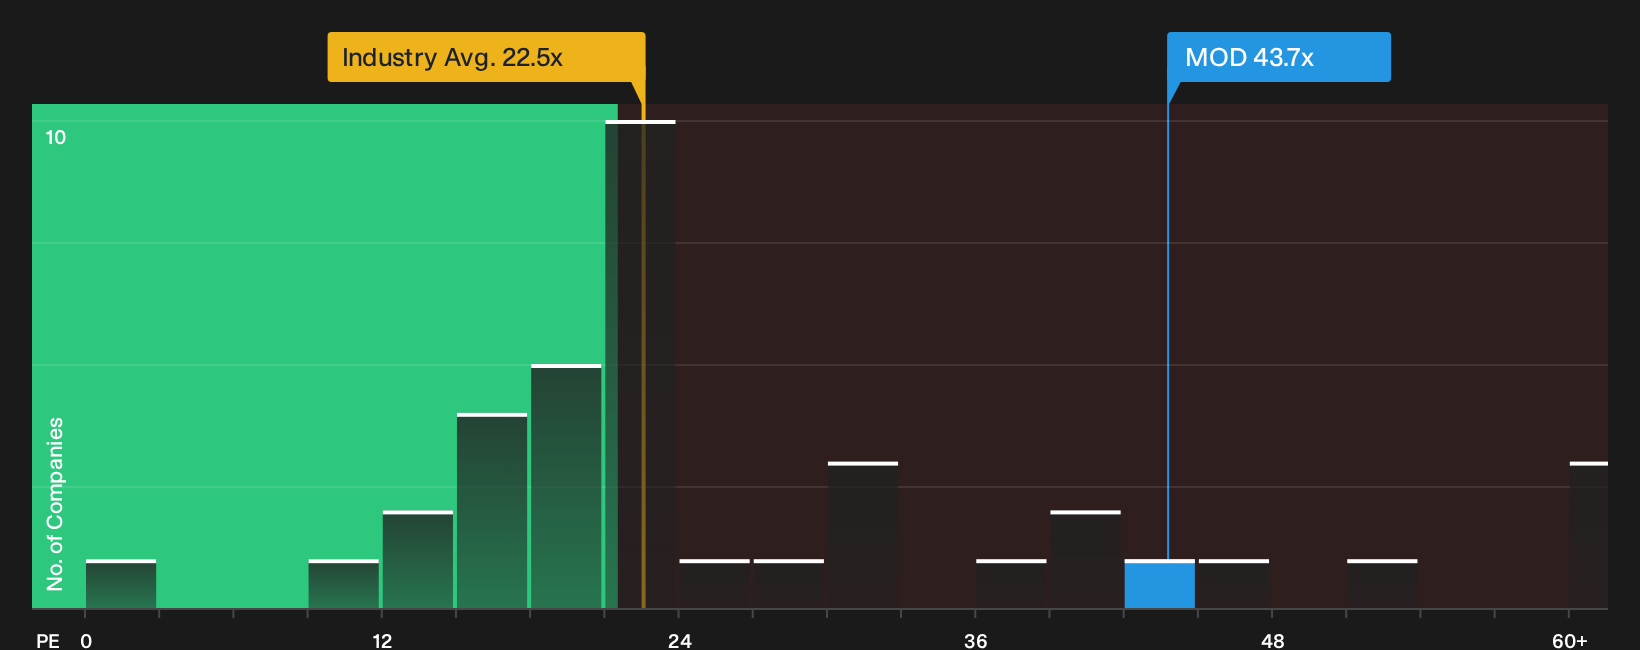
The analyst narrative presents Modine Manufacturing as deeply undervalued on future cash flows, yet the share price does not look cheap on current earnings. The stock trades on a P/E of 43.7x, compared with 22.5x for the wider US Building industry and 30.1x for close peers.
Against the estimated fair ratio of 69.6x, that premium appears more measured and not outright excessive. The gap between today’s multiple, the industry, and the fair ratio highlights valuation risk if earnings delivery stumbles. It also leaves room for potential upside if the climate and data center plan performs in line with current expectations. Which side of that trade-off do you trust more: the rich current multiple, or the long range growth story incorporated into fair value models?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in the Modine Manufacturing story so far. Use the data, weigh both sides, then pressure test your own thesis against the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Modine Manufacturing?
If Modine Manufacturing has sharpened your thinking, do not stop there. Broaden your watchlist with other focused ideas built from the same consistent framework.
- Target potential mispricing by scanning a curated set of companies that look undervalued on quality and fundamentals through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing a handpicked group of stocks with higher yields and resilient payout profiles via the 6 dividend fortresses.
- Dial down portfolio risk by checking a focused 30 resilient stocks with low risk scores that highlights businesses with sturdy balance sheets and steady financial scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com