


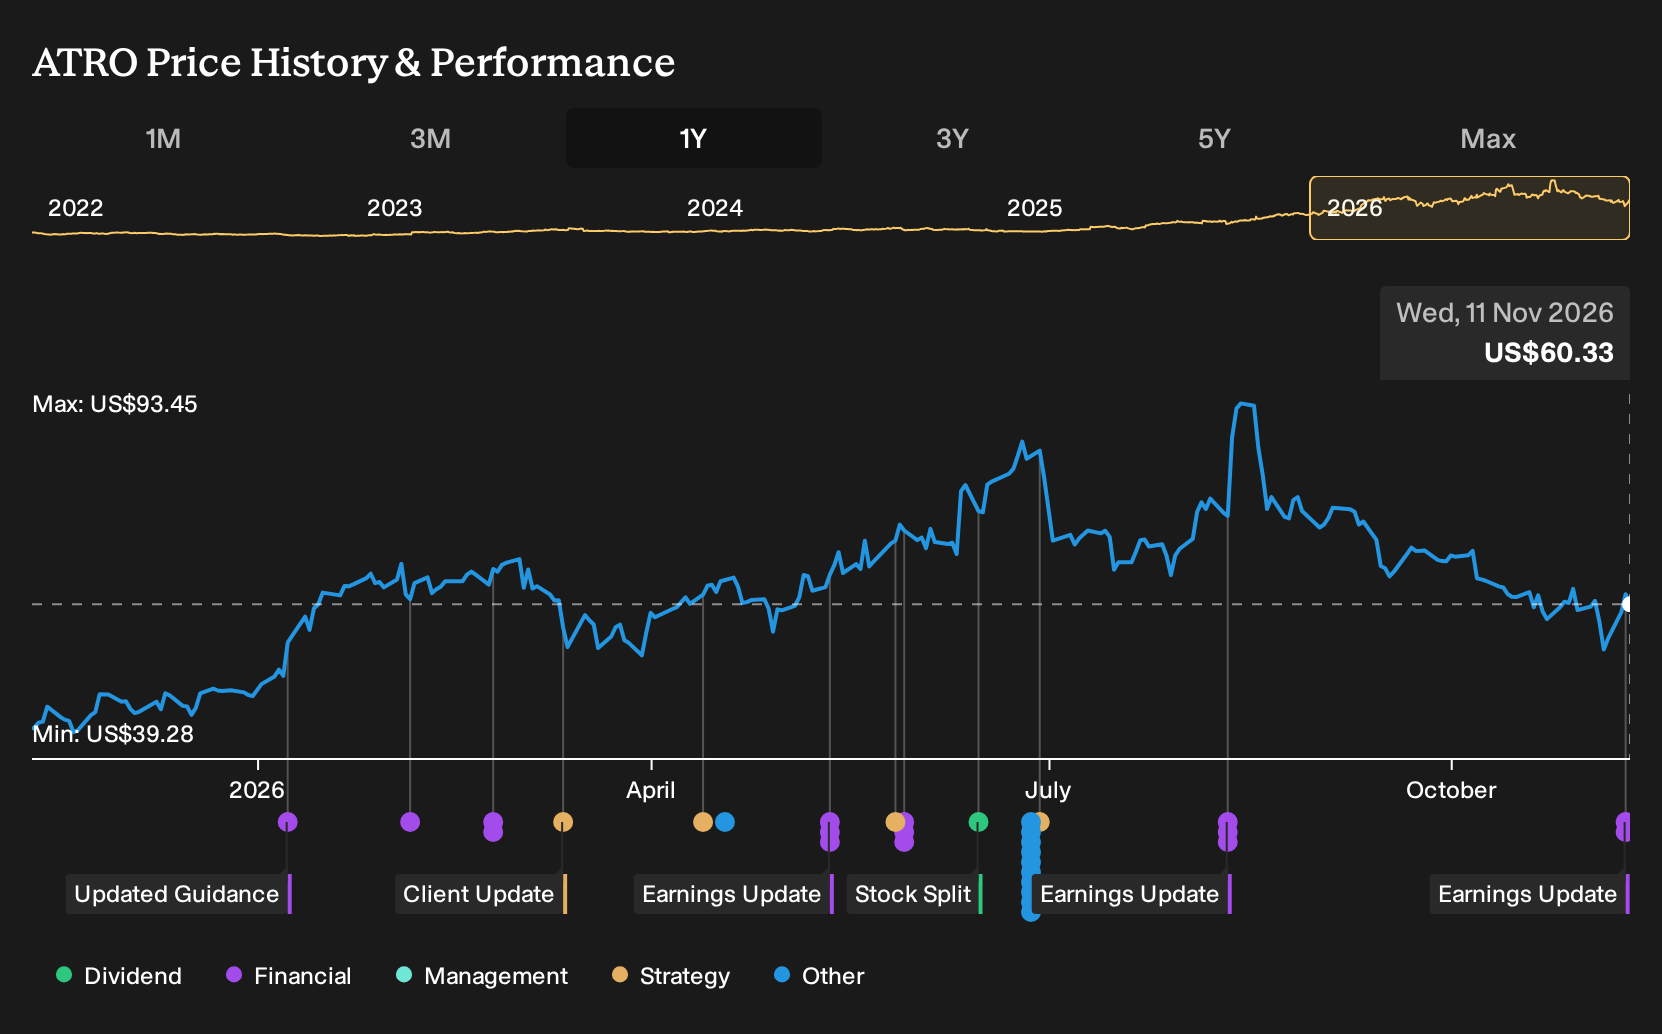
- Astronics reported third quarter 2026 sales of US$271.68 million with net income of US$52.2 million and diluted EPS from continuing operations of US$1.08, and confirmed full year guidance that includes expected 2026 revenue between US$1.02b and US$1.04b.
- The shift from a small net loss in the prior nine month period to US$112.8 million of net income highlights how volume, contract mix, and cost execution are now central to Astronics' earnings story.
- This report reviews how Astronics' record third quarter profitability and relatively cautious fourth quarter sales outlook may influence the existing investment narrative.
Scan how Astronics' record quarter compares with other aerospace and defense stocks by zeroing in on our hand picked 30 resilient stocks with low risk scores that may offer a steadier ride.
Astronics Investment Narrative Recap
A shareholder in Astronics needs to believe the business can turn record demand and a healthier Test Systems segment into sustained earnings while funding heavier investment. The third quarter showed that volume, contract mix, and cost execution can support profitability. The key short term catalyst remains clean execution on the aerospace backlog and U.S. Army radio test program.
The biggest current risk sits in execution and cost control. Tariffs, higher capex, ERP spending, and facility projects all pull on cash and margins. The latest results do not remove these concerns, although the strong nine month net income gives management a bit more breathing room if projects slip or trade costs persist.
The most relevant fresh data point is Astronics confirming 2026 revenue guidance of US$1.02b to US$1.04b, with fourth quarter sales expected between US$255 million and US$275 million. That outlook ties directly into the analyst consensus Narrative on Simply Wall St, which already leaned on record aerospace demand and a larger Test Systems contribution as key earnings drivers.
For you as an investor, that guide frames the next few quarters. Delivery timing on the TS 4549/T radio test contract and commercial aircraft build rates will likely shape whether Astronics lands toward the high or low end of its range. Any disruption here, on top of tariff costs and investment spending, would test the current margin story.
Astronics' analyst narrative projects US$1.4b in revenue and US$234.1 million in earnings by 2029, based on an assumed 13.1% yearly revenue growth rate and an increase in earnings of about US$155 million from current earnings of US$79.1 million.
Discover how Astronics' fair value indicates a 62% potential upside to its current price that could close sooner than you expect.
Exploring Other Perspectives
Some of the most optimistic analysts treated Astronics’ premium seating and Test Systems ramp as the key swing factor, with prior forecasts pointing to revenue of about US$1.5b and earnings of roughly US$249.3 million by 2029. You now have a record quarter that those views did not include, so it is worth comparing several viewpoints before deciding what feels realistic.
Explore 3 other Astronics fair value estimates, including one that suggests there may be as much as 77% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Astronics research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Astronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astronics' overall financial health at a glance.
Looking for more Astronics-sized investment ideas?
If this Astronics update has sharpened your view on the stock market but you want a wider watchlist, the Simply Wall St Screener can help you quickly narrow the field to opportunities that fit your style and risk tolerance.
- If you want potential value with quality to back it up, start with a 32 high quality undervalued stocks that combines balance sheet strength with solid cash flows.
- If capital preservation sits high on your list, focus on a list of solid balance sheet and fundamentals (23 results) that can handle tougher trading conditions.
- If you prefer companies flying under the radar, scan a 19 high quality undiscovered gems that still show strong fundamentals despite limited attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com