


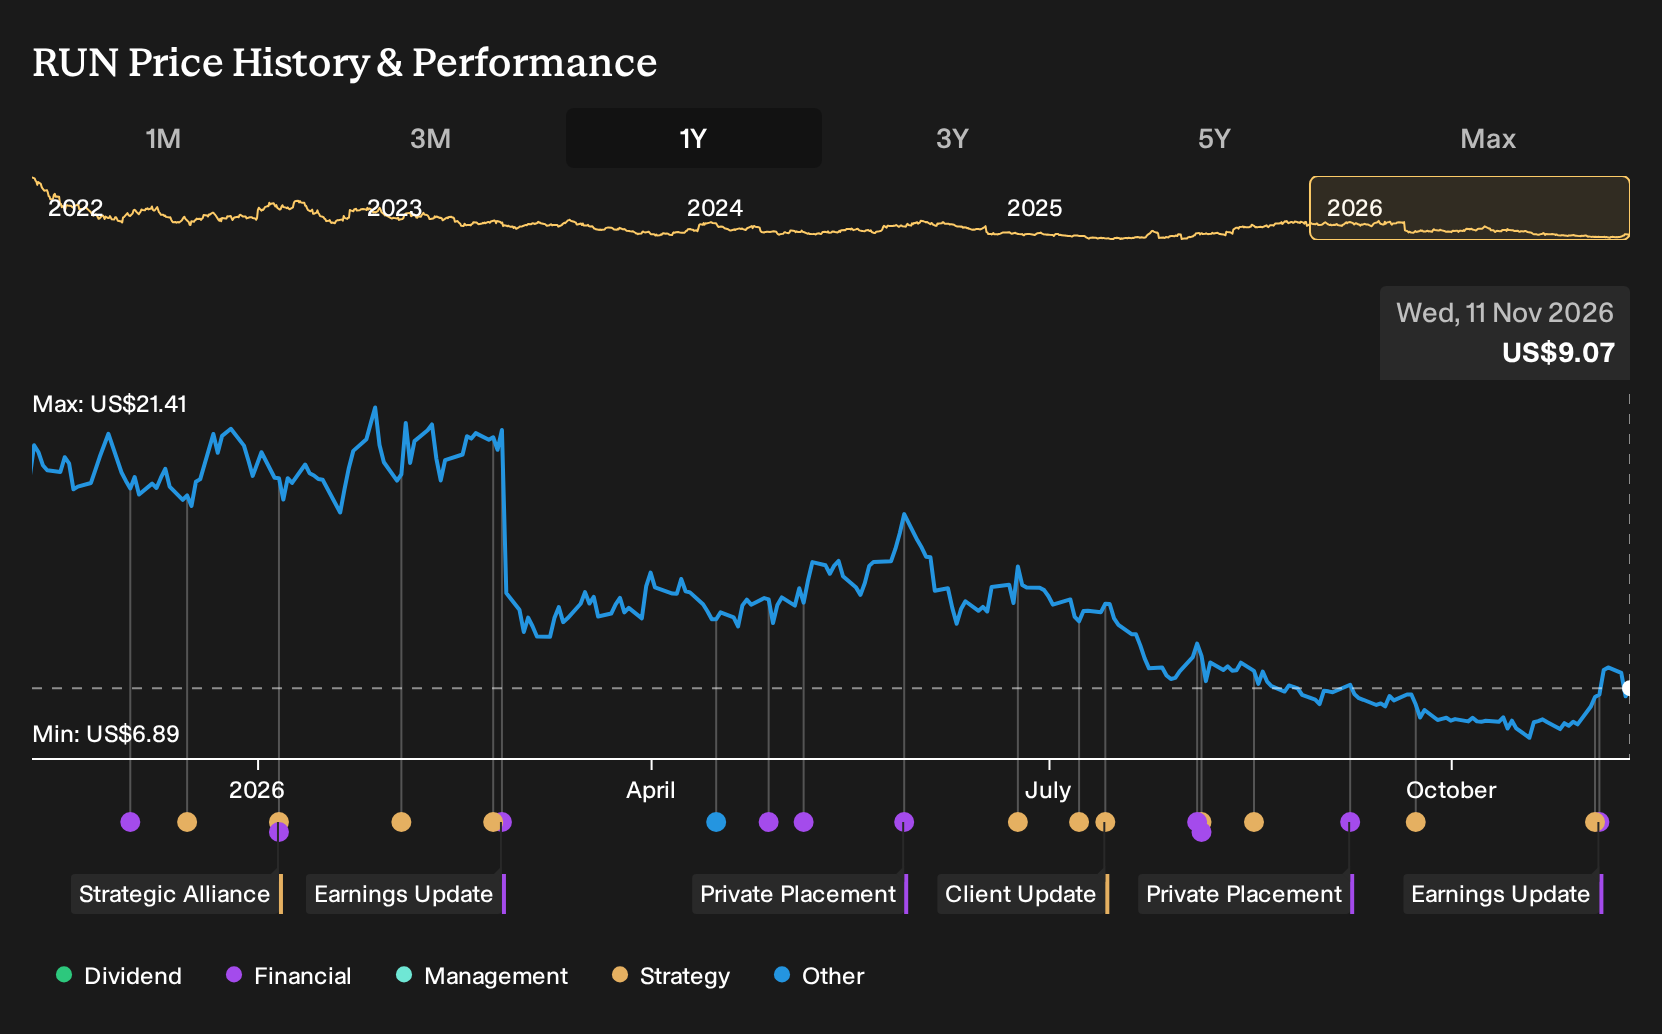
If you backed Sunrun for its home energy revolution story, the payoff so far has been painful. For Sunrun shareholders, the loss over the past year was 53.3%, including dividends. That result sits in sharp contrast to what the bullish and bearish analyst camps were debating in late 2025 about storage attachment, tax credits, financing access, and future P/E. If you had been weighing those assumptions on 11 November 2025, which part of that thesis proved least realistic?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Sunrun has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Two Sunrun Stories Investors Were Weighing
The shares cost US$19.75 at the start of the period, and Sunrun sat between two very different but plausible stories about what came next.
On the optimistic side, the bullish case saw a Fair Value of US$23.58 based on assumptions that revenue could grow 20.9% a year and profit margins might swing from deep losses to 43.8% within three years.
The more cautious view put Fair Value at US$15.92, assuming a more modest 10.4% annual revenue increase and warning that expiring 25D and 48E tax credits could shrink the residential solar market.
What The Evidence Did To The Sunrun Argument
Sunrun’s Q3 2026 report gave the bullish story its cleanest support. Total revenue was US$1.10b compared with US$724.6m a year earlier, while net income excluding one off items rose from US$16.6m to US$153.2m. Net margin moved from 2.3% to 13.9%, which pointed toward better profitability but still fell short of the very high margin jump the most optimistic case had pencilled in.
The lesson to carry to other stocks is simple. When a thesis leans on margin transformation, do not just watch the top line. Track net income and net margin side by side and compare the actual move in each reporting period with the specific percentage shift the story assumed.
What Sunrun’s Lower Price Is Asking You To Believe
Sunrun trades at US$9.07 after a 53.3% loss over the past year, and the bullish analyst Narrative on Simply Wall St still places its Fair Value above that level based on grid services and storage scale.
The central question is whether you think a buyer today is effectively betting that Sunrun can turn its storage fleet and direct origination push into reliable, recurring earnings power.
"Some bullish analysts expect Sunrun to scale its solar plus storage fleet and grid services into a recurring, infrastructure-like earnings stream that is not yet fully reflected in consensus expectations. The main factor that has to go right is Sunrun executing its shift toward higher-margin direct origination, while ramping grid services and distributed power plant contracts off its 4.6 GWh storage base and 425 MW California program."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Beyond Sunrun’s Rooftops
If Sunrun pulls you toward the grid story, it helps to look sideways. The same households using solar and storage still rely on data.
Every AI query, payment, and video needs data centers that can stay online without overheating.
Keeping those facilities powered and cooled requires specialized infrastructure that manages both electricity and heat inside cramped racks.
One supplier focuses on that backbone, from power systems to thermal gear that lets dense computing hardware keep running.
If demand for AI infrastructure keeps compounding, the role of that quiet plumbing could look very different.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 98% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com