


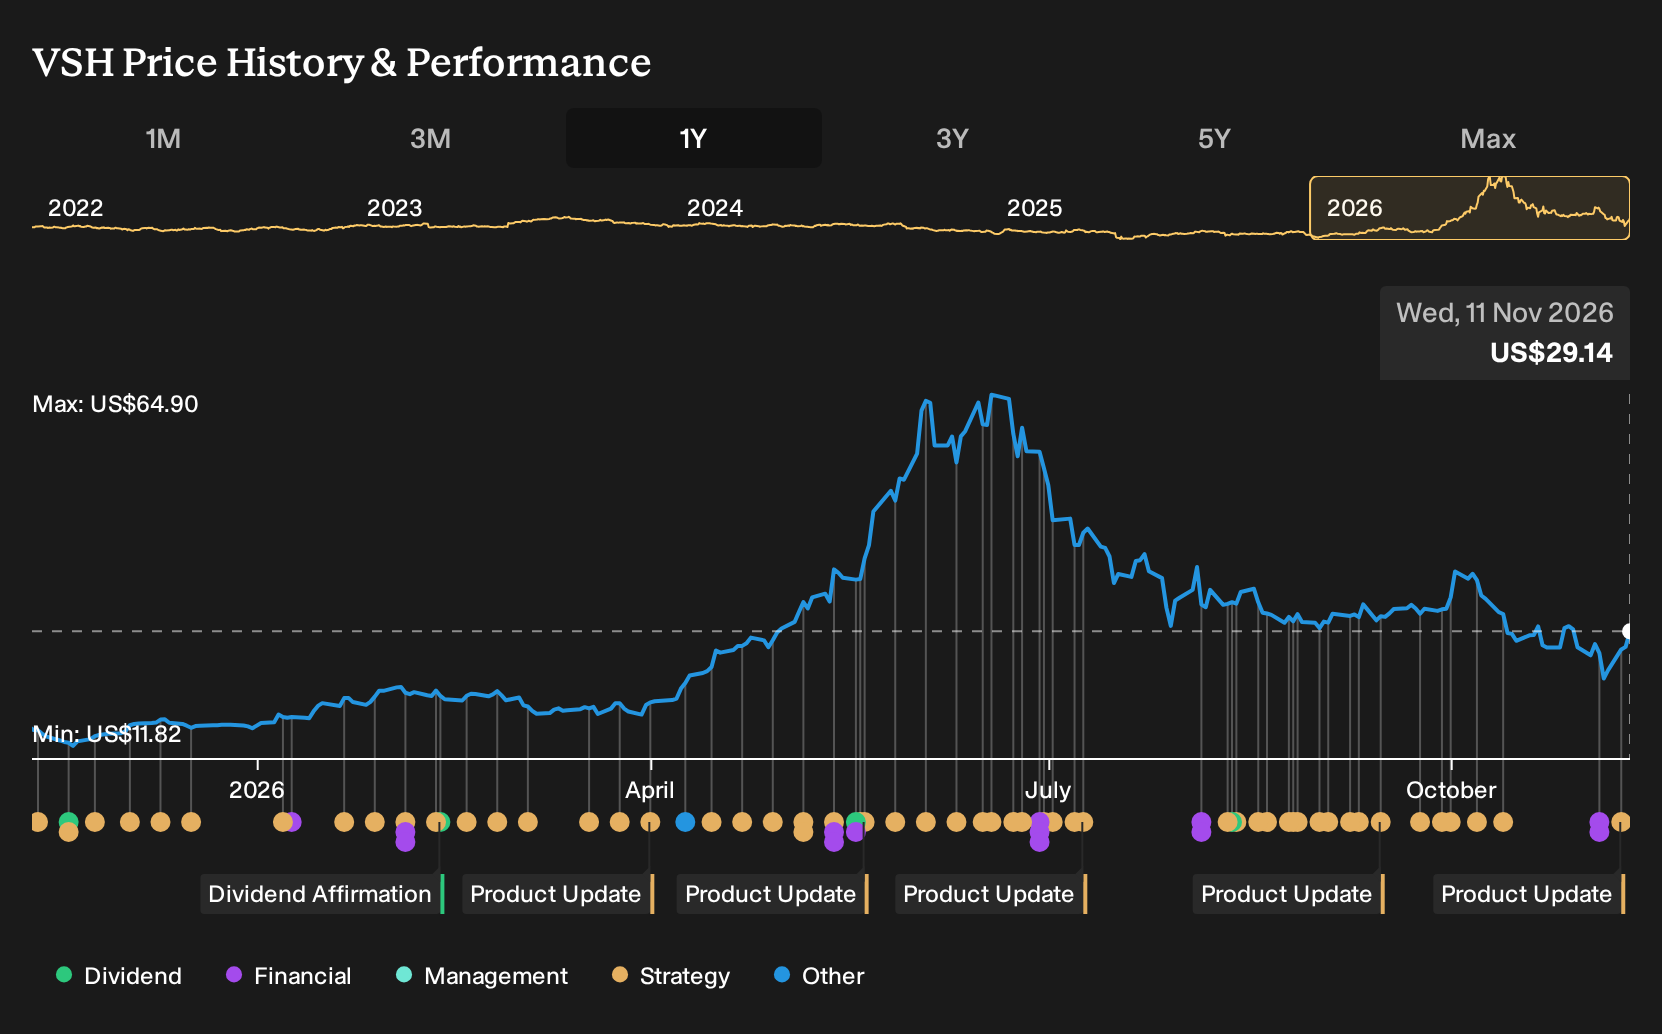
- Vishay Intertechnology reported third quarter 2026 sales of US$978.94 million and net income of US$58.97 million, with both sales and earnings higher than the same period a year earlier and with positive revenue guidance of US$990 million plus or minus US$15 million for the fourth quarter.
- The firm is pairing this improved profitability with a broad technology push, showcasing high density power, wide bandgap and energy storage solutions for AI data centers, e mobility, industrial power and sensing at electronica 2026. This reinforces how its product set ties directly into electrification and automation demand.
- The next area of focus will be how Vishay Intertechnology's stronger earnings and revenue outlook could influence the existing Vishay 3.0 investment narrative.
Scan Vishay Intertechnology's AI and electrification push against a curated group of peers by running your filters across 53 AI infrastructure stocks, which is shaping the next wave of data center and e-mobility hardware.
Vishay Intertechnology Investment Narrative Recap
To own Vishay Intertechnology, you need to believe the heavy capex behind Vishay 3.0 eventually lines up with durable demand in AI power, electrification and industrial projects. The latest quarter, with US$978.94 million in sales and a return to net income of US$58.97 million, supports that case but does not remove execution risk.
The near term swing factor is how efficiently new and existing fabs are loaded, with fourth quarter revenue guided to around US$990 million. The biggest risk remains that sizeable capacity and revolving credit commitments meet softer orders or pricing, which would keep free cash flow under pressure and limit flexibility.
The analyst consensus narrative on Simply Wall St focuses on capacity buildout for AI data center, industrial and e-mobility demand. The Electronica 2026 booth directly showcases that vision, with silicon and silicon carbide MOSFETs, capacitors, magnetics and resistors arranged into full reference designs for AI servers, chargers, inverters and safety systems.
For a shareholder, this kind of showcase matters because it links the capex story to concrete design wins and future utilization rather than just slideware. The risk is clear as well. If these AI and electrification programs do not ramp into high volume, the new Western fabs and low cost campuses in Mexico and India could run below optimal load, limiting margin progress.
Vishay Intertechnology's narrative projects US$5.0b revenue and US$640.7 million earnings by 2029. This assumes 14.6% yearly revenue growth and an earnings increase of about US$612.3 million from US$28.4 million at present.
Uncover why Vishay Intertechnology's fair value indicates a potential 37% upside to its current price before that discount starts to close.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Vishay Intertechnology’s margin potential rather than its heavy capex risk. Before this earnings print and electronica showcase, the bullish narrative was built on revenue reaching about US$5.3b and earnings of roughly US$887.0 million by 2029. That is a very different trajectory. Use this product and earnings news as a prompt to compare both stories and see which assumptions feel more realistic to you.
Explore another Vishay Intertechnology fair value estimate, including one that suggests as much as 155% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vishay Intertechnology research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Vishay Intertechnology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vishay Intertechnology's overall financial health at a glance.
Looking for more investment ideas beyond Vishay Intertechnology?
If this Vishay Intertechnology update has sharpened your thesis, use that same lens to scan a wider opportunity set. The Simply Wall St Screener lets you filter for the kind of balance sheets, income profiles and dividend streams that best match your risk tolerance and time horizon.
- Prefer capital preservation and steadier business profiles over big swings? Start with a basket of 30 resilient stocks with low risk scores that score well on resilience and financial strength.
- Hunting for cash rich companies with room to reinvest and still return money to shareholders? Filter for stocks with strong fundamentals and surplus cash using the list of solid balance sheet and fundamentals (23 results).
- Income is your priority and you want yields above cash rates? Focus your research on 6 dividend fortresses that pair higher payouts with durable operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com