


- Avnet reported first quarter 2027 sales of US$10,717.98 million and net income of US$282.17 million, with basic earnings per share from continuing operations at US$3.43 and diluted earnings per share at US$3.28.
- The company paired these results with second quarter 2027 guidance that points to US$11.1 billion to US$11.4 billion in sales and GAAP diluted earnings per share of US$3.80 to US$4.05, which reflects its operating scale and demand visibility across its distribution and solutions businesses.
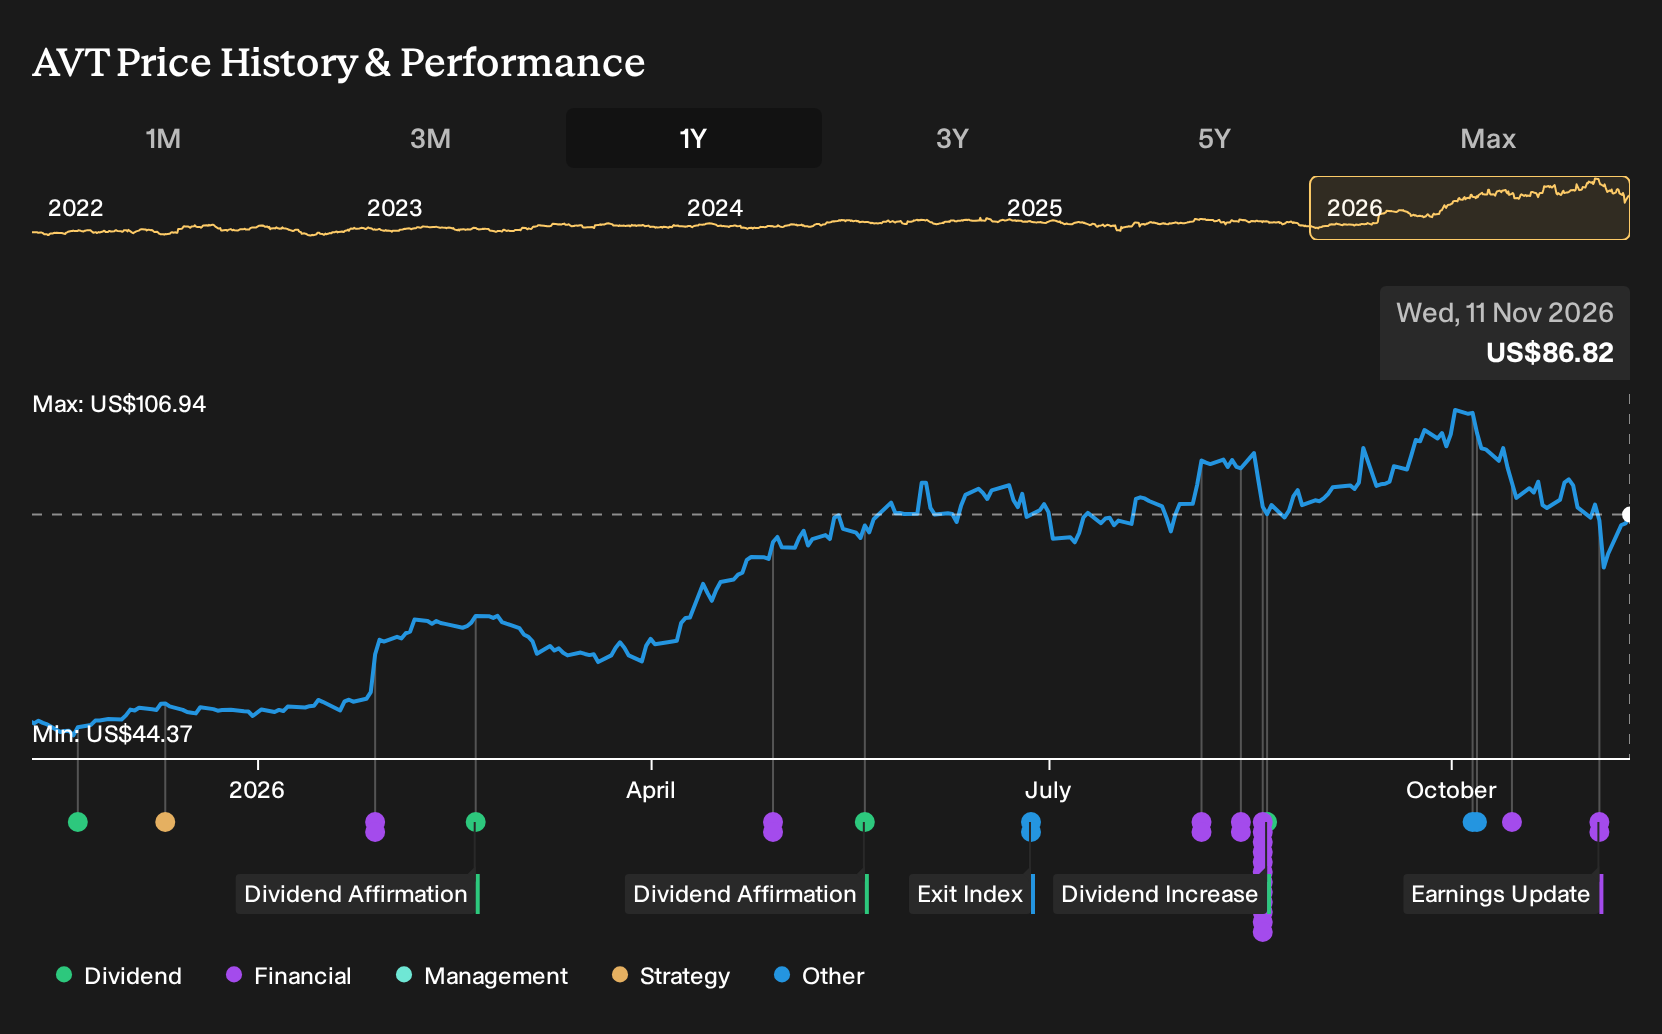
- This article reviews how Avnet’s first quarter earnings and higher second quarter EPS guidance may influence the existing investment narrative.
Scan beyond Avnet and see how other technology distributors and hardware plays with similar earnings momentum are lining up in our curated 32 high quality undervalued stocks.
Avnet Investment Narrative Recap
For an investor to stay with Avnet, the core belief is that the distributor model can keep turning tight supply, AI and data center demand, and design services into growing earnings without letting gross margin compression become permanent. The recent quarter, with US$10,717.98 million in sales and US$282.17 million in net income, supports that operating thesis rather than changing it.
The most important near term swing factor still looks like how mix toward Asia and memory related products plays out, because that mix has previously pressured gross margins. The biggest risk remains a sharp reset in memory pricing or a pause in orders that would test Avnet’s operating leverage and working capital discipline.
The clearest operational signal is Avnet’s second quarter 2027 guidance for US$11.1 billion to US$11.4 billion of sales and GAAP diluted EPS of US$3.80 to US$4.05. That outlook ties directly into what the analyst consensus Narrative on Simply Wall St had already highlighted, which is a story built on operating scale and improving capital efficiency.
For investors, the link to catalysts is straightforward. Management’s guidance reflects their current read on demand, book to bill and pricing as Avnet leans into AI and data center related exposure along with Farnell’s higher margin profile. The risk side is that any reversal in tight supply or memory pricing could make these EPS ranges harder to sustain and would quickly test execution.
Avnet's narrative projects US$59.7b revenue and US$1.9b earnings by 2029. That profile assumes 22.5% yearly revenue growth and an earnings increase of roughly US$1.3b from US$564.8m today.
Uncover why Avnet's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Avnet’s AI and edge projects as the real swing factor, not memory pricing. Before this earnings release, that bullish group was already modeling about US$60.0b in revenue and US$1.6b in earnings by 2029. You can compare those higher expectations with your own view and decide which narrative might need updating after this quarter.
Explore 2 other Avnet fair value estimates, including one that suggests as much as 44% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avnet research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avnet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avnet's overall financial health at a glance.
Looking for more investment ideas beyond Avnet?
Once you have formed a view on Avnet, it helps to pressure test that thinking against other opportunities using the Simply Wall St Screener. You can filter for different qualities that matter to you and quickly see which stocks line up with your preferred mix of quality, risk and income.
- If you want potential upside with stronger fundamentals as a starting point, take a look at the 19 high quality undiscovered gems that might not yet be widely followed.
- If resilience matters most to you, focus on the 30 resilient stocks with low risk scores to see which businesses score well on stability and downside protection.
- If balance sheet strength is your priority, filter for companies through the list of solid balance sheet and fundamentals (23 results) and see which ones keep debt and funding risk firmly in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com