


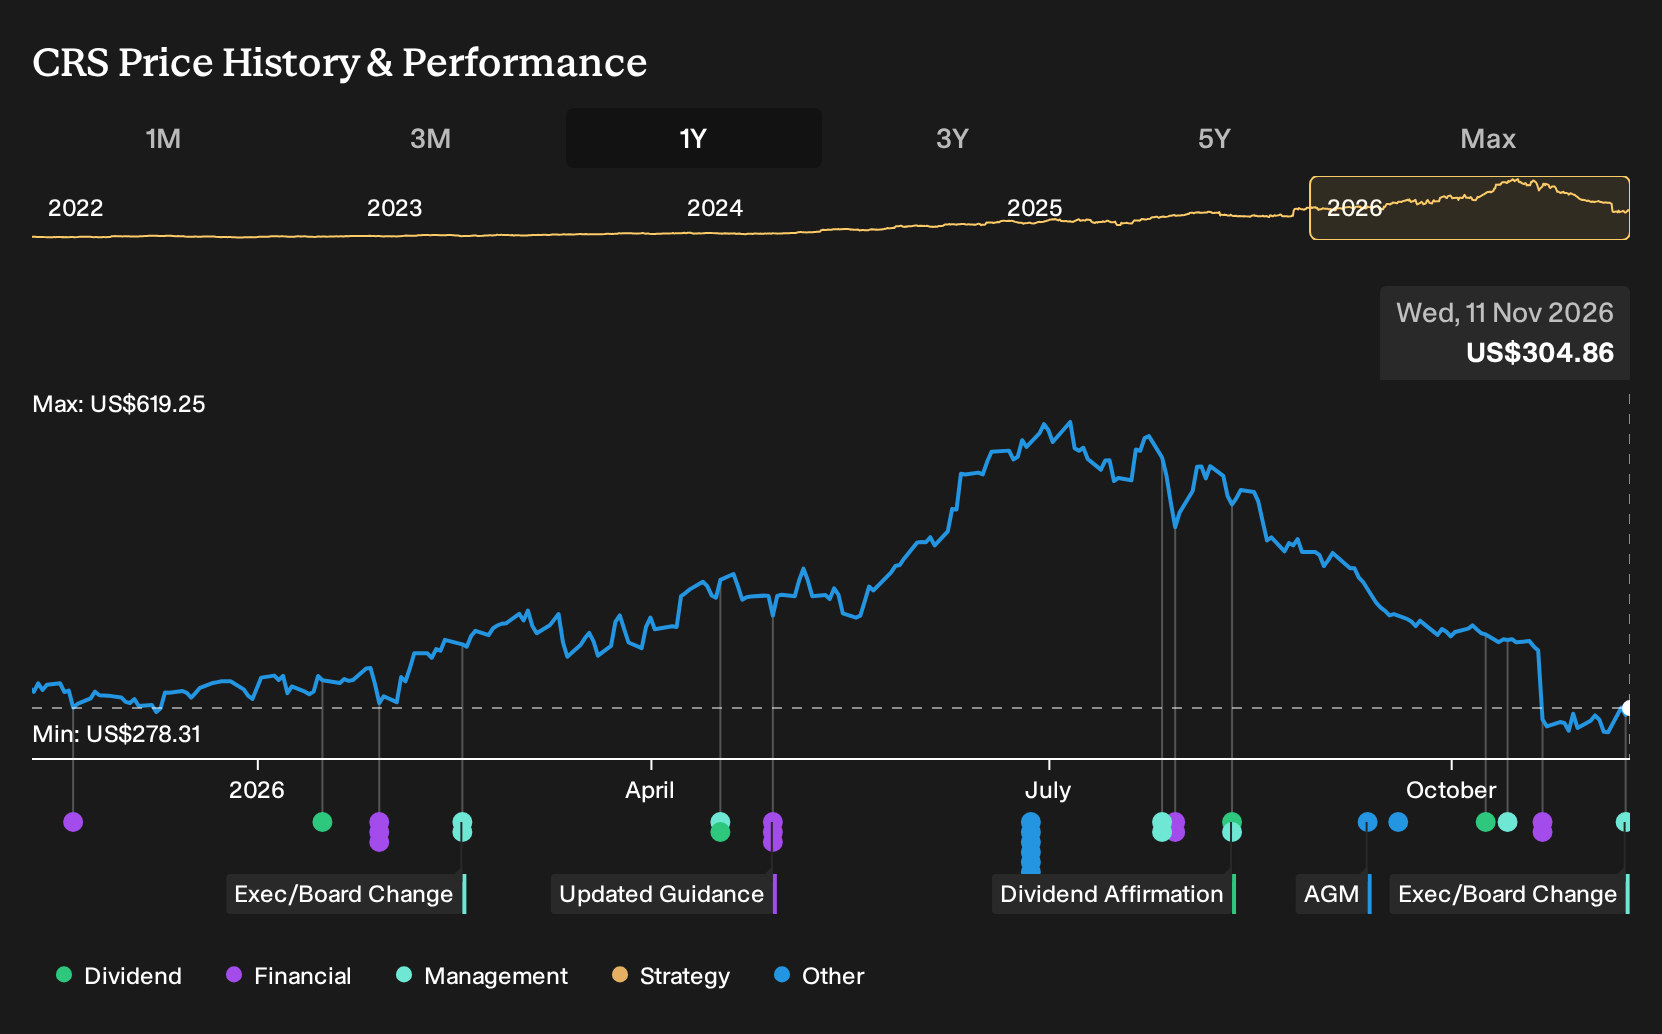
- Carpenter Technology recently reshaped its senior ranks, promoting Marshall Akins to Senior Vice President, Chief Operating Officer, and John Huyette to Vice President, Chief Commercial Officer, while also upgrading its investor relations leadership.
- The decision to combine operational oversight, commercial responsibility and investor relations under refreshed leadership highlights management’s focus on execution, customer mix and capital communication as demand patterns evolve.
- The next area of attention is how Carpenter Technology's new COO role and broader leadership reshuffle might influence the existing investment narrative.
Scan how Carpenter Technology’s leadership reset compares with other materials players preparing for corrosion resistant demand by running through the hand picked 33 best rare earth metal stocks.
Carpenter Technology Investment Narrative Recap
To own Carpenter Technology, you need to be comfortable with a business that leans heavily on aerospace, defense and energy demand, and is funding a large brownfield expansion that is planned to add roughly 9,000 tons of melt capacity by early fiscal 2028. The analyst consensus Narrative on Simply Wall St leans on that project and explicit operating income targets, so the key short term catalyst still sits in day to day execution and mix rather than in this leadership shuffle.
The biggest near term risk remains the same. Any cooling in aerospace or defense volumes, or hiccups on the multi year expansion, could leave Carpenter Technology carrying higher capital and depreciation without the planned lift in operating income and free cash flow. The fresh COO and CCO appointments may help coordination, but do not by themselves change those operational swing factors.
The most relevant fresh development is Marshall Akins stepping into the new Chief Operating Officer role with responsibility for Specialty Alloys Operations and Performance Engineered Products. This puts one leader directly over the assets that are expected to support aerospace, power generation and other high value alloys, plus the production planning and procurement functions that can affect throughput and on time delivery.
For investors watching catalysts such as aerospace build rates and the brownfield ramp, this matters mainly through execution quality. A single point of accountability across SAO, PEP and planning could help Carpenter Technology align capacity, mix and contract commitments if demand for corrosion resistant alloys and aerospace materials stays tight. The core risks flagged in earlier guidance, including construction delays or demand setbacks, still sit with the projects and end markets rather than with the org chart itself.
Carpenter Technology's narrative projects US$4.3b revenue and US$979.9 million earnings by 2029, based on analysts’ forecast that revenue grows about 10.4% per year and earnings increase by roughly US$410 million from US$569.5 million today.
Uncover why Carpenter Technology's fair value indicates a 44% potential upside to its current price. This suggests a discount that could narrow faster than investors expect.
Exploring Other Perspectives
You can also weigh one key concern from the lowest Carpenter Technology forecasts. Those analysts worry more about valuation than operations, assuming similar 2029 earnings of about US$993.2 million on roughly US$4.2b in revenue, while using a lower 19.5x P/E. Their cautious stance could shift if the leadership changes reshape expectations.
Explore 2 other Carpenter Technology fair value estimates, including one that suggests it could be worth just $400.59!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Carpenter Technology research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Carpenter Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carpenter Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Carpenter Technology?
If the Carpenter Technology story has you thinking about portfolio upgrades, it can help to line it up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you scan for companies that match your own checklist rather than just following headline names.
- If you want income to do more of the heavy lifting, filter for robust payers by running through 6 dividend fortresses, which aim to combine yield with staying power.
- If capital preservation comes first for you, focus on stability by checking out 30 resilient stocks with low risk scores, which score well on resilience and downside control.
- If you prefer strong balance sheets over exciting stories, narrow the field to sturdier businesses through the list of solid balance sheet and fundamentals (23 results) so you can compare their fundamentals side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com