


What Kimbell Royalty Partners' Latest Earnings Signal
Kimbell Royalty Partners (KRP) just reported third quarter 2026 results that mixed higher revenue with softer profitability, giving investors fresh data on how its royalty model is handling current energy markets.
The partnership posted US$86.33 million in sales for the quarter, compared with US$80.62 million in the same period last year, while net income came in at US$15.05 million versus US$19.68 million previously, alongside basic and diluted EPS of US$0.12 from continuing operations.
The share price of Kimbell Royalty Partners has held at US$15.26 after a 1-day share price return of 0.73%, softening over the past month yet still recording a 26.85% year to date share price return and a 5-year total shareholder return of 85.30%. This frames recent earnings and the US$367 million of 2026 acquisitions as part of a longer, patient compounding story rather than a short term trading swing.
Scan other income-focused royalty and resource plays showing similar acquisition activity with the curated 6 dividend fortresses that share some of Kimbell Royalty Partners' cash flow appeal.
After a near 27% move this year and fresh acquisitions in the mix, the question for Kimbell Royalty Partners is simple. Is most of the upside already in the rearview mirror or not yet priced in?
Most Popular Narrative: 21% Undervalued
Against a last close of $15.26 for Kimbell Royalty Partners, the analyst consensus Narrative on Simply Wall St anchors fair value at $19.20, implying a material gap in how the units are currently priced. That framework leans heavily on acquisition driven scaling, disciplined leverage and cash distribution policies, all evaluated using a 7.24% discount rate.
The main thing that has to go right is that Kimbell Royalty Partners continues to source accretive deals and manage leverage around its stated target, while rig activity and well conversions on its acreage sustain production and cash available for distribution.
What is behind 18 investors see Kimbell Royalty Partners as 21% undervalued.
Result: Fair Value of $19.20 (UNDERVALUED)
Still, Kimbell Royalty Partners carries real pressure points if the story breaks, including richer bidding rivals in key basins and leverage that amplifies any downturn in drilling activity.
Find out about the key risks to this Kimbell Royalty Partners narrative.
Another Take On Kimbell Royalty Partners' Valuation
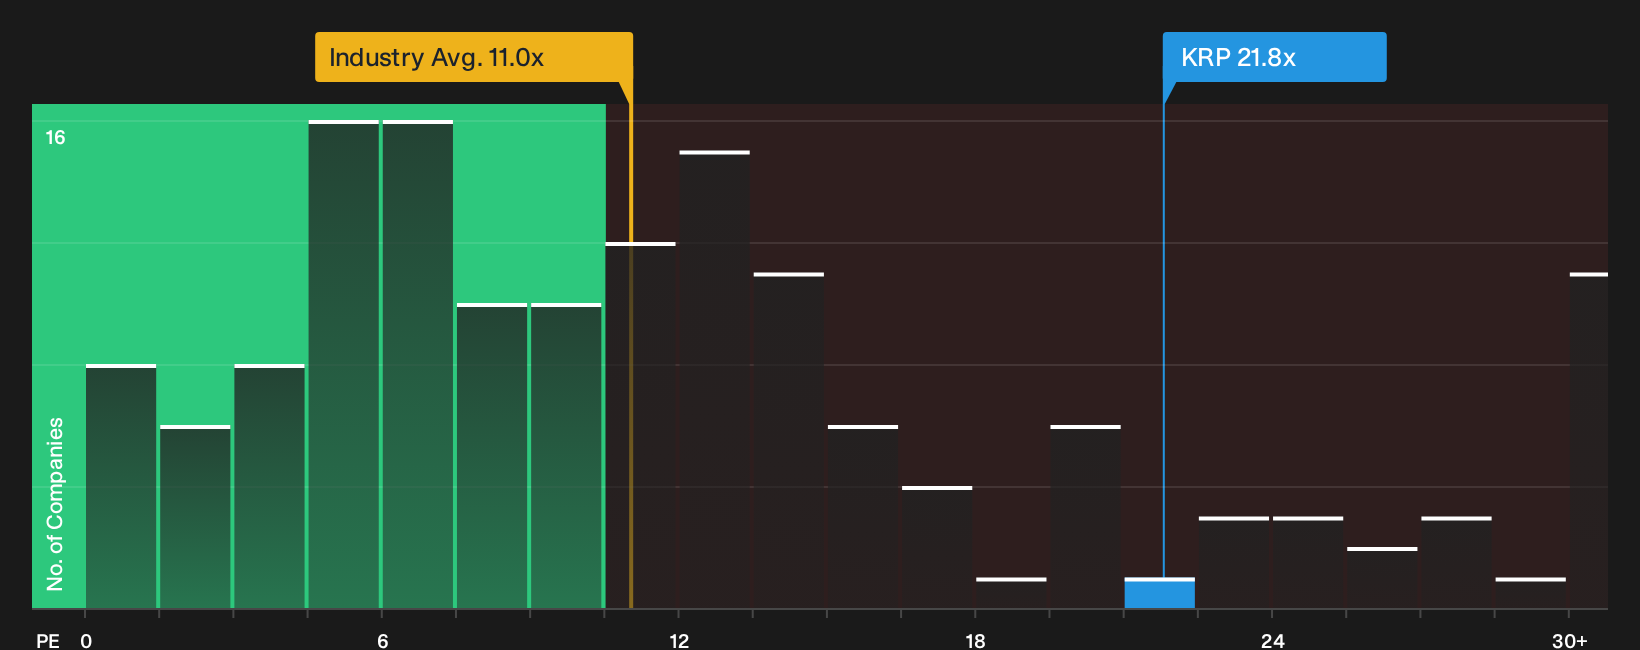
The narrative leans on a fair value of $19.20, yet the current P/E of 21.8x paints a different picture. That multiple is roughly 2x the US Oil and Gas industry at 11x and well above a fair ratio of 15.9x, which points to valuation risk if expectations cool.
When pricing drifts this far above both peers and a fair ratio anchor, it raises a simple question for anyone tracking Kimbell Royalty Partners. Is this a premium you are comfortable paying for the current story, or one you would want evidence to justify before committing fresh capital?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on value and risk can feel uncomfortable. Move quickly from headline impressions to hard numbers, and weigh both sides for yourself using the 4 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Kimbell Royalty Partners?
If Kimbell Royalty Partners has sharpened your focus on quality and income, do not stop here. Broader opportunity sits in the wider market, waiting for you to investigate.
- Target income and resilience by reviewing a hand picked group of high yielding companies that aim to protect payouts through different cycles with the 6 dividend fortresses.
- Hunt for mispriced quality and see which businesses combine strong fundamentals with potentially attractive entry points using the 32 high quality undervalued stocks.
- Prioritise durability first and scan for companies with cleaner balance sheets and robust financial footing by running the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com