


- Aramark recently became the focus of fresh earnings attention as analysts updated forecasts for its upcoming quarter, with consensus expectations centering on earnings per share of between $0.49 and $0.75 and revenue projections around $5.27b that capture both United States and international operations.
- An important angle is how these projections emphasize operating income and segment level performance, which links directly to Aramark’s contract heavy model, client retention record, and the way its international and domestic units may be pulling different financial levers at the same time.
- The next step is to consider how Aramark’s longer term investment narrative intersects with these higher earnings expectations, particularly around operating income strength.
Scan how Aramark’s contract-heavy model compares with other service operators by reviewing our hand picked list of list of solid balance sheet and fundamentals (23 results)
Aramark Investment Narrative Recap
To own Aramark, you need to be comfortable with a contract driven model that leans on high client retention, steady new wins, and disciplined execution across food and support services. The key near term swing factor is how effectively management converts those contracts into operating income and cash, given interest costs and a P/E that screens as expensive on several measures.
Recent earnings expectations around $0.49 to $0.75 per share keep attention firmly on operating margin resilience and labor inflation. If results land near the lower end, the biggest risk is renewed concern about free cash flow conversion and balance sheet flexibility, rather than any change to the core contract portfolio.
The analyst consensus Narrative on Simply Wall St highlights contract momentum, international expansion, and technology tools like Culinary CoPilot and LaborIQ as the main operational drivers to watch. In that context, the focus on upcoming quarterly operating income looks less like a new story and more like a checkpoint on whether these engines are still doing their job.
With no fresh company announcements on record tied directly to this earnings window, the most relevant context is the previously flagged Nexus data center hospitality rollout, which is expected to add higher margin, lower capex revenue over time. Earnings around $5.27b in sales will help you gauge whether Aramark is creating the room it needs to fund Nexus, manage leverage, and still handle reputational and contract quality risks.
Aramark's narrative projects US$25.0b revenue and US$867.8m earnings by 2029. This aligns with analyst assumptions for 8.0% yearly revenue growth and an earnings increase of about US$484.9m from US$382.9m today.
Uncover why Aramark's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
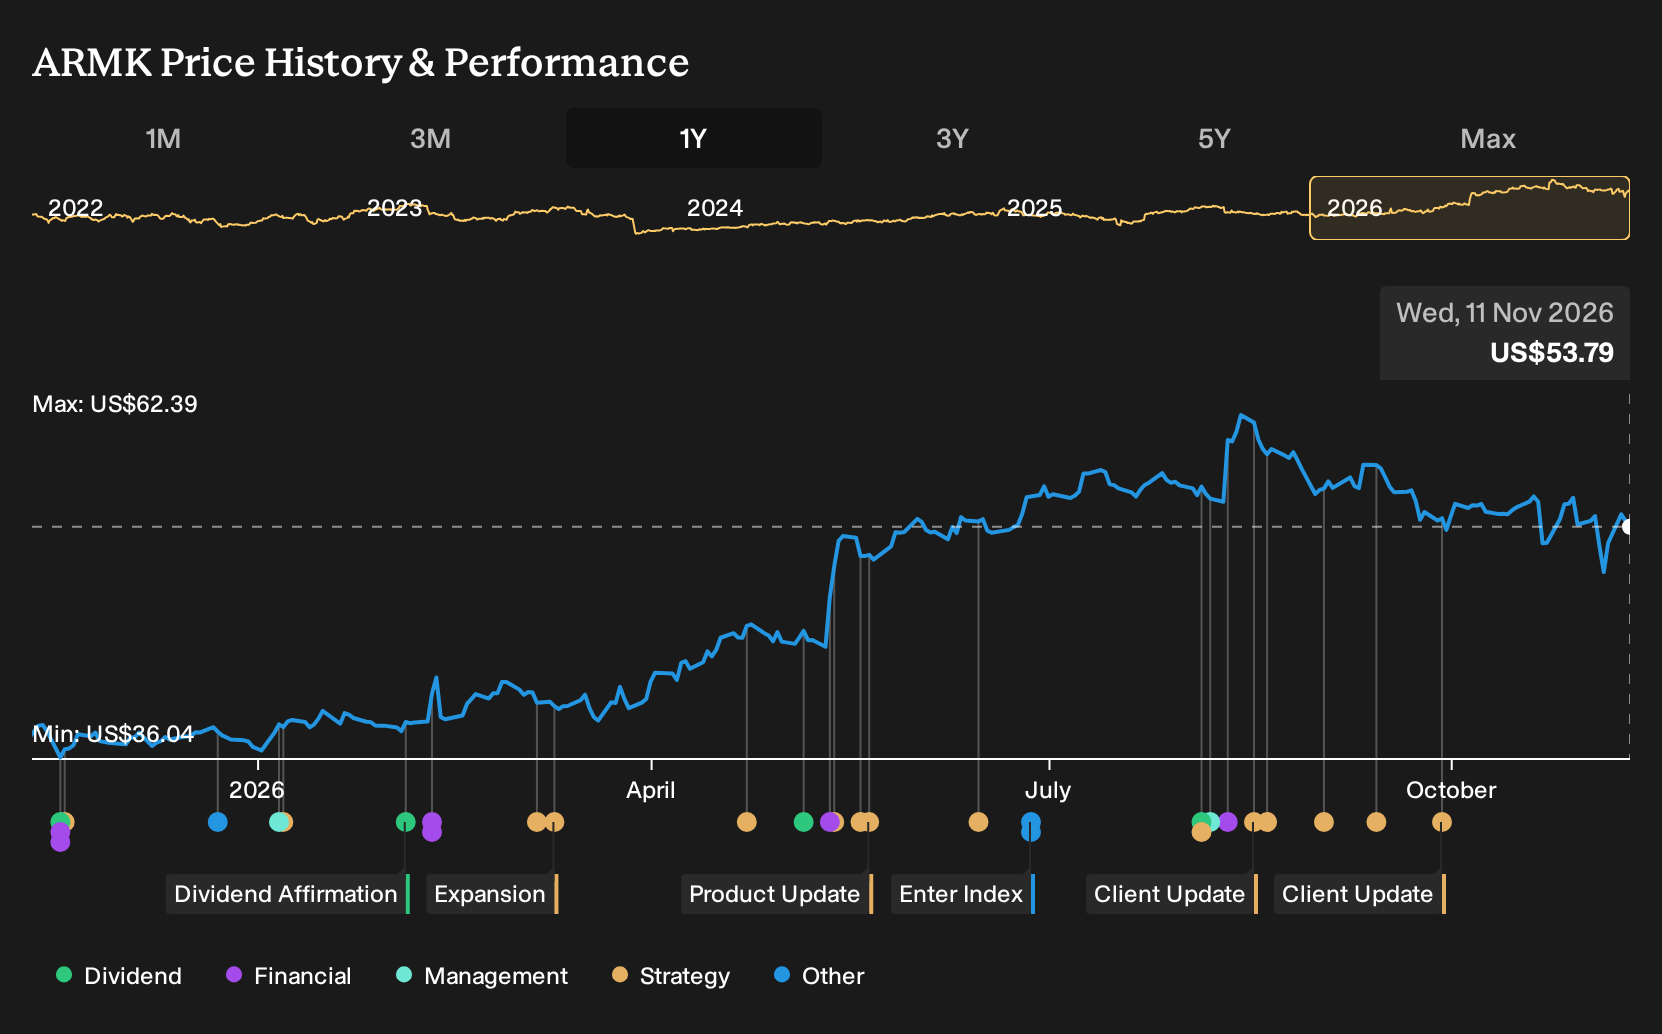
Exploring Other Perspectives
One alternate take on Aramark puts Nexus and AI data center hospitality in the spotlight as a risk rather than a growth engine. The most cautious analysts were working off revenue of about US$24.7b and earnings near US$878.8m by 2029. That camp looks more skeptical and may react very differently once this earnings news is absorbed.
Explore 2 other Aramark fair value estimates, including one that suggests as much as 36% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own, well-researched view.
- A great starting point for your Aramark research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aramark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aramark's overall financial health at a glance.
Looking for more ideas beyond Aramark?
Once you understand Aramark’s story, it can help to compare it with other opportunities that match different risk and income preferences. The Simply Wall St Screener gives you a fast way to compare companies with clear financial traits, so you can build a watchlist that fits how you like to invest.
- If you want potential mispricing with quality metrics to back it up, take a look at 32 high quality undervalued stocks that already clear a solid fundamental bar.
- For investors who care most about income strength and yield resilience, scan through 6 dividend fortresses that focus on distributing cash to shareholders.
- If capital preservation and balance sheet strength sit at the top of your checklist, filter for 30 resilient stocks with low risk scores that score well on financial robustness and lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com