


- Novo Nordisk reported mixed signals for its GLP-1 franchise, including new FDA safety label warnings for vision loss risks and strong real-world and clinical data updates across obesity and MASH treatments.
- The company is balancing higher regulatory scrutiny with heavy R&D and manufacturing investment in semaglutide, CagriSema, and broader obesity care. This could influence how durable its GLP-1 economics prove to be.
- We will now explore how Novo Nordisk's fresh FDA safety warning on GLP-1 drugs could reshape the longer term investment narrative.
Novo Nordisk Investment Narrative Recap
To own Novo Nordisk, you need to believe its GLP 1 platform can keep pulling in demand across obesity, diabetes and now liver disease, despite tighter regulation and new safety language. The short term swing factor is operational execution around Wegovy and semaglutide supply and manufacturing after the Q3 impairment of DKK 701 million on property, plant and equipment.
The biggest near term risk sits in regulatory and safety perception. The fresh FDA label warning on rare vision loss, pressure around thyroid related boxed warnings and a changing management bench, including a new CFO, all raise execution questions but do not yet look like a clear break to the core obesity and diabetes franchise.
The most relevant fresh update is Novo Nordisk’s real world data from the PLATINUM Truveta and RHODIUM 2 MASH studies using semaglutide 2.4 mg. This sits right at the intersection of obesity, liver disease and the GLP 1 debate. According to Tokyo, an investor in the Simply Wall St Community, the long term story rests heavily on extending this platform into adjacent cardiometabolic problems.
These observational datasets are not randomized trials and Novo Nordisk itself highlights limitations such as potential confounding, coding issues and relatively short follow up. Even with those caveats, positive associations in liver and cardiometabolic markers could support the ESSENCE phase 3 program and keep semaglutide’s multi disease positioning as a key operational catalyst while regulatory scrutiny and safety communication remain the main risk anchors.
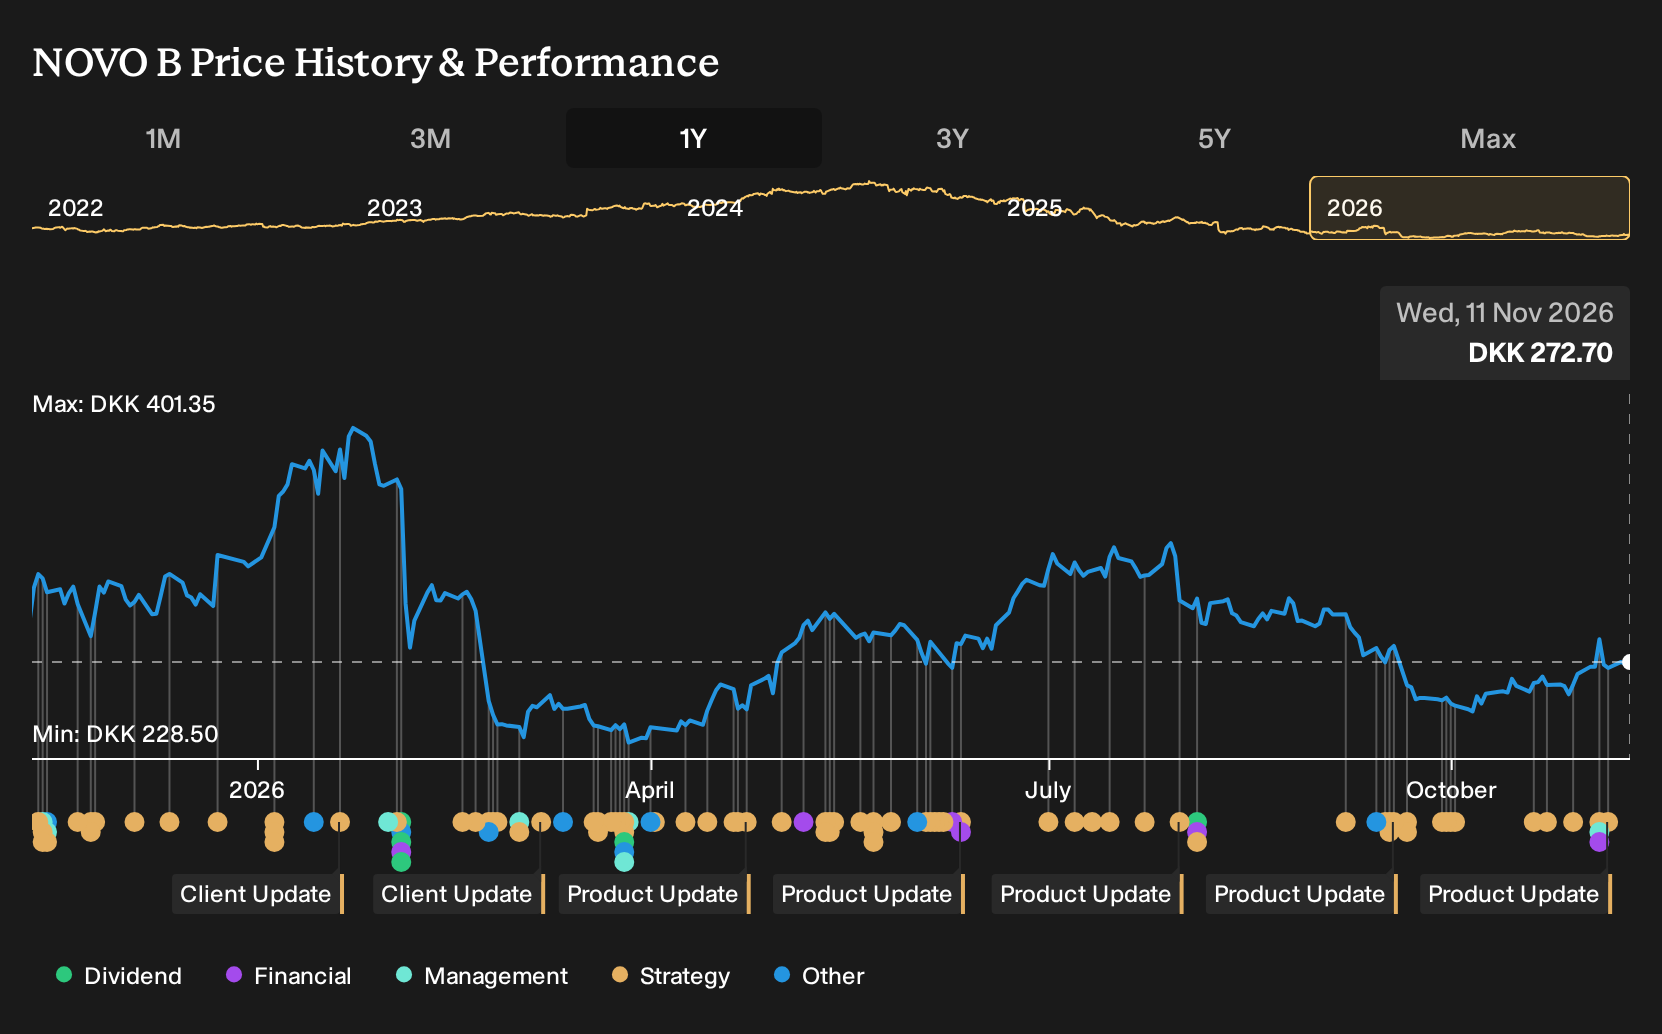
Using Tokyo’s revised assumptions of 11.7% annual revenue growth and a future profit margin of 34.8%, the narrative lands on a fair value of DKK 851.04 for Novo Nordisk as its GLP 1 cash flows are projected forward and discounted back into today’s money.
Uncover why Novo Nordisk's fair value indicates a 212% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One sharp contrast to Tokyo’s upbeat Novo Nordisk view is the bearish focus on pricing pressure. The lowest analysts were already modelling revenue slipping to about DKK 284.0 billion and earnings easing to roughly DKK 79.3 billion by 2029, before this FDA safety warning and new MASH data. Use that gap to stress test your own expectations.
Explore 16 other Novo Nordisk fair value estimates, including one that suggests it could be worth just DKK 287.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novo Nordisk research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Novo Nordisk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novo Nordisk's overall financial health at a glance.
Looking for more investment ideas beyond Novo Nordisk?
Once you have a view on Novo Nordisk, it can help to widen the lens and compare it with other opportunities that match your risk profile and return goals. The Simply Wall St Screener lets you do that in a structured way so you can move from a single stock story to a watchlist built around clear criteria.
- If capital preservation comes first for you, start with a basket of companies that our models flag as relatively resilient, using the 207 resilient stocks with low risk scores as a reference point for building a steadier foundation.
- If your focus is on stronger balance sheets and cleaner fundamentals, filter for businesses with solid financial footing through the list of solid balance sheet and fundamentals (197 results) and see which ones match your quality threshold.
- If you want to hunt for under-the-radar opportunities with healthier fundamentals, scan through a curated set of potential sleepers via the 567 high quality undiscovered gems and shortlist ideas that deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com