


Unprecedented global demand for advanced artificial intelligence hardware continues to drive historic revenue expansion across leading semiconductor foundries. As tech hyperscalers aggressively expand data center capacity, cutting-edge wafer production and next-generation packaging capabilities remain fully booked, insulating top-tier chip manufacturers from broader consumer electronics demand fluctuations.
Underlining this booming chip demand, Taiwan Semiconductor Manufacturing (TSM) reported an October revenue surge of nearly 60% year-over-year.
About Taiwan Semiconductor Manufacturing
Taiwan Semiconductor Manufacturing — widely known as TSMC — is the world’s leading dedicated semiconductor foundry. Headquartered in Taiwan, the company manufactures advanced chips for global technology leaders, including Nvidia (NVDA) and Apple (AAPL). Its cutting-edge 2-nanometer, 3-nanometer, and advanced packaging technologies make it a key player in the artificial intelligence (AI) and semiconductor industries.
TSM Stock Delivers Strong 2026 Returns
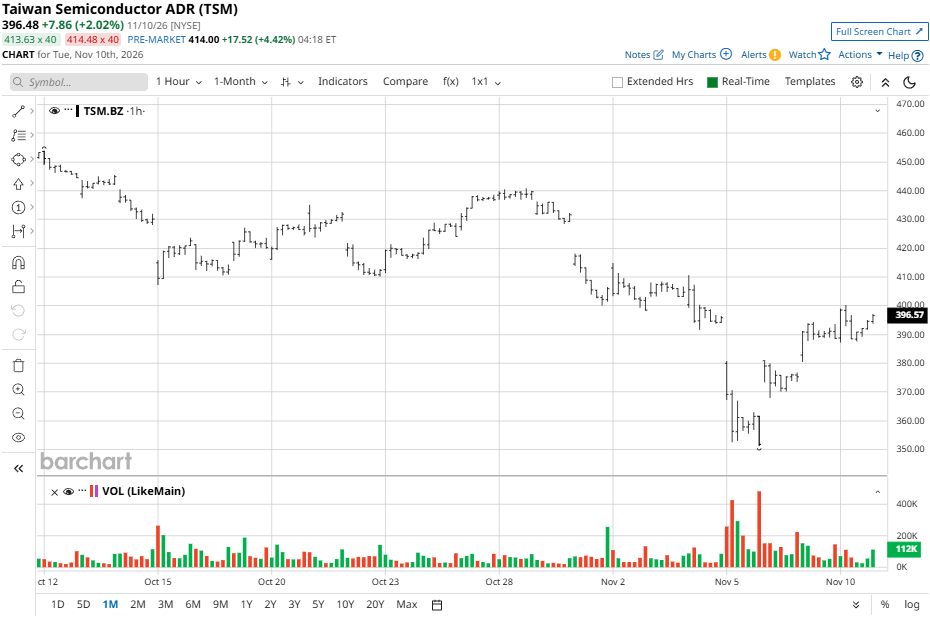
TSMC stock has delivered strong gains in 2026, supported by accelerating demand for artificial intelligence chips, advanced semiconductor manufacturing, and high-performance computing infrastructure. The company’s U.S.-listed American Depositary Receipts (ADRs) closed at approximately $396.48 on Nov. 10, giving the stock a year-to-date price gain of around 30.5% from its 2025 closing level. However, shares have experienced volatility, retreating from their 52-week high of approximately $487.47, as investors reassessed technology valuations and the sustainability of AI-related spending.
TSMC Quarterly Results
TSMC reported strong third-quarter 2026 financial results, driven by sustained demand for advanced semiconductor manufacturing and AI-related chips. Revenue reached NT$1.494 trillion (approximately $46.72 billion), increasing 50.9% year over year and exceeding the LSEG analyst estimate of approximately NT$1.46 trillion. Diluted earnings per share came in at NT$29.43, compared with the analyst consensus of NT$28.89, while net income climbed 68.7% year over year to NT$763.06 billion. The results reflected continued momentum across the global semiconductor industry, particularly in AI infrastructure and high-performance computing.
The company maintained strong profitability, with gross margin reaching 66.4%, operating margin at 58.7%, and net profit margin at 51.1%. Gross profit increased 68.6% year over year to NT$992.38 billion, while operating income rose 75% to NT$876.45 billion. Advanced technologies, including 2-nanometer, 3-nanometer, 5-nanometer, and 7-nanometer processes, accounted for 79% of total wafer revenue. Notably, 3-nanometer technology contributed 33%, while the newly ramping 2-nanometer process represented 8%.
Looking ahead, TSMC management expects strong demand for leading-edge process technologies to support its fourth-quarter 2026 performance, particularly as production of its 2-nanometer technology ramps up. The company forecasts fourth-quarter revenue between $52.3 billion and $54.3 billion, with gross margin projected at 65%-67% and operating margin at 56.5%-58.5%.
TSMC Revenue Jumps 60%
Taiwan Semiconductor Manufacturing reported a 59.7% year-over-year increase in October 2026 revenue to NT$586.89 billion ($18.4 billion), highlighting robust demand for advanced semiconductors used in artificial intelligence applications.
The world's largest contract chipmaker generated NT$4.49 trillion in revenue during the first 10 months of 2026, marking a 43.3% increase from the same period last year. Analysts expect revenue growth to accelerate to approximately 63% in the final quarter, following TSMC's September-quarter revenue of $46.72 billion, which exceeded the $45.7 billion analyst estimate.
TSMC shares listed in Taiwan rose 2.2% ahead of the revenue announcement. As a major supplier to Nvidia and Apple, TSMC remains well positioned to benefit from rising AI infrastructure investment and demand for advanced chip manufacturing.
Should You Buy TSM?
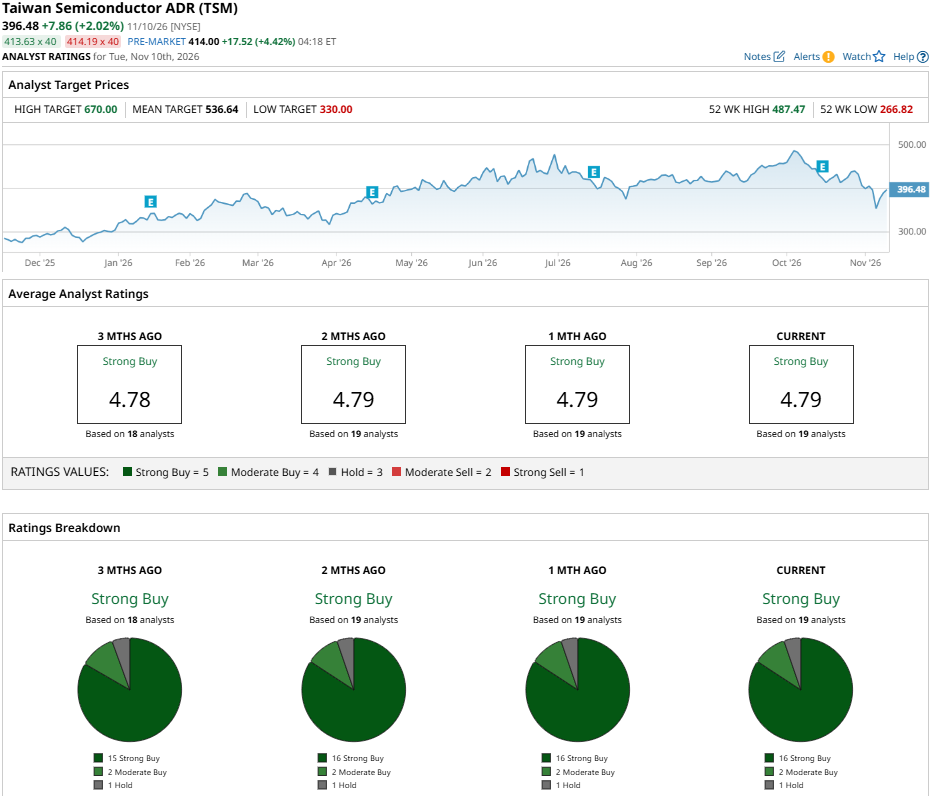
TSMC's October revenue surge of nearly 60% highlights strong demand for AI chips and reinforces its position as a leading semiconductor manufacturer. Continued investment in AI infrastructure could provide further growth opportunities, although market volatility and semiconductor industry risks remain important considerations. Wall Street maintains a “Strong Buy” consensus on TSM, with an average price target of $536.64, suggesting 35.5% potential upside from its current market price. Among 19 analyst ratings, 16 are "Strong Buy," two are “Moderate Buy,” and one is “Hold,” reflecting broadly positive sentiment toward TSMC's growth prospects.
On the date of publication, Ruchi Gupta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.