


Birmingham, Alabama-based Regions Financial Corporation (RF) is a financial holding company that provides banking and bank-related services to individual and corporate customers. With a market cap of $24.5 billion, the company provides consumer and commercial banking, wealth management, credit life insurance, leasing, commercial accounts receivable factoring, specialty mortgage financing, and securities brokerage services.
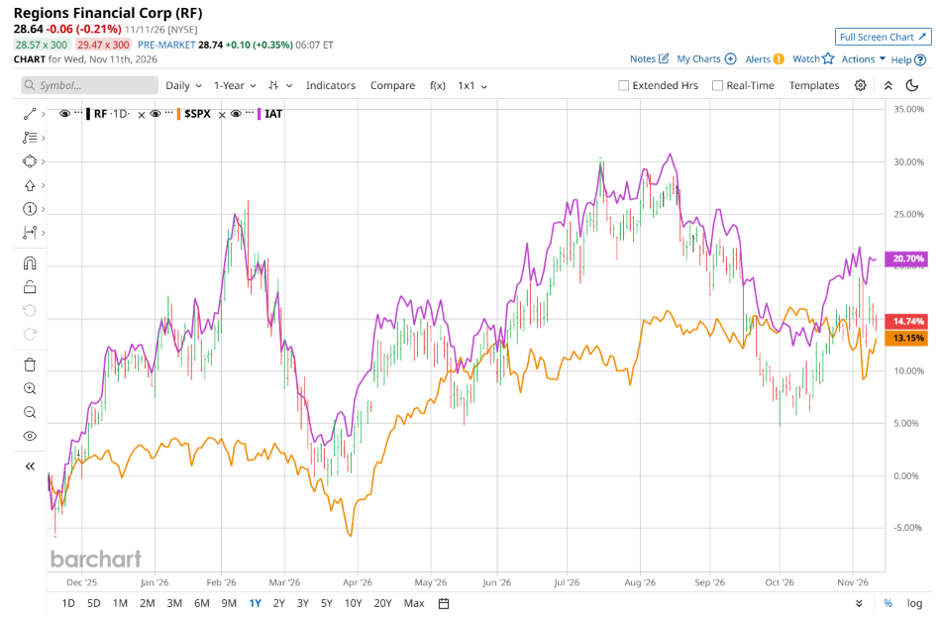
Shares of this leading banking and financial services provider have outperformed the broader market over the past year. RF has gained 14.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 11.3%. However, in 2026, RF stock is up 5.7%, compared to the SPX’s 11.3% rise on a YTD basis.
Narrowing the focus, RF’s underperformance is apparent compared to the iShares U.S. Regional Banks ETF (IAT). The exchange-traded fund has gained about 19.9% over the past year. Moreover, the ETF’s 9.9% gains on a YTD basis outshine the stock’s returns over the same time frame.
Regions Financial delivered a strong third quarter driven by commercial lending expansion, record capital markets and treasury fees, and disciplined risk management. CEO John Turner Jr. and CFO Anil D. Chadha highlighted robust C&I loan growth, a stable low-30% noninterest-bearing deposit mix, and improving credit metrics. Looking ahead, the bank expects continued momentum from structural asset repricing and milestone investments in cybersecurity and a new cloud-based deposit platform.
For the current fiscal year, ending in December, analysts expect RF’s EPS to grow 15.9% to $2.70 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 24 analysts covering RF stock, the consensus is a “Hold.” That’s based on five “Strong Buy” ratings, one “Moderate Buy,” 15 “Holds,” and three “Strong Sells.”
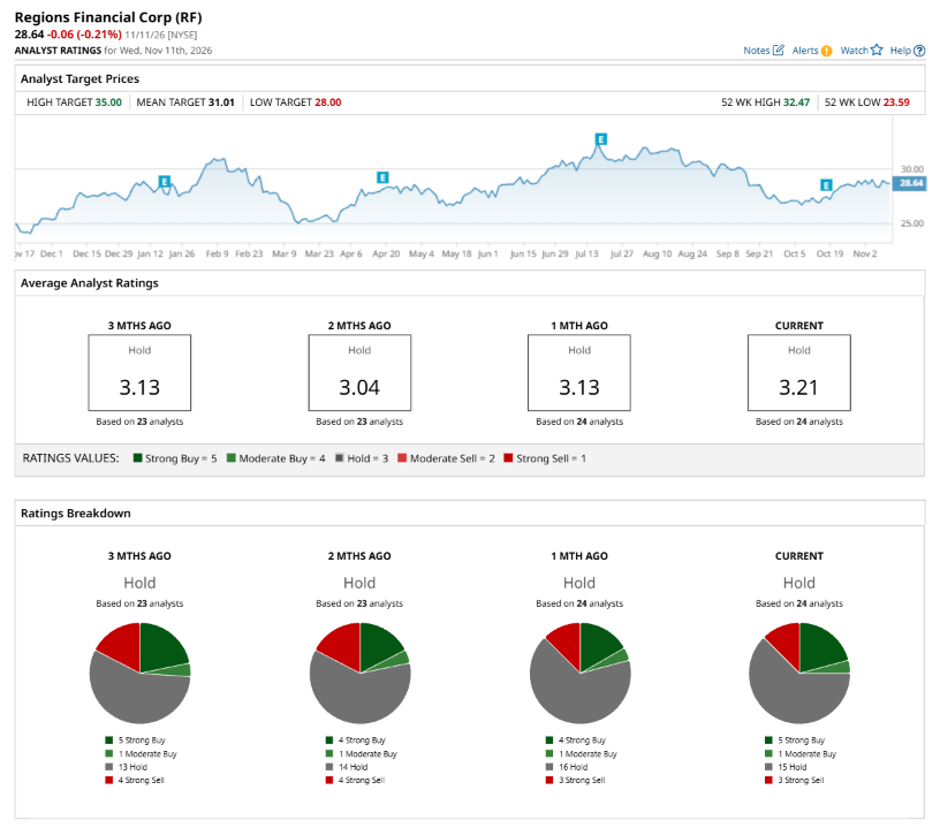
This configuration is more bullish than a month ago, with four analysts suggesting a “Strong Buy.”
On Nov. 10, Jason Goldberg from Barclays PLC (BCS) maintained a “Sell” rating on RF, with a price target of $30, implying a potential upside of 4.7% from current levels.
The mean price target of $31.01 represents an 8.3% premium to RF’s current price levels. The Street-high price target of $35 suggests a notable upside potential of 22.2%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.