


Kinetik Holdings has delivered a powerful run over the past few years, which puts the current US$53.71 share price under the spotlight and raises a straightforward question for you as an investor. Are buyers today paying a level that its earnings can reasonably support, or has the recent enthusiasm pulled the stock away from what the profit stream suggests?
- The share price has returned 88.0% over the past 3 years, which puts real pressure on the earnings profile to justify how far the valuation has already moved.
- Record processed gas volumes and approval of a major ECCC Pipeline expansion signal larger throughput potential, which can influence how investors think about future profitability and the durability of Kinetik Holdings' earnings base.
- The analysts covering Kinetik Holdings have run their own numbers. See what analysts think Kinetik Holdings's shares could be worth.
The issue now is whether Kinetik Holdings' current market price is in line with what its earnings suggest the stock should be worth.
If you want a wider context around Kinetik Holdings and its recent run, a focused stock screen can help you compare earnings power against price using 32 high quality undervalued stocks.
Is Kinetik Holdings Getting Expensive on Earnings?
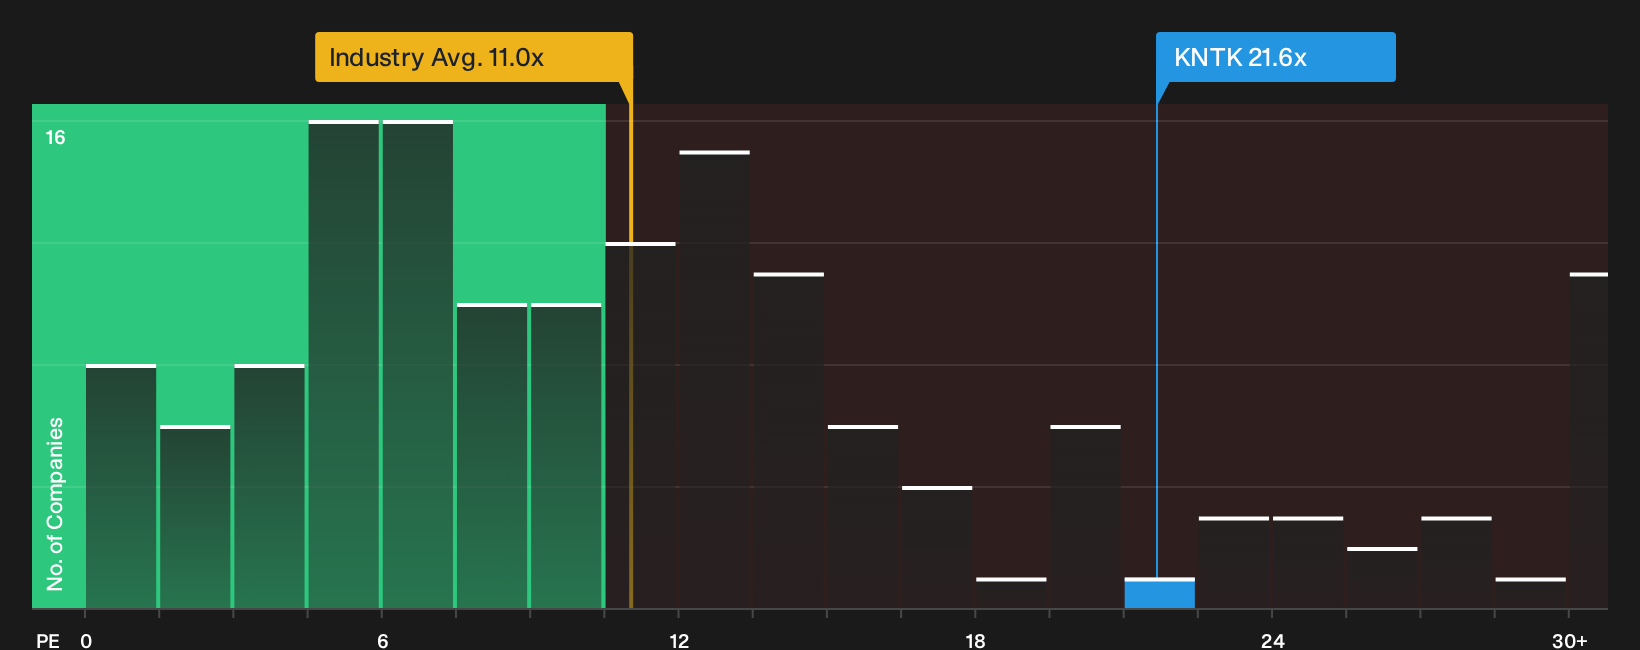
The P/E ratio fits Kinetik Holdings because investors in pipeline and processing businesses often anchor valuations to relatively steady earnings streams. At a current P/E of 21.6x, the stock trades well above the Oil and Gas industry average of 11.0x and also above the 14.3x average for its closest peers. As a result, the market is attaching a richer earnings tag to this ticker than to many comparable operators.
The fair multiple implied by a more tailored model, which weighs Kinetik Holdings' growth profile, profitability, size and risk, points to a lower P/E than where the shares change hands today, so on this yardstick the equity looks overvalued. Because the record gas volumes and ECCC Pipeline expansion decision have already reset expectations higher, the premium P/E leaves less room for further positive surprises to shift the earnings story meaningfully before the valuation needs to catch up. Explore the numbers behind Kinetik Holdings's P/E valuation.
The Kinetik Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Kinetik Holdings valuation question leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to look meaningfully richer or cheaper than today's price. They also frame each scenario as a thesis about how the business might perform that you can monitor over time, rather than a one off snapshot on Kinetik Holdings' Community page.
Optimists and skeptics are looking at the same Kinetik Holdings projects and drawing very different conclusions about how much is already reflected in the shares.
Bull case: 9% undervalued
The analyst consensus Narrative on Simply Wall St highlights how Kinetik Holdings could build a larger, steadier earnings base over time.
"Reworked gas processing contracts, including amendments that extend legacy Durango volumes into the mid to late 2030s, expand dedicated acreage by about 25% for at least one large customer…"
Discover why this Narrative puts Kinetik Holdings at 9% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St leans on heavy spending and funding risk to argue upside may be limited.
"Kinetik’s steady plan to reinvest US$500 million to US$600 million each year into new cryogenic plants, pipeline expansions and long lead equipment supports future processing capacity, but the persistent secondary share sales by a large shareholder highlight a risk that equity funding pressure and dilution could offset any eventual EBITDA gains…"
Explore why this Narrative puts Kinetik Holdings at roughly fairly valued.
One more piece to weigh on Kinetik Holdings before you decide
Current earnings and today's P/E only tell part of the story for Kinetik Holdings. Analyst projections for revenue, profits and cash flows a few years from now provide a different reference point that you can compare with today's price. Explore where analysts expect Kinetik Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com