


- Sonos reported Q4 2026 sales of US$344.44 million and a quarterly net loss of US$5.16 million, while full year revenue reached US$1.55 billion with net income of US$89.6 million.
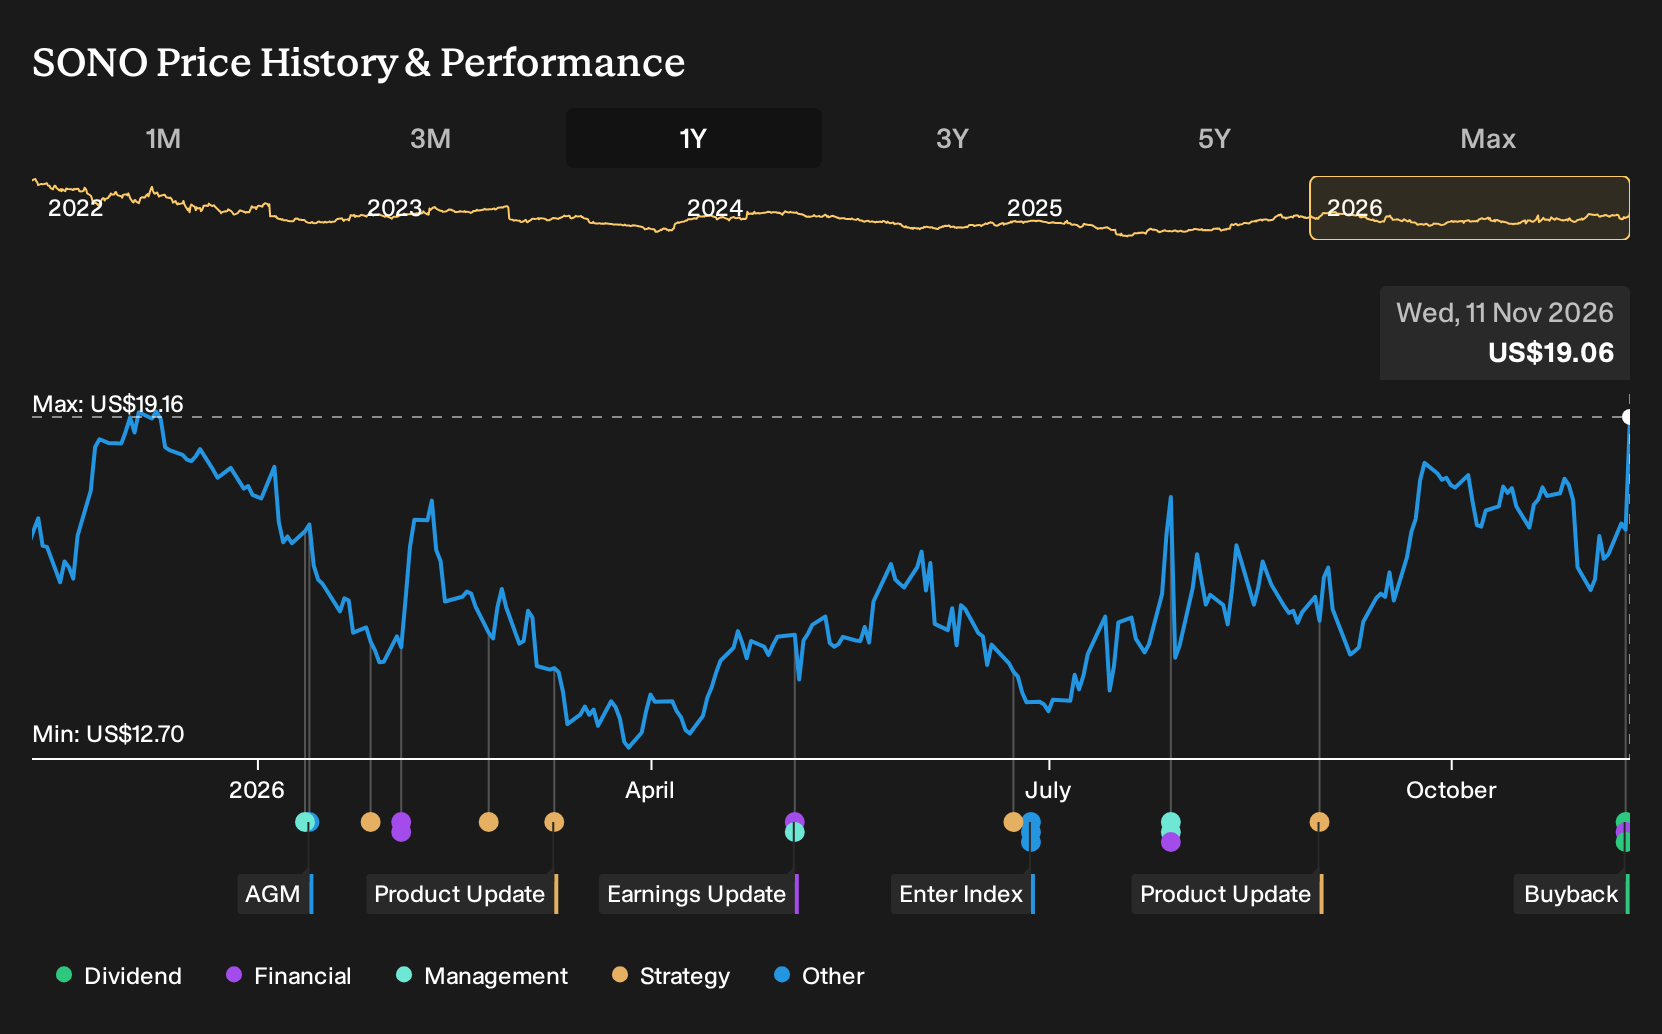
- The Board completed a previous US$150 million repurchase covering 8.12% of shares and, on the same day, approved a new US$150 million buyback funded from existing and future cash.
- We will now look at how Sonos's return to full year profitability and the fresh US$150 million buyback affect its investment narrative.
Compare Sonos' profitability rebound and fresh buyback with other companies showing similar turning points by using our hand picked 19 high quality undiscovered gems for ideas beyond this ticker.
Sonos Investment Narrative Recap
To own Sonos, an investor needs to believe the audio ecosystem can convert its 53 million connected devices and 17 million homes into higher spend per household, helped by Sonos 27 and new hardware. The return to full year profitability in 2026 supports that belief, although higher memory and component costs are still keeping a lid on gross margins.
The analyst consensus narrative on Simply Wall St points to margin improvement as a key short term catalyst. However, management expects FY27 non GAAP gross margin to be around the lower end of Q4 guidance near 40%. Prolonged elevated memory pricing remains the biggest operational risk, as it can constrain both earnings and product investment.
The fresh US$150 million buyback authorization is the standout new announcement alongside the earnings release. It follows completion of a prior US$150 million program that retired 8.12% of shares, and is planned to be funded from existing cash and future cash flow, with no expiration date on the authorization.
For you, the relevance is mostly about how this interacts with execution on the core plan. If Sonos manages through memory cost pressure and turns its cost cuts and product launches into steadier earnings, repurchases can reduce the share count alongside that progress. If margins stay under pressure for longer, the repurchase program may matter less than how quickly the business model adjusts.
Sonos' current analyst story points to revenues of US$1.9b and earnings of US$108.6 million by 2029, built on 7.5% yearly revenue growth and an earnings increase of about US$51.7 million from the US$56.9 million reported today.
Uncover why Sonos' fair value indicates that the valuation picture is roughly in line with its current price.
Exploring Other Perspectives
One alternate view on Sonos leans heavily on the fresh buyback. The most optimistic analysts were already pencilling in around US$1.9b of revenue and roughly US$154.7 million of earnings by 2029. That is a far more upbeat story than consensus, and this new profitability rebound and repurchase plan may eventually lead to those projections being revisited.
Explore 4 other Sonos fair value estimates, including one that suggests as much as 10% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Sonos research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sonos. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sonos' overall financial health at a glance.
Looking for more investment ideas beyond Sonos?
Once you have a view on Sonos, it can help to compare that thesis with other opportunities that share similar traits, whether you care most about value, resilience, or income.
- For investors who want quality businesses that look priced for potential mispricing, check out our curated 32 high quality undervalued stocks to see where the numbers and fundamentals align most convincingly.
- If balance sheet strength matters to you, scan our list of solid balance sheet and fundamentals (23 results) to find companies that pair financial resilience with underlying business fundamentals.
- For those who prioritise cash returns, use the income focused 6 dividend fortresses to spot higher yielding stocks that may warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com