


J. M. Smucker (SJM) has drawn fresh attention after recent share price moves, with the stock last closing at US$133.07. Investors are weighing that level against the consumer staples group’s mixed performance across coffee, pet food and snacks.
Recent trading has come after a strong run, with a roughly 10.9% 1 month share price return and about 10.3% over 3 months, while the share price return year to date sits near 37.7% and the 1 year total shareholder return is about 26.2%. This signals momentum that investors appear to be linking to expectations for J. M. Smucker’s earnings power and risk profile rather than short term headlines alone.
Scan how J. M. Smucker’s momentum compares with a hand picked group of consumer defensives that show strong fundamentals in the list of solid balance sheet and fundamentals (23 results).
After that sharp rerating, J. M. Smucker now trades only modestly below the average analyst target, while internal fair value work implies a far steeper discount. Which reference point really anchors the valuation story from here?
Most Popular Narrative: 6% Undervalued
On the Simply Wall St analyst consensus Narrative, J. M. Smucker screens as modestly undervalued, with a fair value of about $142 against the recent $133.07 close and a 7.2% discount rate anchoring that view. The framework leans heavily on how branded platforms like Uncrustables, Café Bustelo and Meow Mix convert into cash flow while the Hostess integration is worked through.
• The main factor that has to go right is that J. M. Smucker converts momentum in core growth brands and ongoing cost discipline into sustained free cash flow around the current US$1.1 billion level while it continues to deleverage and manage the Hostess turnaround.
See why 17 investors see J. M. Smucker as 6% undervalued.
Result: Fair Value of $142 (UNDERVALUED)
Still, the narrative can unravel if FY27 net sales fall 1% to 2% as guided and the Sweet Baked Snacks recovery for J. M. Smucker stays slow.
Find out about the key risks to this J. M. Smucker narrative.
Another View: What J. M. Smucker’s P/E Is Telling You
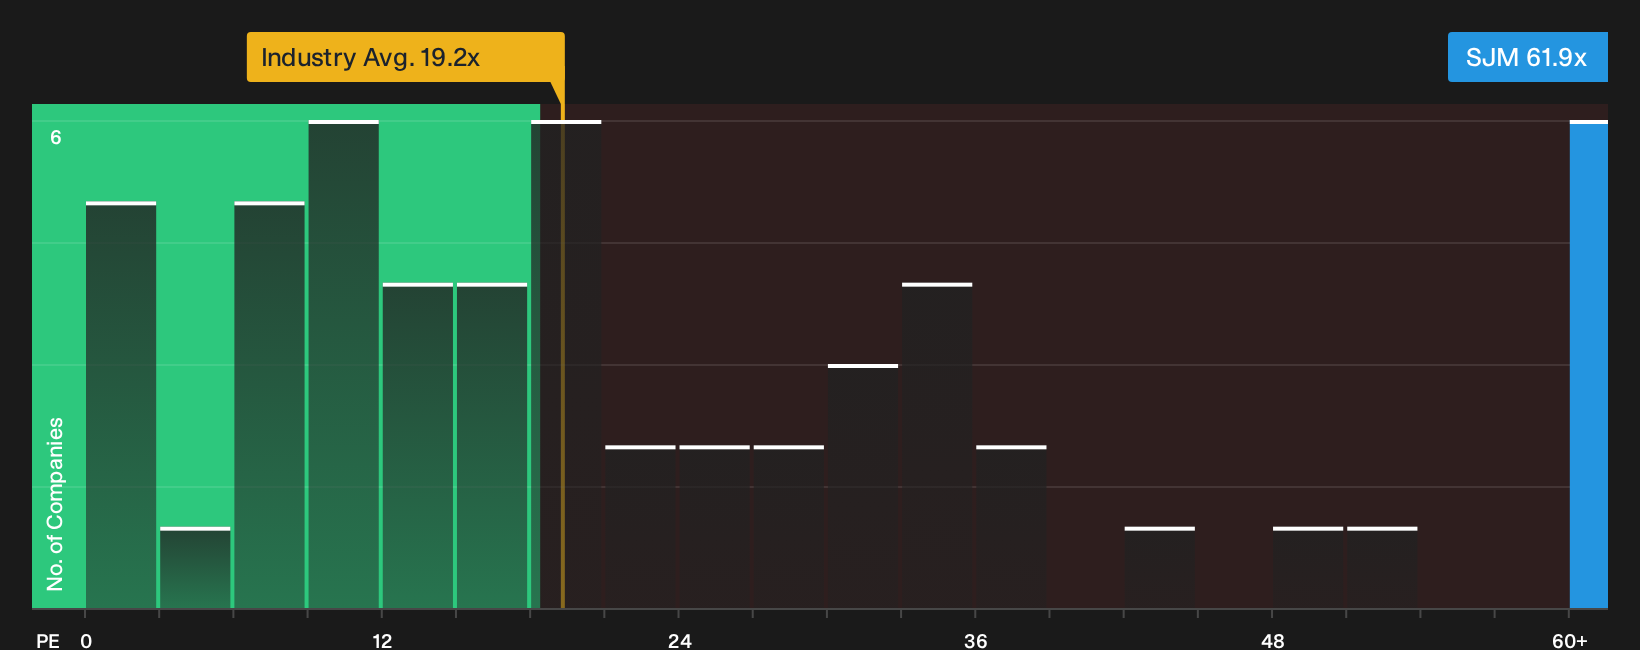
The SWS DCF model points to upside, yet the plain P/E picture looks very different. J. M. Smucker trades on about 61.9x earnings, compared with roughly 19.1x for the US Food sector and a fair ratio estimate of 26.1x. That gap signals meaningful valuation risk if sentiment shifts away from premium pricing.
To see how this earnings multiple stacks up against both industry peers and the fair ratio the market could move toward, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed sentiment on J. M. Smucker leaves you on the fence, move fast, review the data for yourself, and weigh both sides of the story. To help frame that view with a balanced checklist of what looks promising and what could go wrong, start with these 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond J. M. Smucker?
If J. M. Smucker has you reassessing your watchlist, you can use this momentum to widen your search and uncover other opportunities that match your risk and income goals.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results), which can help anchor a portfolio when sentiment shifts.
- Look for quality at a measured price by reviewing the 32 high quality undervalued stocks, sourced from companies that pair fundamental strength with potentially appealing valuations.
- Focus on your income stream and reduce guesswork around payout reliability by checking the 6 dividend fortresses, which highlights higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com