


- Reinsurance Group of America reported Q3 2026 revenue of US$7,550 million and net income of US$456 million, with diluted EPS from continuing operations at US$6.92. For the first nine months, the company reported revenue of US$20,681 million and net income of US$1,248 million.
- The firm also completed a share repurchase of 765,739 shares for US$174.84 million under its February 2026 authorization, which reduces the share count and concentrates future earnings across a smaller equity base.
- We will now look at how Reinsurance Group of America’s quarterly earnings performance could influence the existing long-term investment narrative.
Scan beyond Reinsurance Group of America and compare its earnings and capital return story with a curated 32 high quality undervalued stocks that also pair strong cash generation with disciplined balance sheets.
Reinsurance Group of America Investment Narrative Recap
To own Reinsurance Group of America, you need to be comfortable with a life and health reinsurer that leans heavily on biometric risk expertise, digital underwriting and global partnerships, as set out in the analyst consensus Narrative on Simply Wall St. The latest quarter showed strong underwriting, investment income and favorable claims, which supports that story. The near term operational swing factor remains execution on exclusive, higher margin reinsurance deals and efficient use of excess capital.
The main business risk right now is that weaker pension risk transfer activity in the U.S. and U.K. persists, which could restrain premium growth and make those earnings goals harder to reach. A further risk is any step back in mortality experience or pricing discipline that erodes margins just as the company is investing in new product launches, risk analytics and third party capital platforms.
The recent completion of the US$174.84 million buyback of 765,739 shares is the clearest link between the earnings story and capital management. Lower share count concentrates any future earnings across fewer shares, so execution on underwriting and fee income now flows through more directly to per share metrics. That matters when analysts are watching earnings growth, returns and payout ratios together.
This repurchase also interacts with the catalysts laid out in the analyst consensus Narrative on Simply Wall St, which highlights excess capital, in force transactions and debt paydown as key tools. Committing funds to buybacks reduces flexibility if pension risk transfer volumes stay soft or if attractive Asia Pacific or biometric focused deals require significant capital. The trade off between returning cash and funding new reinsurance opportunities remains an ongoing operational balancing act for Reinsurance Group of America.
Reinsurance Group of America's narrative projects US$31.2b revenue and US$2.2b earnings by 2029, based on an assumed annual revenue growth rate of 4.6% and an implied earnings increase of about US$500m from US$1.7b today.
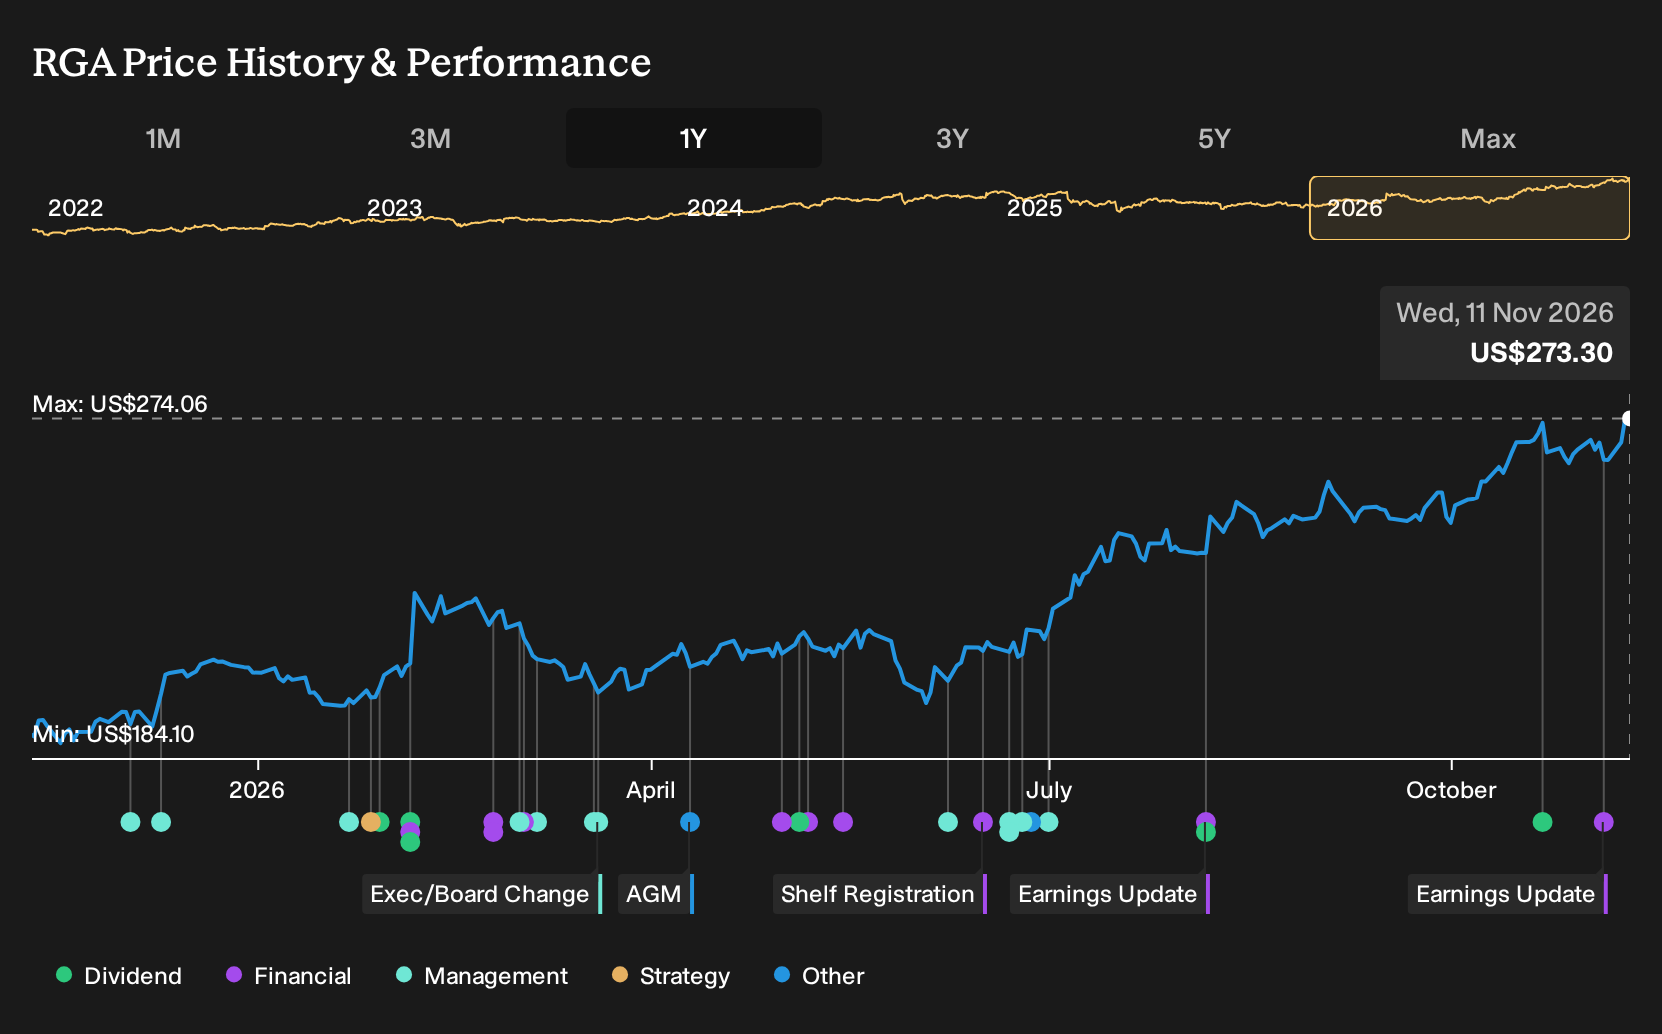
Uncover why Reinsurance Group of America's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts pension risk transfer exposure at the center of the Reinsurance Group of America debate. The most cautious analysts, who were only looking for about US$30.8b of revenue and US$2.0b of earnings by 2029, see soft U.S. and U.K. pension markets as a real brake. Your own take might shift after this latest earnings and buyback update, so treat these pre news forecasts as a starting point and compare a few different narratives.
Explore 3 other Reinsurance Group of America fair value estimates, including one that suggests it could be worth just $283.67.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Reinsurance Group of America research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Reinsurance Group of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Reinsurance Group of America's overall financial health at a glance.
Looking For More Investment Ideas Beyond Reinsurance Group of America?
If this earnings and capital return story has sharpened your view on Reinsurance Group of America, use that same lens to scan other businesses with cash flows, balance sheets and return policies that fit your style.
- If you want potential mispricings paired with solid fundamentals, start by reviewing a curated 32 high quality undervalued stocks that already clear basic quality and balance sheet checks.
- Income focused investors can zero in on payouts by screening for companies that look more like steady cash dispensers through a targeted 6 dividend fortresses with elevated yields.
- If risk control matters most, narrow your list to financially resilient businesses using a 30 resilient stocks with low risk scores that filters out weaker balance sheets and fragile earnings profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com