


Northwest Natural Holding (NWN) released its third quarter earnings and raised its full year EPS outlook, after reporting nine month sales of US$911.93 million and net income of US$68.25 million.
The earnings update landed against a backdrop of steady gains for Northwest Natural Holding, with the share price up 6.95% over the past month and 10.89% year to date. The 1 year total shareholder return of 12.06% and 3 year total shareholder return of 58.91% point to momentum that has been building rather than fading.
Scan for other regulated utilities that show similar earnings momentum and regulatory support to Northwest Natural Holding by reviewing our curated list of 30 resilient stocks with low risk scores.
After that run and a higher earnings bar, Northwest Natural Holding now looks less like a recovery story and more like a fully priced utility. The key question for investors is whether the current valuation still leaves enough upside to justify taking on new risk.
Most Popular Narrative: 9.7% Undervalued
Against a last close of $51.83, the analyst consensus Narrative on Simply Wall St sets Northwest Natural Holding's fair value at $57.40 and frames the stock as modestly undervalued. That view leans heavily on contracted projects, regulatory tools and utility style earnings visibility, priced using a 7.24% discount rate.
Analysts expect Northwest Natural Holding to translate its Texas utility platform, long-term contracted gas storage project and growing water operations into steady EPS growth and a more predictable earnings mix through 2030.
The main conditions that need to be met include continued execution on high-growth Texas customer additions, regulatory outcomes that support multiyear frameworks across key jurisdictions, and timely progress on the MX3 storage expansion and water platform integration.
See why 7 investors see Northwest Natural Holding as 10% undervalued.
Result: Fair Value of $57.40 (UNDERVALUED)
Still, the Northwest Natural Holding story could look very different if decarbonization policies accelerate or if higher operating and financing costs squeeze future earnings power.
Find out about the key risks to this Northwest Natural Holding narrative.
Another View: What Multiples Say About Northwest Natural Holding
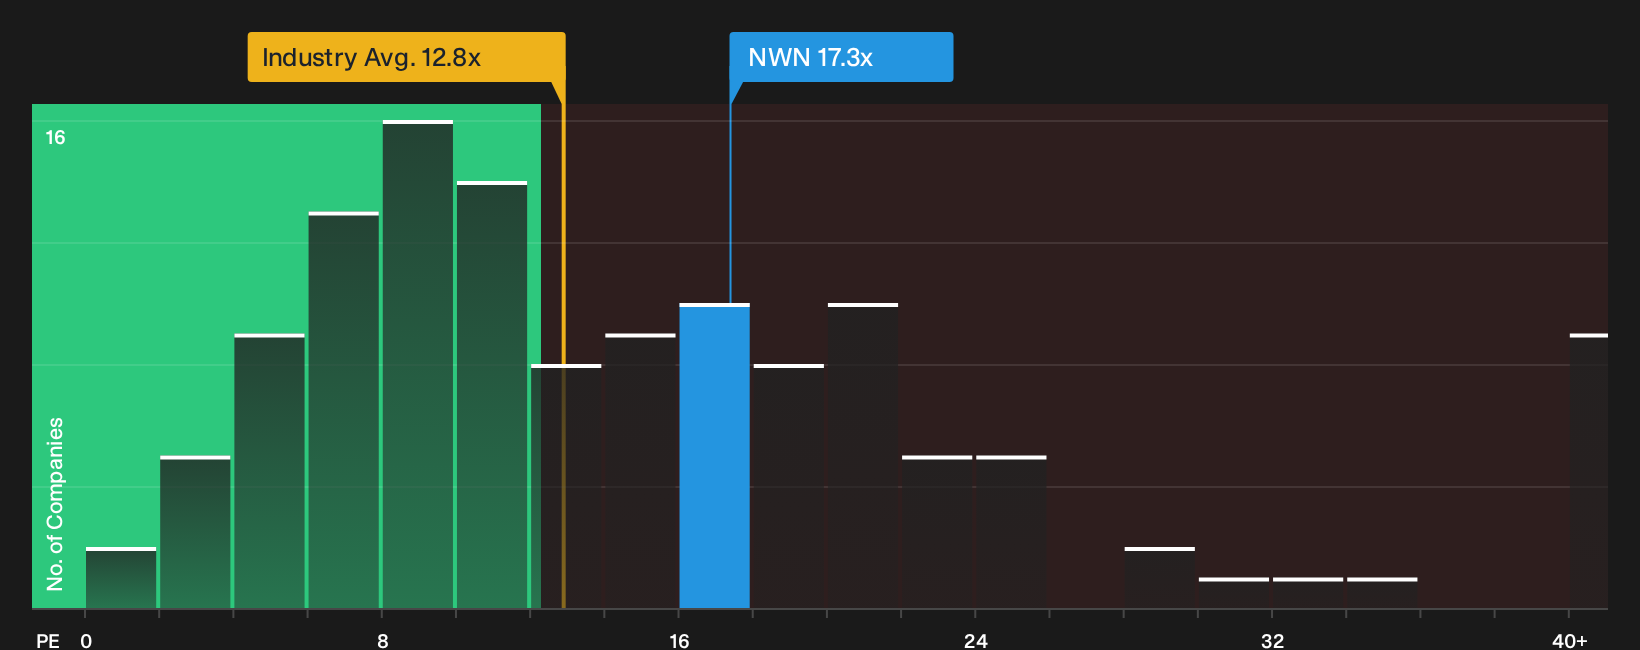
The story shifts when you look at simple valuation ratios. Northwest Natural Holding trades on a P/E of 17.3x, above the global gas utilities average of 12.5x and in line with its own fair ratio of 17.3x. That points to a stock already priced for its current earnings profile, so where is the extra cushion if things do not go to plan?
To see how that pricing stacks up against peers in more detail, take a look at the valuation breakdown, including our fair ratio workup, in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed tone on Northwest Natural Holding leaves you unsure, treat that as a prompt to move quickly and stress test the story yourself using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Northwest Natural Holding?
If Northwest Natural Holding is now on your radar, do not stop there. Use this moment to widen your opportunity set with a few focused screeners that highlight different strengths across the market.
- Target income resilience by zeroing in on companies that resemble dividend fortresses using the 6 dividend fortresses.
- Hunt for mispriced quality and see which businesses combine solid fundamentals with attractive entry points through the 32 high quality undervalued stocks.
- Prioritize financial strength and filter for companies with robust balance sheets and fundamentals with the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com