


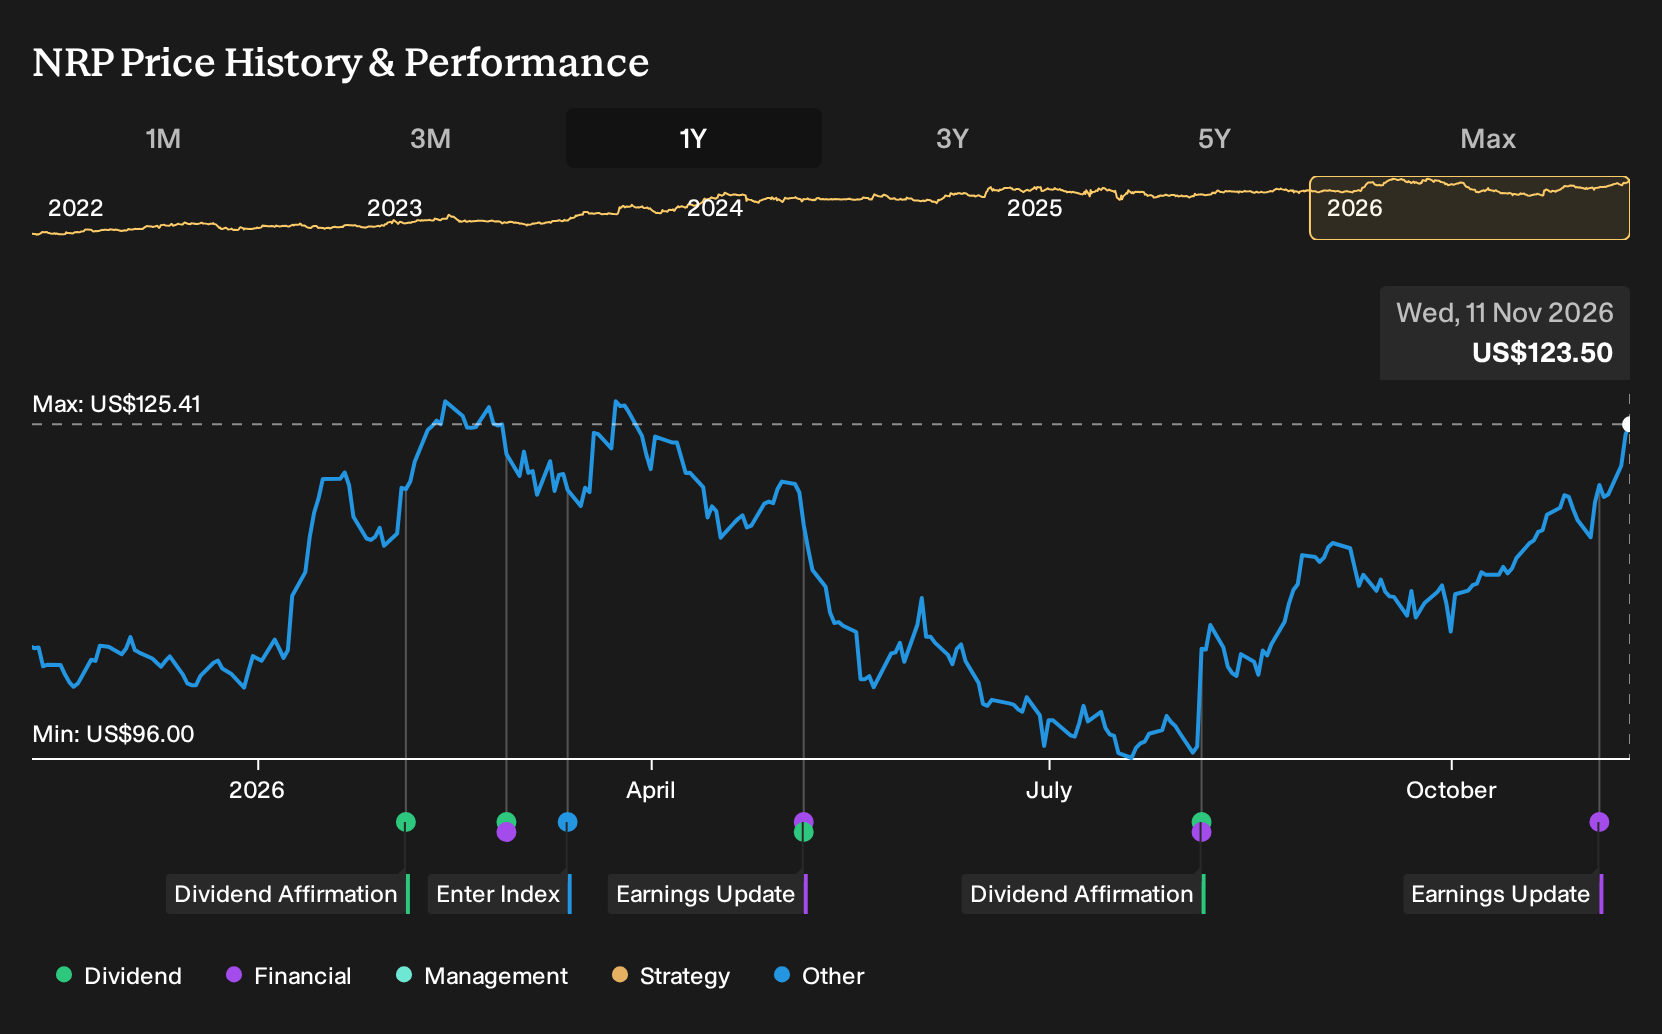
- Natural Resource Partners reported third quarter 2026 revenue of US$44.82 million and net income of US$26.01 million, with both figures lower than the same period in 2025 alongside reduced basic and diluted earnings per share from continuing operations.
- For the first nine months of 2026, Natural Resource Partners showed materially lower revenue and net income versus the prior year, which points to pressure on its royalty and leasing model and raises questions about how management balances cash generation with long term asset stewardship.
- Next, the focus shifts to how Natural Resource Partners' softer earnings profile shapes the investment narrative and what lower year to date profitability might signal.
What Is Natural Resource Partners' Investment Narrative?
To own Natural Resource Partners, you need to be comfortable with a royalty and leasing story where most of the action happens in coal, industrial minerals, and soda ash, not in big new projects. The appeal is a relatively asset light model that converts resource access into cash, while relying on counterparties to spend the heavy capital. The latest quarter breaks that spell a bit. Softer revenue and net income, plus lower earnings per unit for both the quarter and the first nine months of 2026, underline that pricing and volume on those underlying resources really matter for this structure.
The key short term swing factors now look very operational. Production and pricing trends at lessees, contract terms, and how quickly management adjusts costs and capital allocation take center stage. Earnings have already trended lower over the past year and over five years, and the fresh results reinforce that pattern rather than easing it. At the same time, Natural Resource Partners still screens as good value on some metrics, including P/E against peers and a large gap to one estimate of future cash flow value. That mix of pressure on profitability and potential valuation upside is exactly what investors will be weighing after this report.
Even so, there is a structural wrinkle in Natural Resource Partners' setup that could matter a lot more than this single quarter...
There's only one way to know the right time to buy, sell or hold Natural Resource Partners. Head to Simply Wall St's company report for the latest analysis of Natural Resource Partners's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Natural Resource Partners research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Natural Resource Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Natural Resource Partners' overall financial health at a glance.
Looking for more Natural Resource Partners investment ideas?
If Natural Resource Partners' latest update has you rethinking your watchlist, it can help to line it up against other businesses with different risk and income profiles. The Simply Wall St Screener lets you quickly scan groups of companies that fit a specific angle, then dig into the details that matter most to you.
- If capital preservation is near the top of your list, start with sturdier balance sheets and lower risk scores by checking out 30 resilient stocks with low risk scores.
- If income is the priority, target businesses built around stronger payouts and yields through the lens of 6 dividend fortresses.
- If you want to cast a wider net for underfollowed opportunities with solid fundamentals, the 19 high quality undiscovered gems is a useful way to surface ideas you may not have considered yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com