


- ON Semiconductor introduced its fourth generation EliteSiC M4 silicon carbide platform, targeting AI data centers, electric vehicles and energy infrastructure with higher power density and lower losses, while also issuing fourth quarter 2026 revenue guidance of US$1.715b to US$1.815b.
- The EliteSiC M4 launch arrives alongside recent quarterly results that report higher sales and net income year over year. This highlights how onsemi is coupling product execution with current earnings delivery rather than only future expectations.
- Next, the focus moves to how ON Semiconductor's broader investment narrative could be reshaped by the EliteSiC M4 platform efficiency gains.
What Is ON Semiconductor's Investment Narrative?
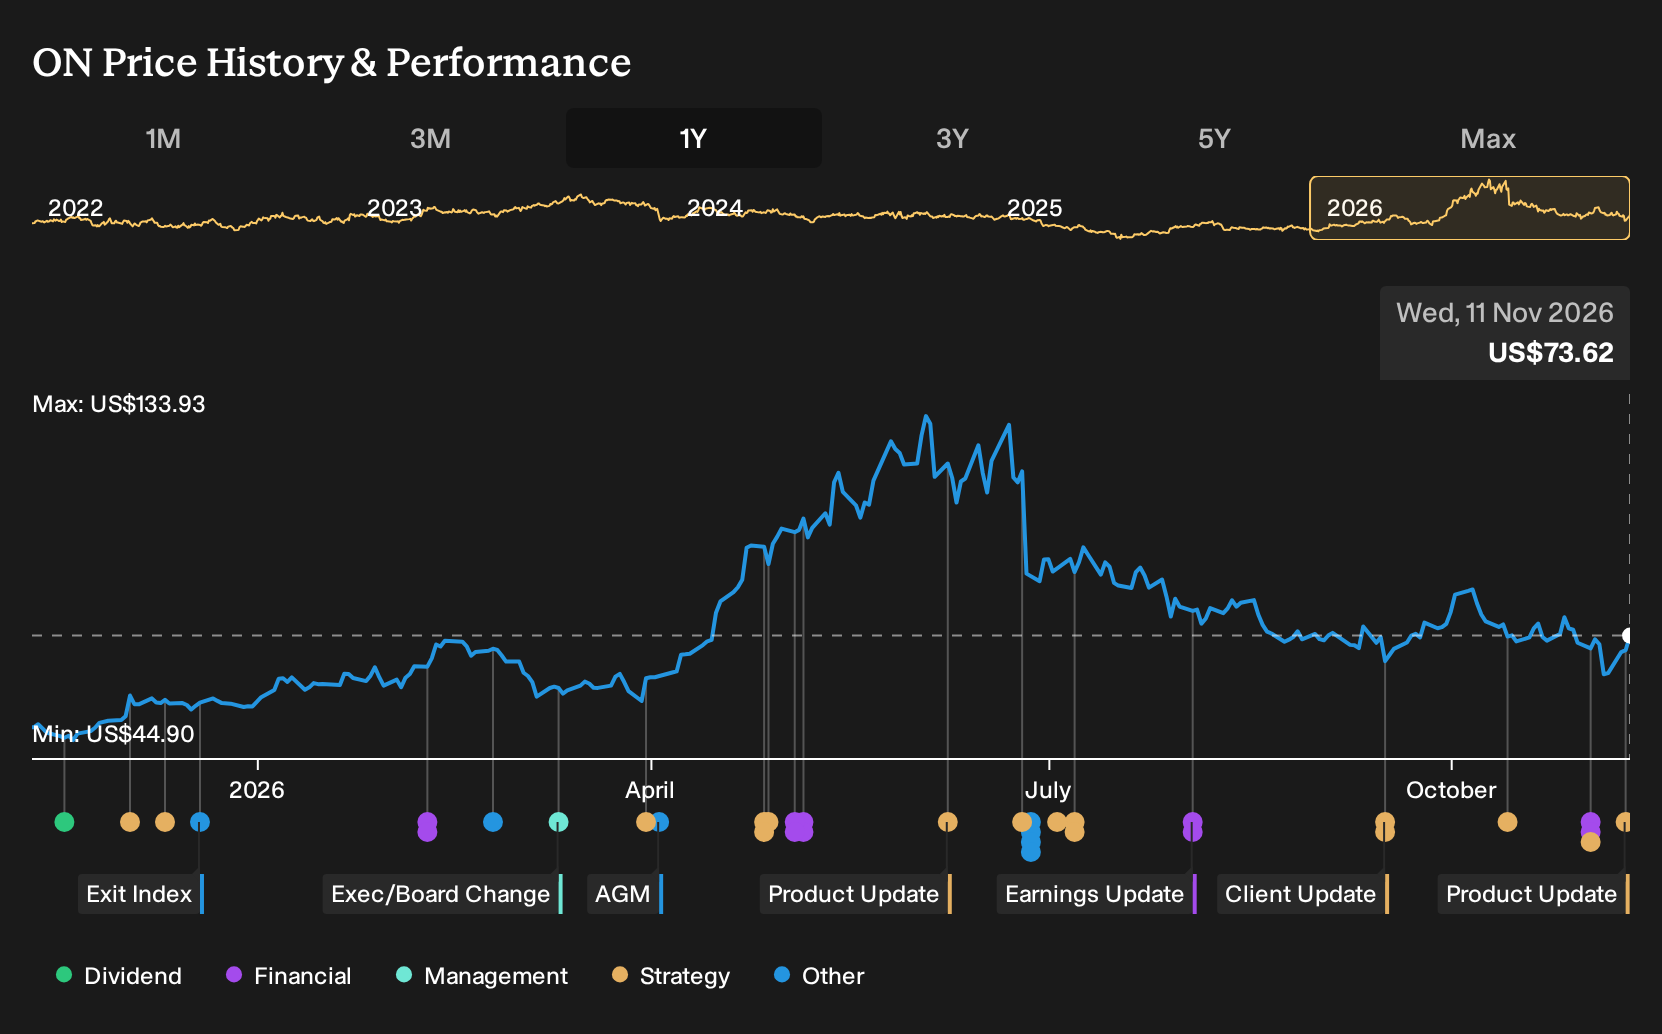
For ON Semiconductor, the core belief is that its power and sensing portfolio can stay central as AI data centers, EV powertrains and high voltage energy systems demand more efficient silicon carbide. The EliteSiC M4 launch fits this view directly, since it is aimed at those exact end markets and links product execution to current earnings, not only long term promises. Recent quarterly results with higher sales and net income, and Q4 2026 revenue guidance in the US$1.715b to US$1.815b range, indicate that operations are scaled to support that thesis, although silicon carbide remains capital intensive and technically complex.
In the short term, the key swing factors appear to be demand durability in EV and AI infrastructure, pricing power in silicon carbide, and ON Semiconductor's ability to ramp new voltage classes without quality issues or cost overruns. EliteSiC M4 could strengthen the near term narrative if customers standardize on the platform, yet it also concentrates more of the future on one technology path. Earnings quality flags such as large one off items, significant recent insider selling and a relatively full P/E against fair value estimates keep execution risk in focus even with strong recent profit growth.
The part that can materially change how you think about ON Semiconductor becomes clearer when you consider ...
There's only one way to know the right time to buy, sell or hold ON Semiconductor. Head to Simply Wall St's company report for the latest analysis of ON Semiconductor's Fair Value.
Exploring Other Perspectives
One alternate angle on ON Semiconductor leans heavily on revenue optimism. The most bullish analysts were modeling annual top line expansion of 16.9% for the next 3 years and earnings reaching about US$3.0b by 2029, well above today’s US$689.1m base. Those projections did not yet factor in the EliteSiC M4 launch, so this new platform could prompt those optimistic narratives to evolve further. You do not need to agree with that view. However, it is worth comparing it with more cautious scenarios and deciding where you sit on that spectrum.
Explore 5 other ON Semiconductor fair value estimates, including one that suggests there could be up to 80% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ON Semiconductor research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ON Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ON Semiconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond ON Semiconductor?
Once you have formed a view on ON Semiconductor, it can help to widen the lens and compare it with other businesses that share some of the qualities you care about. The Simply Wall St Screener is built for exactly that kind of side by side research, so you can stress test your thesis and spot fresh ideas that fit your style.
- If you care most about pricing power and durable profitability, focus on companies with strong cash flows and solid balance sheets using the list of solid balance sheet and fundamentals (23 results).
- For readers hunting for mispriced quality, weigh ON Semiconductor against a 32 high quality undervalued stocks that combine financial strength with what may be attractive entry points.
- If capital preservation matters more than anything, narrow your watchlist to a 30 resilient stocks with low risk scores that score well on resilience and lower overall risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com