


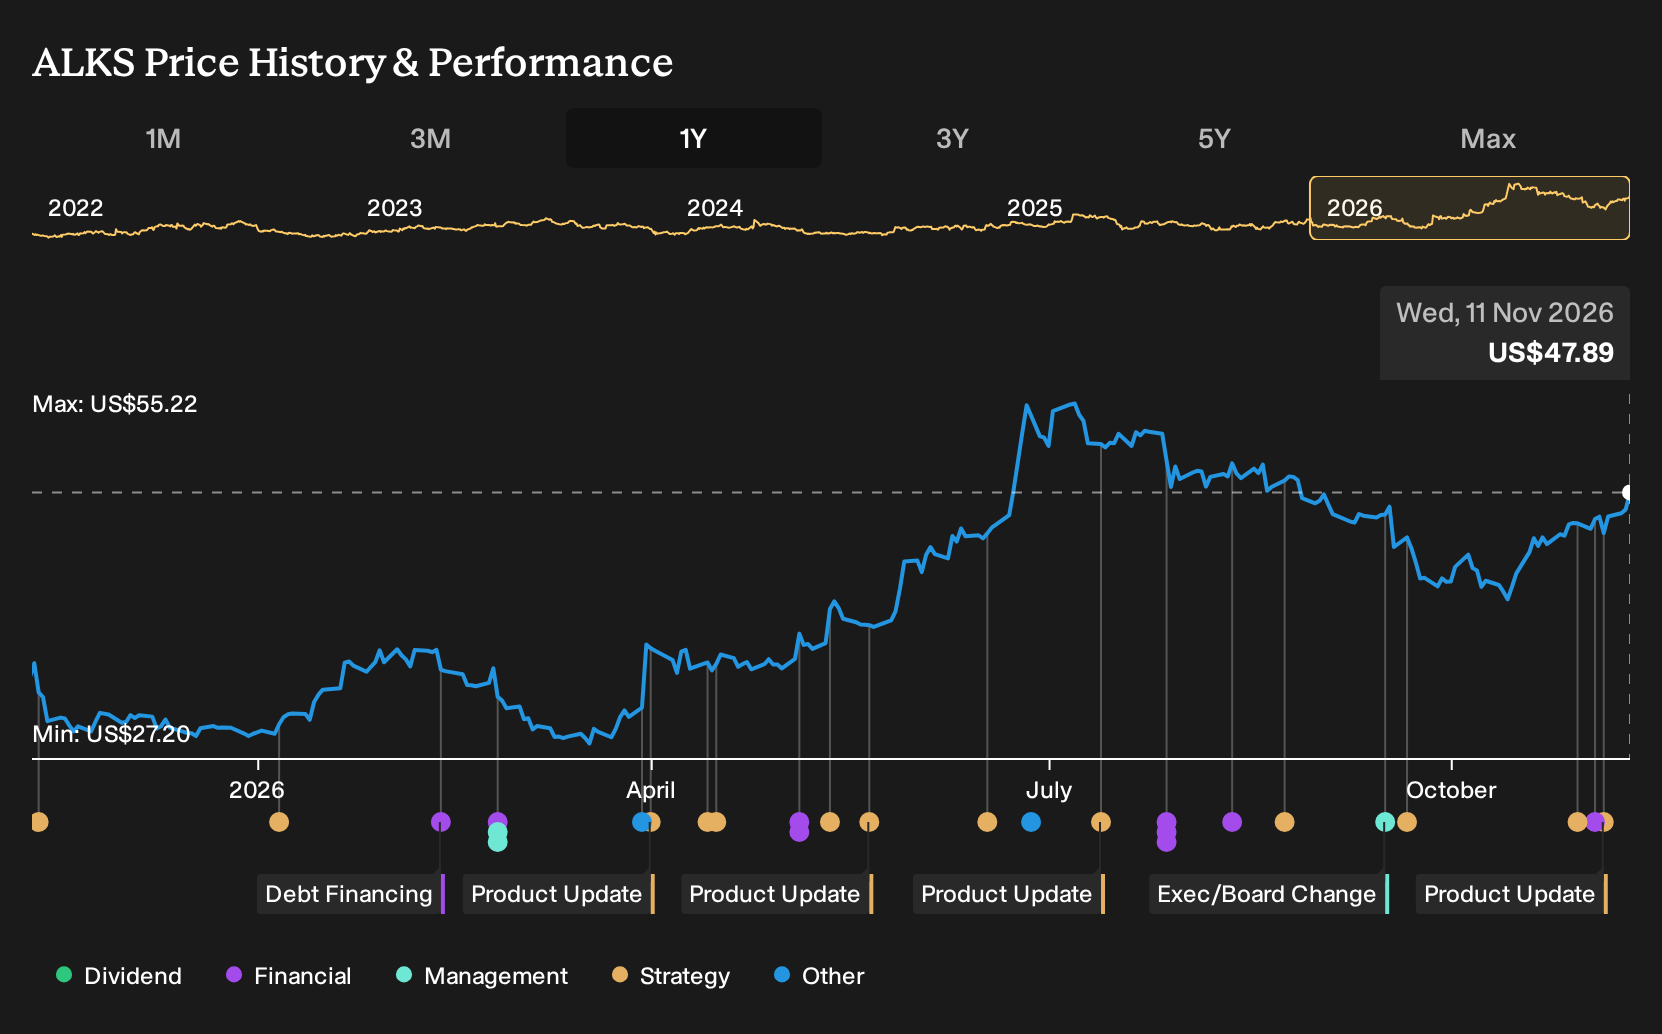
- Alkermes reported third quarter 2026 revenue of US$480.13 million and net income of US$16.29 million, alongside extensive psychiatry and sleep medicine data presentations and new orexin 2 receptor programs such as ALKS 7290 and alixorexton across major scientific meetings.
- The combination of broad real world evidence for LYBALVI and ARISTADA, LUMRYZ expansion work, and orexin agonist progress in narcolepsy, idiopathic hypersomnia and mood disorders indicates that Alkermes is leaning heavily on central nervous system franchises to support its future operating profile.
- The next section examines how Alkermes' expanded orexin 2 receptor clinical program could shape the investment narrative around its R&D spending.
Alkermes Investment Narrative Recap
Owning Alkermes means believing the psychiatry and sleep franchise can support heavy orexin investment while the company works through a guided GAAP net loss of US$95 million to US$115 million in 2026. The analyst consensus Narrative on Simply Wall St hinges on R&D translating into approvals and commercial use rather than simply higher costs.
The latest quarter showed revenue of US$480.13 million and net income of US$16.29 million, which sits against that full year loss guidance. Expanded data presentations and conferences do not meaningfully change the near term picture. The key short term swing factor remains orexin trial readouts, with trial failures and sustained high expenses as the biggest threat.
The recent initiation of the phase 2 ALKS 7290 study in major depressive disorder feels most relevant to this orexin heavy story. That trial adds another meaningful program on top of ongoing ADHD work, reinforcing the focus on orexin 2 agonism as a potential second pillar alongside LYBALVI, ARISTADA, VIVITROL and LUMRYZ.
For you as an investor, this adds another clinical catalyst plus another cost line. Success in ALKS 7290, together with the alixorexton narcolepsy and idiopathic hypersomnia programs discussed at recent congresses, could support the multi indication vision described in the analyst consensus Narrative on Simply Wall St. Disappointing data would push that out and leave the higher R&D burden more exposed.
Alkermes' current earnings sit at about US$66.1 million, with analyst models pointing to US$2.3b in revenue and US$363.0 million in earnings by 2029. That profile lines up with a 10.6% yearly revenue growth rate and requires roughly a 5.5x increase in earnings from today's base to reach the 2029 consensus target.
Uncover why Alkermes' fair value indicates an 18% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You see Alkermes leaning hard into orexin as a growth story, yet the lowest analysts frame execution risk very differently. They focus on earnings staying subdued, with revenue forecasts closer to US$2.0b and potential earnings of about US$346.5 million by 2029 before this latest data wave. Treat today’s news as a fresh reason to compare both narratives.
Explore 4 other Alkermes fair value estimates, including one that suggests there could be as much as 20% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Alkermes research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Alkermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alkermes' overall financial health at a glance.
Looking for more Alkermes sized investment ideas?
If Alkermes has you thinking about where else focused clinical stories and clear financial targets might line up, the Simply Wall St Screener is a useful way to widen your watchlist while still keeping your criteria tight.
- For investors who care most about balance sheet strength and fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) that can help you filter for resilience before anything else.
- If you want potential mispricing to be the focus, scan through a 32 high quality undervalued stocks that highlights businesses where quality and valuation may be out of sync.
- When capital preservation and stability matter more than rapid growth, consider a 30 resilient stocks with low risk scores that concentrates on companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com