


nLIGHT has been on a powerful multi year run, and after a fresh burst of momentum the question now is whether the current share price lines up with the cash the business can generate. With expectations shaped by both recent gains and stronger profitability, the valuation conversation has shifted squarely onto its cash flows and what they can support.
- Over the past 3 years, nLIGHT has delivered a very large share price gain of around 3x. This puts a lot of weight on how durable its future cash generation may be.
- Recent results highlighted higher revenue and improved profitability from defense focused demand. This can influence how investors think about the timing and resilience of nLIGHT's future cash flows.
- If you'd rather focus on sales, this one's for you. See why nLIGHT's 8.2x P/S tells a different valuation story.
The issue now is whether nLIGHT's current US$44.48 share price is sufficiently supported by the cash flows implied by a Discounted Cash Flow (DCF) view.
If you want to pressure test whether nLIGHT's 3 year run and cash flow story holds up beside other opportunities, compare it with 32 high quality undervalued stocks.
Is nLIGHT Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on how much cash nLIGHT can return to shareholders over time. The model uses last twelve month free cash flow of about $22.35 million as a starting point, then assumes that cash generation improves, with projected annual free cash flows stepping up through the early 2030s before easing into a steadier phase. With the current share price at $44.48, the projections suggest that today’s valuation is broadly in line with what these cash flows could support.
Recent Q3 2026 results, including stronger defense driven demand and higher product gross margins, help explain why the market is prepared to pay up for nLIGHT’s future cash generation and keep the price close to the DCF estimate. If you want to see how this intrinsic value picture compares with other stocks that may have more of a gap between price and cash flow estimates, check the full DCF output for nLIGHT beside wider opportunities. Find out what nLIGHT could be worth using our Discounted Cash Flow (DCF) estimate.
The nLIGHT Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF puzzle for nLIGHT leaves off. They spell out the specific path for nLIGHT's revenue, margins and earnings that would need to play out for the share price to end up meaningfully higher or lower than it is today, and they sit on Simply Wall St's Community page so you can see how those assumptions evolve over time. Whereas a single valuation output gives you one figure, Narratives describe the future that figure relies on so you can monitor whether reality tracks it.
One of the top narratives on nLIGHT: 46% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor that must go right is successful execution on large U.S. laser weapon and sensing contracts while managing the exit from legacy cutting and welding revenue and Chinese supply chain risk..."
Discover why this Narrative puts nLIGHT at 46% undervalued.
One more nLIGHT signal that could change how you read the story
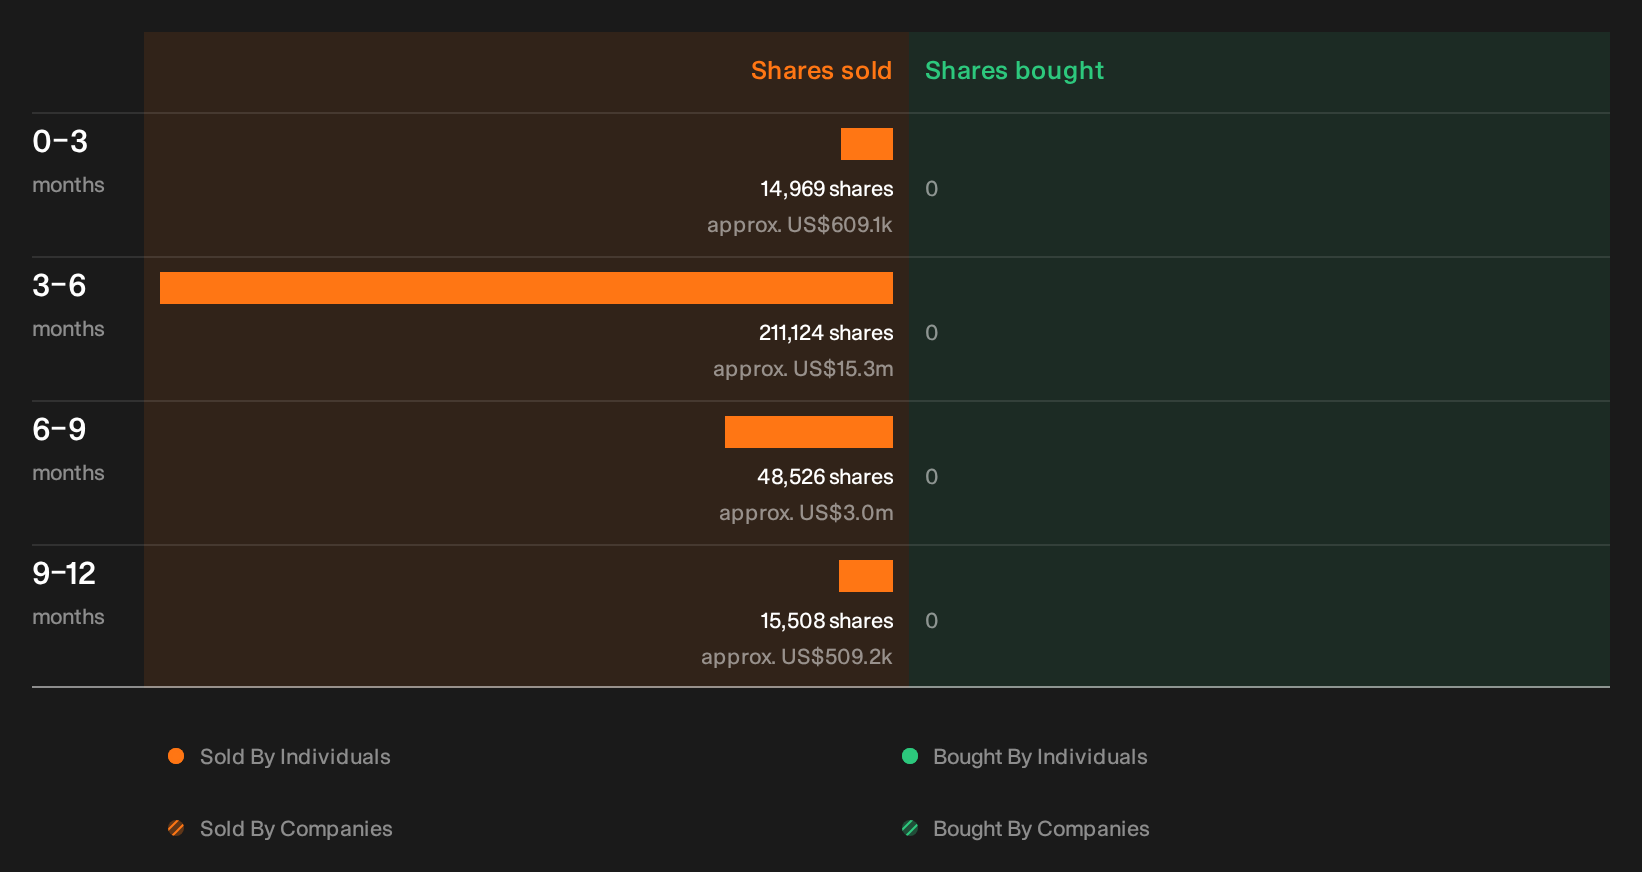
Before you lean too heavily on cash flow estimates and narratives, it is worth checking the recent share activity from people inside nLIGHT, who know the business from the inside out. See the recent insider selling flagged for nLIGHT.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com