


Vulcan Materials (VMC) is back in focus after its third quarter and nine month 2026 earnings release, which showed slightly lower quarterly sales but higher year to date profit and earnings per share.
The share price reaction has been choppy around the results. Vulcan Materials closed at US$284.37 after falling 1.02% on a 1 day share price return and 4.47% on a 7 day share price return, even though the 30 day share price return is up 16.00% and the 3 year total shareholder return is 37.86%. This points to longer term holders still sitting on meaningful gains while shorter term momentum has cooled.
Capitalize on Vulcan Materials being back in the headlines by scanning a curated set of infrastructure and construction-linked plays through 42 power grid technology and infrastructure stocks.Vulcan Materials now trades below the average analyst price target, even as its own valuation signal suggests a mild premium. Is the recent pullback a healthy reset, or a warning sign on what the market sees ahead?
Most Popular Narrative: 9% Undervalued
Compared with Vulcan Materials' last close at $284.37, the analyst consensus Narrative on Simply Wall St points to a fair value near $311. That view is built on detailed assumptions about demand, pricing, costs, and capital allocation.
The company's footprint in growing Sunbelt metros continues to line up with a visible pipeline of large public and private projects, including a large volume of data centers and related power and LNG work, where about 60% of all large projects are within 50 miles of a Vulcan facility, which can support future aggregates shipments and earnings as those projects move from award to steady production.
See why 15 investors see Vulcan Materials as 9% undervalued.
Result: Fair Value of $311 (UNDERVALUED)
Still, higher diesel costs pressuring cash costs and a cautious view on 2027 volumes could easily reverse Vulcan Materials' undervalued story.
Find out about the key risks to this Vulcan Materials narrative.
Another View: Vulcan Materials Looks Expensive On Earnings
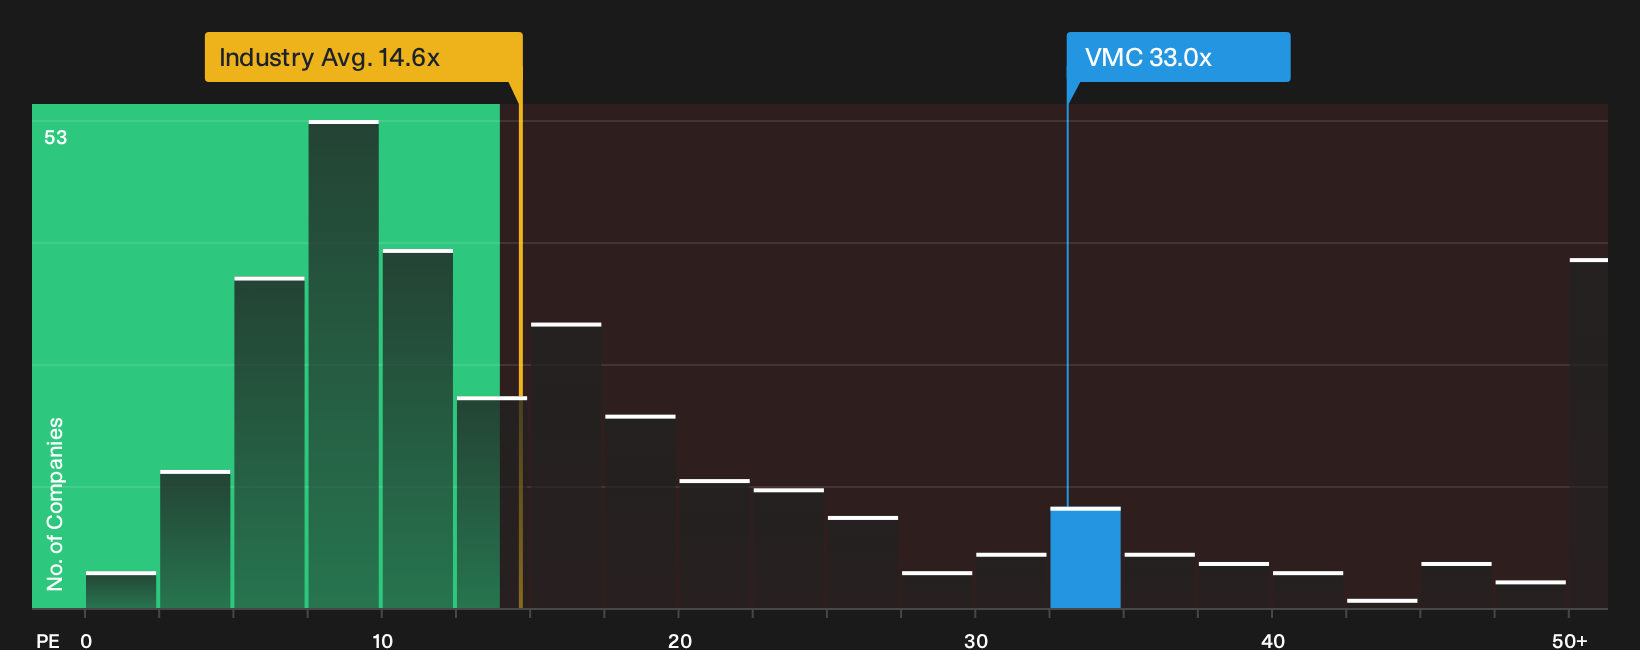
The fair value narrative paints Vulcan Materials as about 9% undervalued around $311 per share. The earnings multiple tells a very different story. VMC trades on a P/E of 33x versus 14.8x for the global Basic Materials group and 25.7x for peers, while the fair ratio is 19.7x. That gap points to meaningful valuation risk if sentiment or forecasts cool.
For investors who want to understand how this richer P/E lines up against a cash flow based approach, it is worth seeing how the SWS DCF model tackles Vulcan Materials, step by step, through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Vulcan Materials can be confusing. Move quickly, review the full risk and reward breakdown, and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Vulcan Materials?
If Vulcan Materials has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against fresh opportunities using the Simply Wall St Screener.
- Target potential mispricing by scanning a curated group of quality stocks trading below their implied value through 32 high quality undervalued stocks.
- Prioritise resilience by focusing on companies with strong financial footing using the list of solid balance sheet and fundamentals (23 results).
- Build your dividend watchlist by zeroing in on income-focused opportunities screened as 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com