


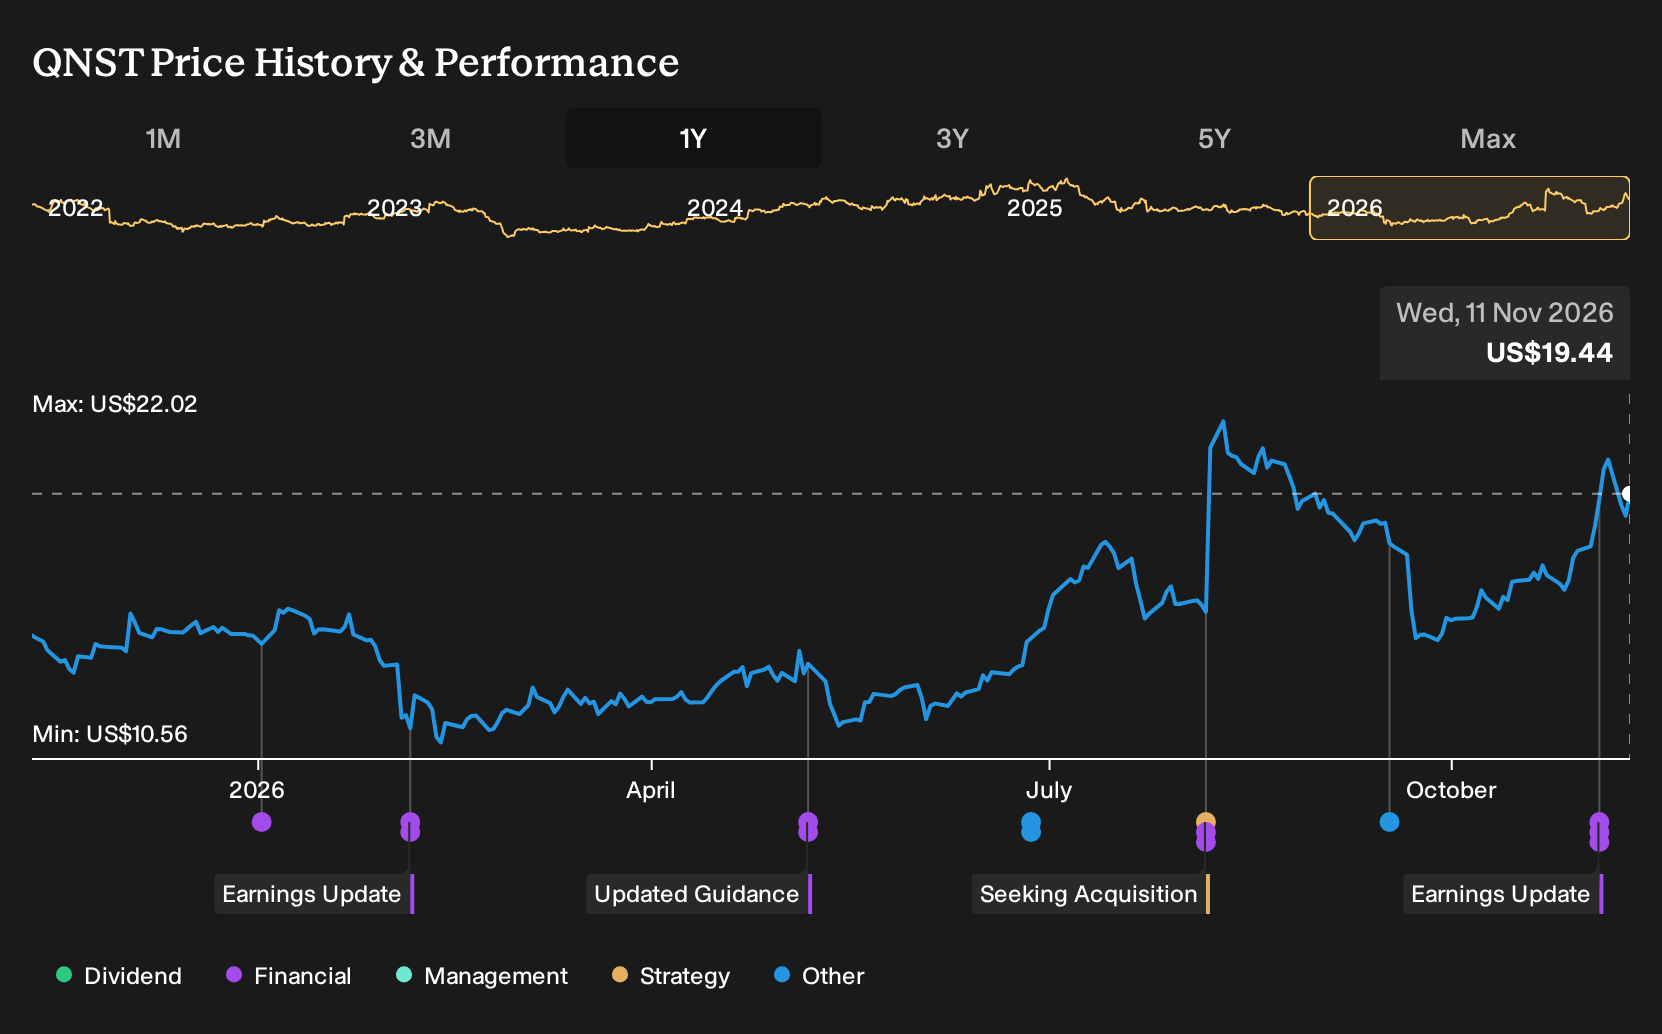
- QuinStreet reported first quarter fiscal 2027 results for the period ended September 30, 2026, with sales of US$416.65 million and net income of US$17.02 million, alongside basic earnings per share from continuing operations of US$0.30 and diluted earnings per share of US$0.29.
- The business paired this earnings release with higher full year 2027 revenue guidance of US$1.5 billion to US$1.6 billion and a second quarter revenue outlook of US$360 million to US$380 million, which reflects management’s view of demand for its performance marketing services.
- We will now look at how QuinStreet's raised full year 2027 revenue guidance could influence the investment narrative around its growth profile.
Scan how QuinStreet’s raised outlook fits alongside peers by lining it up against 32 high quality undervalued stocks that may also be pricing in stronger revenue stories.
QuinStreet Investment Narrative Recap
To own QuinStreet, you need to be comfortable with a business tied tightly to digital customer acquisition, especially in insurance and financial services, where advertiser budgets can swing quickly. The raised 2027 revenue outlook puts more weight on execution of its media mix, data capabilities, and platforms like QMP and QRP to keep lead quality attractive.
The short term swing factor now is whether that higher revenue guidance translates into sustained net margin quality after a very strong year of profit growth cited in the analyst consensus Narrative on Simply Wall St. The main near term risk remains exposure to large clients and paid search platforms, where any pullback in spend or algorithm change could quickly dent performance.
The most relevant development is the new and raised guidance around fiscal 2027, paired with the first quarter update that showed US$416.65 million in sales and US$17.02 million in net income. Management is effectively putting numbers around the same themes analysts have been watching, such as margin work and broader client participation.
Guidance for second quarter 2027 revenue of US$360 million to US$380 million now sits alongside analyst expectations for slower revenue growth than the wider US market, which keeps execution risk front and center. For you as a shareholder, the key question is whether QuinStreet can keep scaling its higher margin products fast enough to offset competition and rising compliance and traffic acquisition costs.
QuinStreet's narrative projects US$1.8b revenue and US$107.5 million earnings by 2029. Analysts factor in 8.4% yearly revenue growth and an earnings increase of about US$13.8 million, from US$93.7 million today to reach that 2029 consensus level.
Uncover why QuinStreet's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The lowest QuinStreet analysts focus on margin pressure, not growth. Before this guidance, they were only pencilling in about US$1.8b of revenue and roughly US$93.5 million of earnings by 2029, which is far more cautious than the consensus. You can treat this as a reminder that views vary widely and are likely to shift after the latest update.
Explore 2 other QuinStreet fair value estimates, including one that suggests it could be worth just $21.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QuinStreet research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QuinStreet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QuinStreet's overall financial health at a glance.
Looking for more investment ideas beyond QuinStreet?
If the updated QuinStreet story has sharpened your view on risk and reward, you can use that same lens to scan a wider set of opportunities with the Simply Wall St Screener. You can filter by balance sheet strength, income focus or potential mispricing and quickly see which businesses deserve a closer look.
- If capital preservation sits high on your list, start with a 30 resilient stocks with low risk scores that may appeal if you want steadier profiles.
- If you are hunting for mispriced quality, a 32 high quality undervalued stocks can help you focus on companies where fundamentals and expectations look out of sync.
- If balance sheet resilience matters most to you, consider the list of solid balance sheet and fundamentals (23 results) as a way to filter for businesses with stronger financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com