


Personal care company Edgewell Personal Care (NYSE:EPC) reported calendar Q3 2026 [fiscal Q4 2026] results topping the market’s revenue expectations, with revenue up 3% year on year to $484.1 million. Its non-GAAP profit of $0.78 per share was in line with analysts’ consensus estimates.
For more on Edgewell Personal Care, read the full research report for free.
Edgewell Personal Care Q3 CY2026 highlights:
- Revenue $484.1 million vs S&P analyst consensus of $480.2 million (3% year-on-year growth, 0.8% beat)
- Adjusted EPS $0.78 vs S&P analyst consensus of $0.77 (in line)
- Adjusted EBITDA $76.8 million vs analysts’ consensus estimates of $77.32 million (15.9% margin, 0.7% miss)
- Adjusted EPS guidance $2 at the midpoint for fiscal 2027, beating analysts’ consensus estimates by 1%
- EBITDA guidance $260 million at the midpoint for fiscal 2027, above analysts’ consensus estimates of $257.6 million
- Operating margin 3.5%, up from -7.7% in the same quarter last year
- Free cash flow -$15.9 million, down from $46.5 million in the same quarter last year
- Organic revenue rose 3.1% year on year (miss)
- Market capitalization $1.34 billion
"Fiscal 2026 was a year of meaningful progress and change for Edgewell, culminating in a strong fourth quarter that reflected continued growth in North America, a return to growth in International and stronger performance across our focus brands," said Rod Little, President and Chief Executive Officer. "Our second-half performance enabled us to deliver the top- and bottom-line outlook we established at the beginning of the year on an adjusted basis, providing further evidence that our investments in innovation, brand building and commercial execution are gaining traction. We enter fiscal 2027 as a more focused business, with confidence in our plans to build on this progress, increase support behind our brands and improve profitability. While significant cost and competitive headwinds persist, we believe the broader transformation of our operating model is creating greater capacity to invest and supporting more consistent growth and margin expansion."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years.
With $2.00 billion in revenue over the past 12 months, Edgewell Personal Care is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
Edgewell Personal Care struggled to generate demand over the last three years. Its revenue dropped by 3.9% annually.
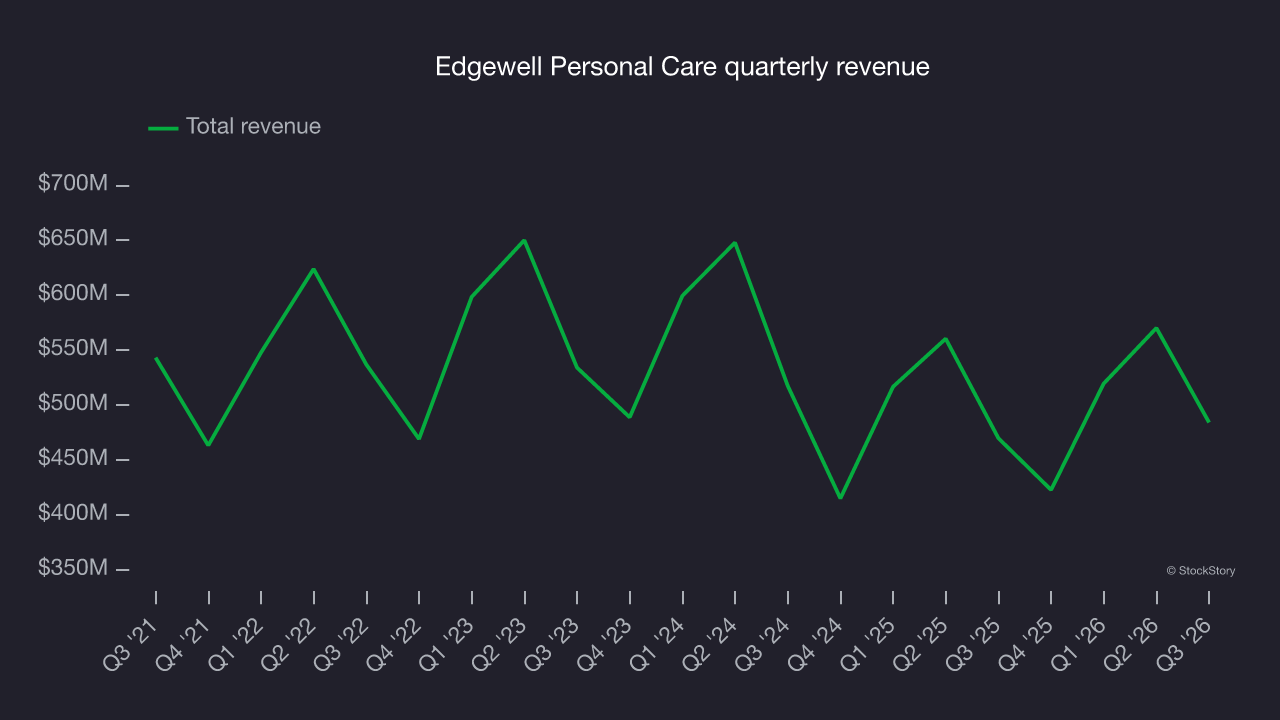
This quarter, Edgewell Personal Care reported modest year-on-year revenue growth of 3% but beat Wall Street’s consensus estimates by 0.8%.
Looking ahead, sell-side analysts expect revenue to grow 1.2% over the next 12 months, according to S&P. Although this projection indicates its newer products will drive better revenue growth, it is still below the sector average.
Organic revenue growth
When analyzing revenue growth, the most important measure is organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions and divestitures as well as foreign currency fluctuations.
The demand for Edgewell Personal Care’s products has barely risen over the last eight quarters. On average, the company’s organic revenue has been flat. 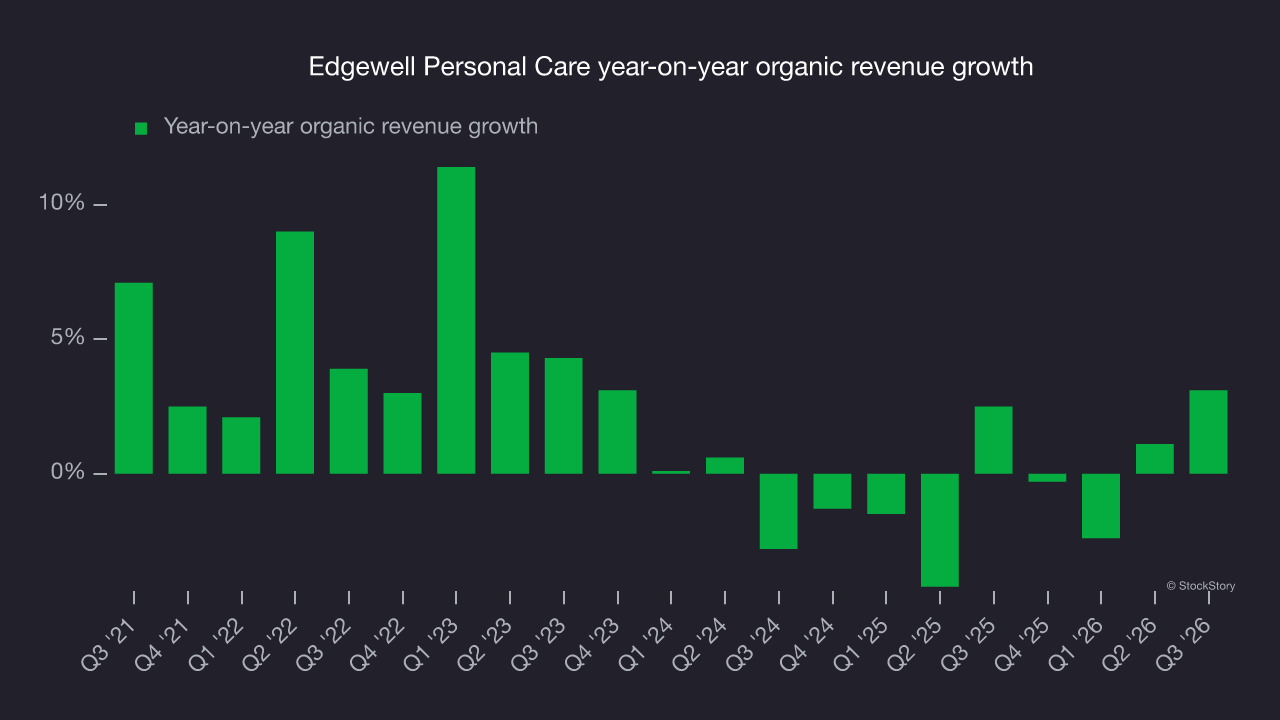
In the latest quarter, Edgewell Personal Care’s organic revenue rose by 3.1% year on year. This growth marked a turnaround from its historical levels, showing the business is regaining momentum.
Key takeaways from Edgewell Personal Care’s Q3 results
Edgewell Personal Care’s quarter could have been better despite revenue narrowly topping analysts’ consensus estimates. Organic revenue and gross margin both fell short of Wall Street’s expectations. Shares remained flat at $29.18 immediately after the release.
When deciding whether to buy the stock, the latest quarter matters, but longer-term fundamentals and valuation matter more. For more on that assessment, read the full research report here (it’s free).