


Crown Castle Inc. (CCI), headquartered in Houston, Texas, owns, operates and leases more than 40,000 cell towers and approximately 90,000 route miles of fiber supporting small cells and fiber solutions across every major U.S. market. Valued at $37.9 billion by market cap, the company manages and offers wireless communication coverage and infrastructure sites in the U.S. and Australia.
Shares of this leading provider of wireless infrastructure have underperformed the broader market over the past year. CCI has declined 5.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 11.3%. In 2026, CCI stock is up marginally, compared to the SPX’s 11.3% rise on a YTD basis.
Narrowing the focus, CCI’s outperformance is apparent compared to the Pacer Benchmark Data & Infrastructure Real Estate SCTR ETF (SRVR). The exchange-traded fund has fallen about 6.2% over the past year. Meanwhile, CCI’s marginal returns on a YTD basis mirror the ETF’s slight gains over the same time frame.
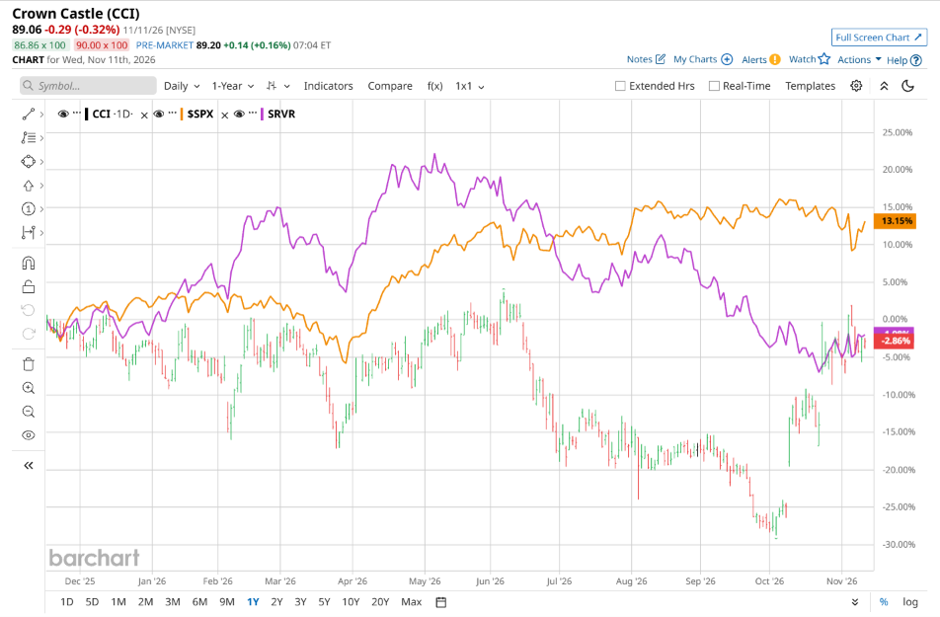
CCI has experienced a volatile performance trajectory over the past year, recently trading around the 89.06 level while navigating a broader transition into a pure-play cell tower REIT. The stock's mixed momentum has been influenced by shifting macroeconomic conditions, ongoing interest rate pressures, and sector-wide telecom dynamics, such as competition and spectrum developments, offset by steady cash flow generation, defensive infrastructure demand, and a reliable quarterly dividend of $1.06 per share.
On Oct. 21, CCI shares closed down more than 3% after reporting its Q3 results. Its FFO of $1.24 per share surpassed Wall Street expectations of $1.20 per share. The company’s revenue was $995 million, missing Wall Street forecasts of $1 billion. CCI expects full-year FFO in the range of $4.54 to $4.66 per share.
For the current fiscal year, ending in December, analysts expect CCI’s FFO per share to grow 1.4% to $4.42 on a diluted basis. The company’s FFO surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 23 analysts covering CCI stock, the consensus is a “Moderate Buy.” That’s based on 12 “Strong Buy” ratings, one “Moderate Buy,” and 10 “Holds.”
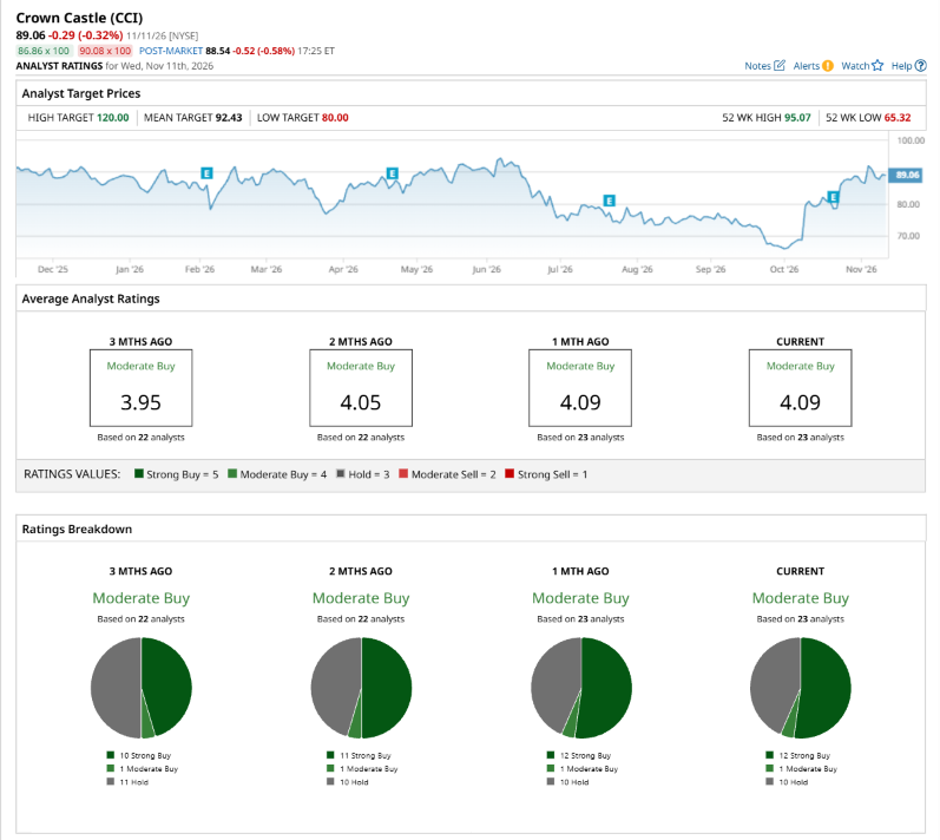
This configuration is more bullish than two months ago, with 11 analysts suggesting a “Strong Buy.”
On Oct. 23, David Paige from RBC Capital maintained a “Buy” rating on CCI, with a price target of $90, implying a potential upside of 1.1% from current levels.
The mean price target of $92.43 represents a 3.8% premium to CCI’s current price levels. The Street-high price target of $120 suggests a notable upside potential of 34.7%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.