


KLA Corporation has delivered a powerful share price run over several years, and that kind of track record naturally raises a question about whether the current valuation is still grounded in its earnings power. With fresh credit rating news in the mix, the issue for you is how much of KLA's profit potential today is already reflected in a US$161.01 share price at the last close.
- Over the past 5 years the stock has gained 298.4%, which puts a lot of weight on whether the underlying earnings story can support such compounding.
- S&P's upgrade of KLA's credit rating to A, tied to AI related chip demand and disciplined leverage, can support a lower cost of capital and more flexibility around funding future profit growth.
- There is a second opinion on KLA worth weighing. See what analysts think KLA's shares could be worth.
The stock's next move may depend on whether KLA's current earnings and their trajectory are strong enough to justify the valuation investors are paying today.
If you are weighing KLA against other ways to play this earnings driven AI infrastructure story, it can help to line it up beside 53 AI infrastructure stocks.
Has KLA Run Too Far on Earnings?
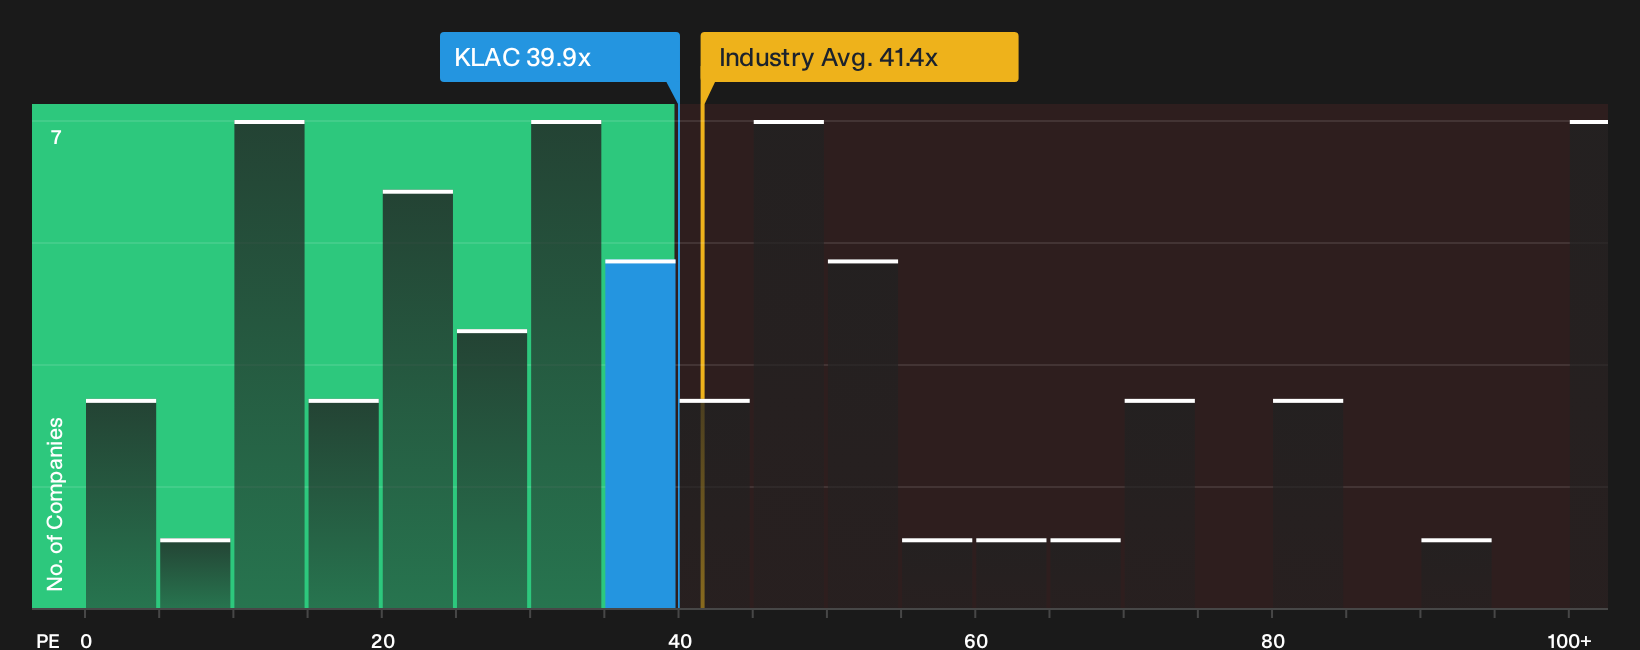
The P/E ratio suits KLA because investors mainly focus on its earnings power and cash generation. From this perspective, the stock trades on about 39.9x earnings, which is slightly below the Semiconductor group on roughly 41.4x but still in the same general ballpark. Compared with direct peers on around 36.6x, the market is asking you to pay a premium for each dollar of KLA’s profit.
The fair multiple implied by KLA’s own growth, margins and risk profile sits below the current P/E, so the shares screen as overvalued on this framework. S&P’s recent upgrade to an A credit rating, tied to AI related chip demand and disciplined leverage, helps explain why investors are willing to stretch the earnings multiple. However, the current price already bakes in that stronger balance sheet story. Explore the numbers behind KLA's P/E valuation.
The KLA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where KLA's valuation puzzle leaves off. They spell out the specific growth, margin and earnings paths that would need to play out for the stock to be worth much more or much less than today’s share price. Instead of a single multiple or model result, each one lays out the assumptions behind its fair value so you can compare those expectations with KLA's actual numbers as results arrive.
One of the top narratives on KLA: 28% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that KLA continues to convert its large, long dated backlog and process control share gains into high margin systems…"
Discover why this Narrative puts KLA at 28% undervalued.
One more piece of the KLA puzzle before you make a move
You have seen what KLA Corporation looks like on today’s numbers and market expectations for its earnings power, but analyst views on where this business could be a few years out add a different comparison point. Explore where analysts expect KLA to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com