


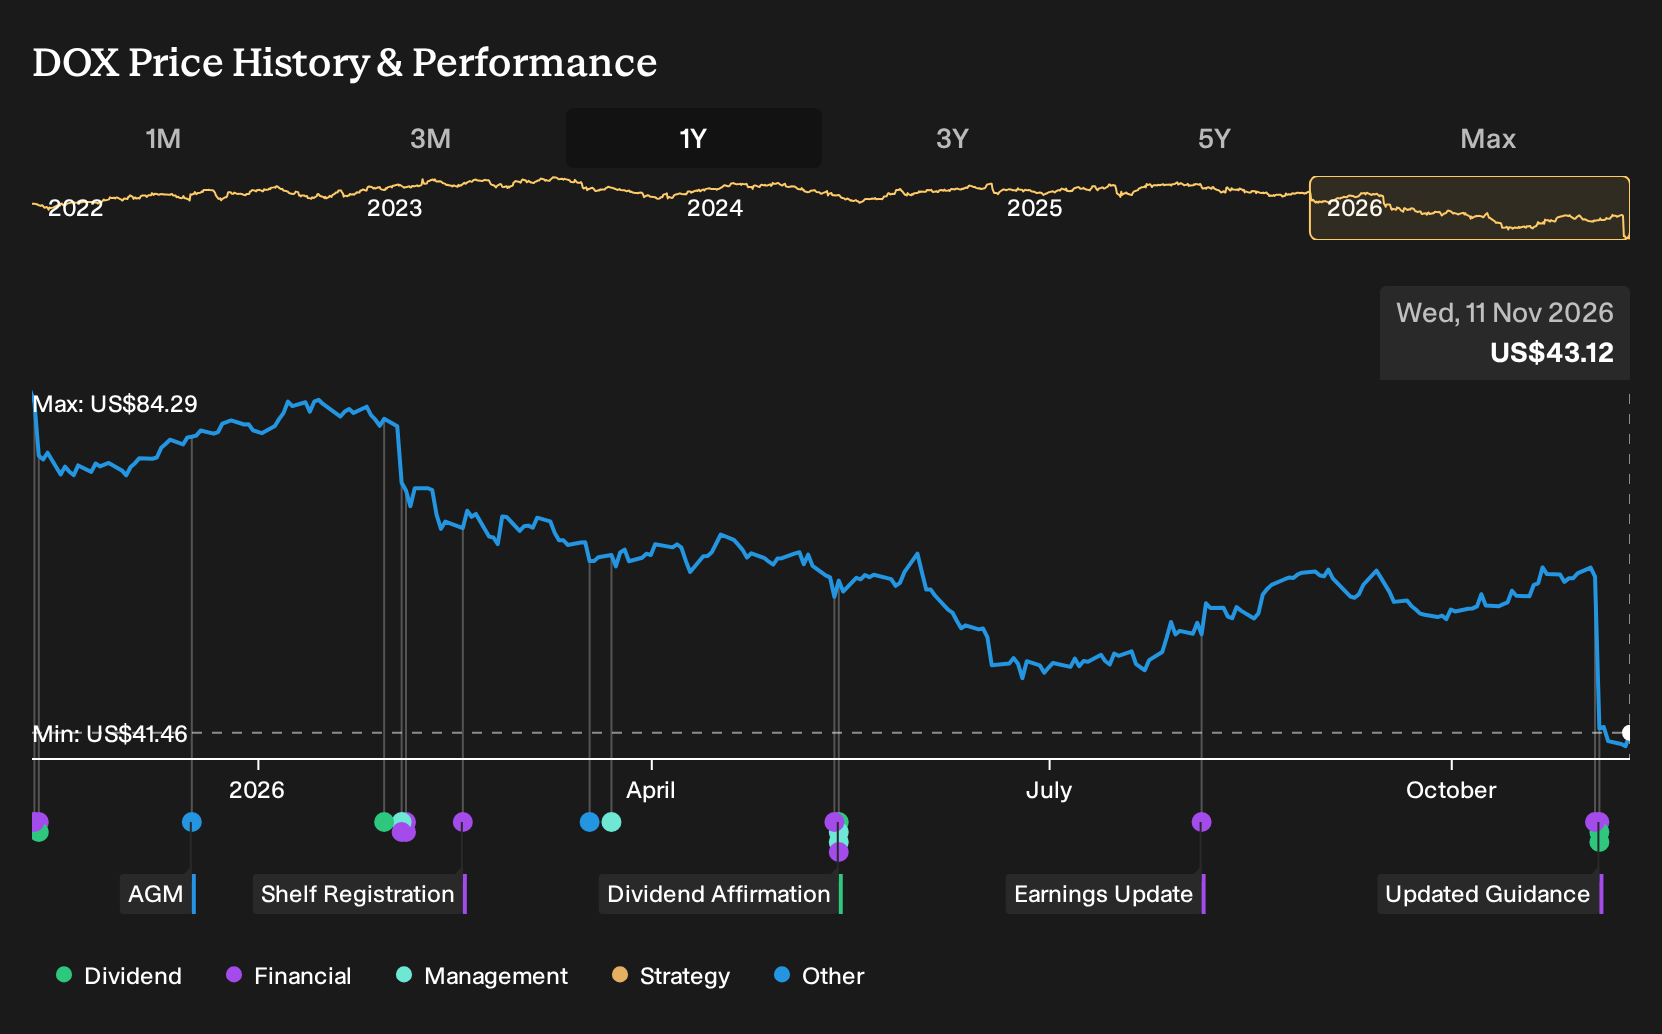
- Amdocs reported full-year 2026 sales of US$4,696.58 million, with lower net income, and issued fiscal 2027 guidance that points to revenue and GAAP EPS declining compared with the prior year.
- The business also disclosed a legal dispute with T-Mobile that has progressed into litigation, prompting a securities fraud investigation focused on past disclosures related to that key customer contract.
- We will now see how Amdocs' prior high-conviction investment narrative holds up in light of the new legal dispute with T-Mobile.
Scan beyond Amdocs and see how other communications and software players are positioned after earnings resets by zeroing in on 30 resilient stocks with low risk scores.
Amdocs Investment Narrative Recap
For Amdocs, the big picture hinges on whether you believe its telecom and software clients keep relying on its BSS and OSS platforms while it rolls out GenAI led offerings like CES25, aOS and amAIz. The dispute with T Mobile and the 2027 guidance reset put that operational dependability under scrutiny and keep customer concentration risk front and center.
The key near term catalyst is management’s ability to stabilize revenue after guiding to a 17.9% to 14.3% decline in fiscal 2027 and a 17% to 25% drop in GAAP EPS. Execution on the existing US$4.7b revenue base, backlog conversion and legal clarity around T Mobile are likely to drive whether sentiment improves or worsens.
The dividend decisions are particularly relevant now. Amdocs’ board kept the quarterly cash dividend at US$0.569 per share for the January 29, 2027 payment, even as guidance points to weaker revenue and earnings next year. That indicates the payout is being maintained into a period where the operating outlook is softer and legal costs could be higher.
The planned 3% lift in the quarterly dividend to US$0.586 per share, expected from April 2027 subject to shareholder approval, adds another lever to watch. For investors who see the stock as a value and income idea, as HarishPK, a Simply Wall St Community investor who wrote the Narrative, argues, the combination of lower near term growth and a higher dividend places more focus on cash generation and balance sheet resilience as potential catalysts for any future re rating.
On HarishPK’s numbers, that US$61.79 fair value comes from a discounted cash flow framework. This framework assumes Amdocs can compound revenue at 3.6% a year while settling into an 11.8% profit margin over time, and then discounts those projected cash flows back to today.
Uncover why Amdocs' fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some analysts saw a very different risk around Amdocs even before this T-Mobile dispute and 2027 guidance reset. The lowest forecasts were already calling for revenue of about US$5.2b and earnings of roughly US$460.3m by 2029, which paints a more cautious story. That group looks more pessimistic, so treat this news as a prompt to compare several viewpoints before deciding where you sit.
Explore 6 other Amdocs fair value estimates, including one that suggests it could be worth just $46.00.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Amdocs research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amdocs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amdocs' overall financial health at a glance.
Looking for more investment ideas beyond Amdocs?
Once you have a view on Amdocs and the T-Mobile dispute, it can help to broaden your watchlist and see how other businesses stack up on quality, valuation and resilience. The Simply Wall St Screener lets you quickly filter for stocks that match the kind of risk and return profile you are actually comfortable holding.
- If capital preservation and shock resistance matter most to you, focus on companies that score well on stability and see what turns up in the 30 resilient stocks with low risk scores.
- If you are hunting for potential mispricings backed by solid fundamentals, sort the market by quality and value signals with the 19 high quality undiscovered gems.
- If reliable income streams are a priority, concentrate on payout strength and consistency and scan through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com