


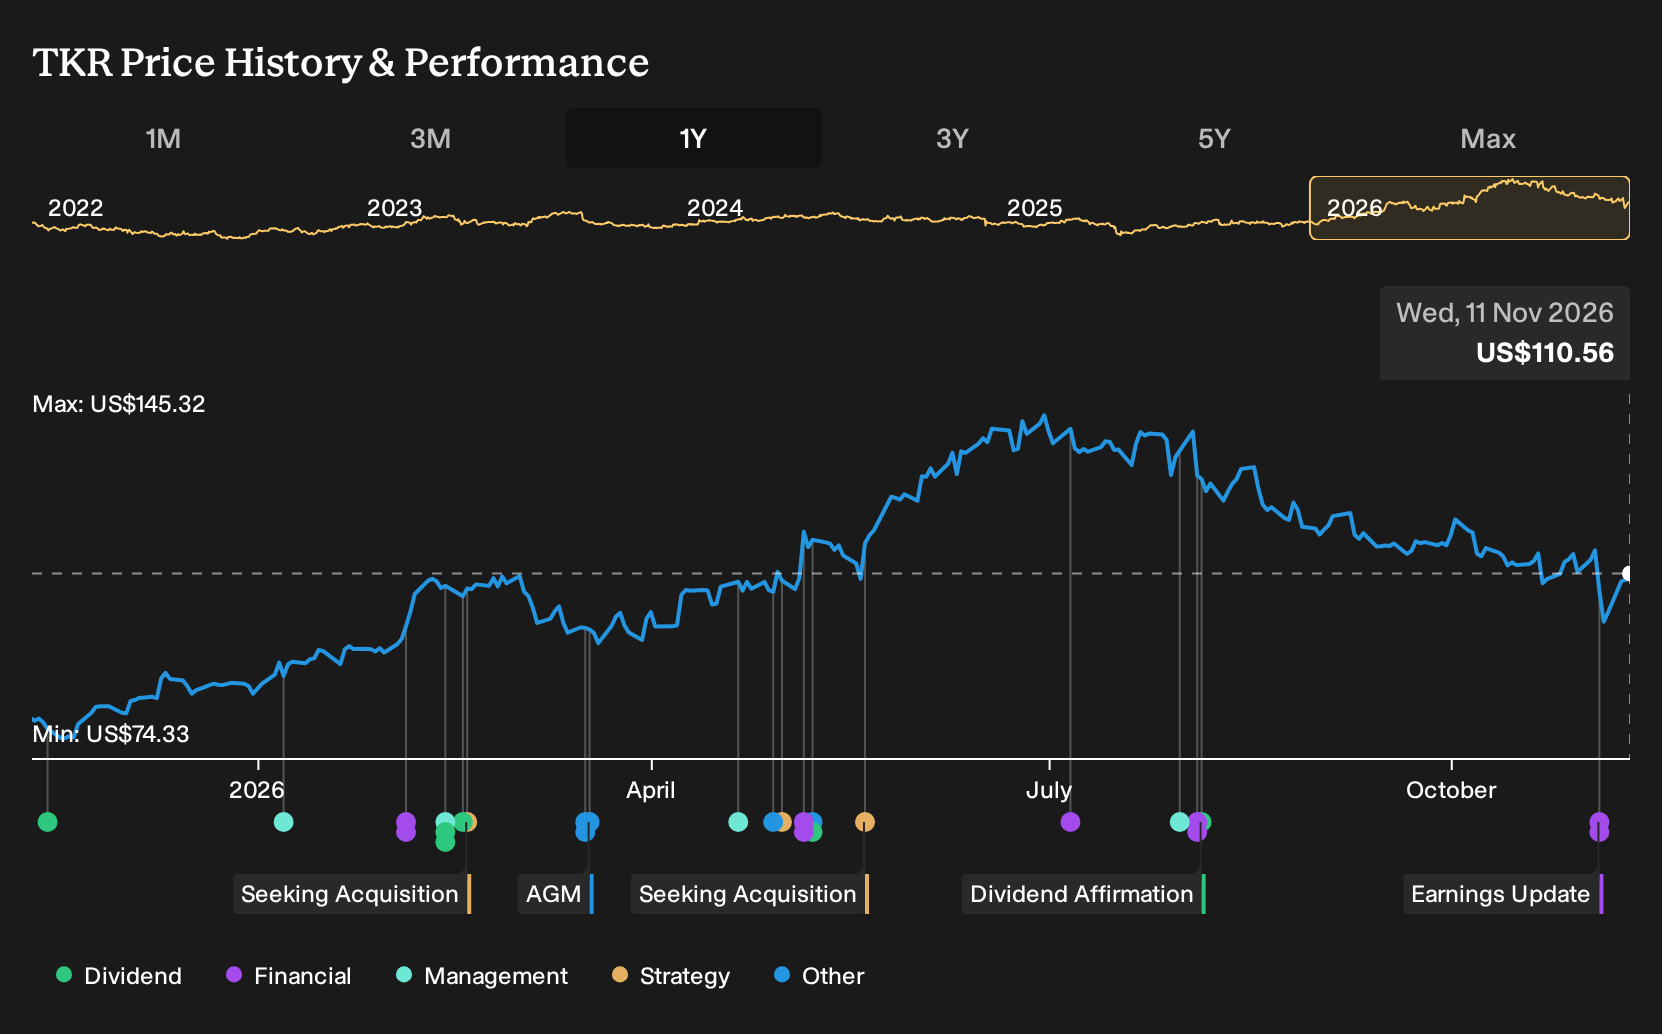
- Timken reported third quarter 2026 sales of US$1,211.4 million and net income of US$93.8 million, raised full year earnings guidance, and completed a US$111.12 million share repurchase program covering 1.35% of its equity.
- The combination of higher quarterly earnings per share, increased 2026 earnings and revenue guidance, and ongoing share buybacks indicates management confidence in Timken’s operating trajectory and capital allocation priorities.
- Now the focus shifts to how Timken's raised 2026 earnings guidance may reshape the existing investment narrative built around margin expansion.
Compare Timken's upgraded 2026 outlook and recent buybacks with other industrial names preparing for potential breakouts by scanning the hand picked 42 power grid technology and infrastructure stocks.
Timken Investment Narrative Recap
To own Timken, you need to believe the Elevate to Outperform and 80/20 programs can keep lifting efficiency, while the shift toward higher value Industrial Motion products offsets softer areas like solar and wind. The raised 2026 earnings guidance and solid third quarter result support that execution story, although the analyst consensus Narrative on Simply Wall St still highlights slower implied organic growth in the second half.
The main near term swing factor remains margins. Higher labor, equipment and incentive costs in aerospace and defense facilities, along with mix pressure in renewables, keep risk on profitability, even with better pricing and cost work. The recent updates do not remove that risk; they just show progress against it.
The most relevant announcement here is the higher 2026 earnings per diluted share guidance of US$4.05 to US$4.20, alongside a plan for 2026 revenue to be about 5.5% above 2025. That outlook builds on the Elevate to Outperform margin ambitions and the portfolio shift away from lower return automotive OEM and belts activities already underway.
For you as a shareholder or potential shareholder, that guidance update ties directly into the margin expansion and capital deployment catalysts analysts are watching. It also comes as Timken has completed a US$111.12 million buyback and is preparing to speak at the Baird 2026 Global Industrial Conference, which gives management a public forum to explain how they see execution, risks and capital allocation lining up from here.
Timken's narrative assumes revenues reach US$5.3b and earnings rise to US$653.4 million by 2029. This implies about 3.5% yearly revenue growth and an earnings increase of roughly US$370 million from the US$283.2 million reported today.
Uncover why Timken's fair value indicates a 28% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Timken focuses on the buyback and capital deployment story. Before this earnings beat and the completed US$111.12 million repurchase, the most optimistic analysts were already modelling revenue of about US$5.5b and earnings of roughly US$721.9 million by 2029. That is a much richer earnings path than consensus. You can treat this conference update and higher 2026 EPS guidance as a live test of whether that upbeat script gains more followers or is revised closer to the baseline view.
Explore 3 other Timken fair value estimates, including one that suggests potential upside of as much as 45% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Timken research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Timken. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Timken's overall financial health at a glance.
Looking for more investment ideas beyond Timken?
If Timken has sharpened your interest in industrials and income opportunities, it can help to line it up against a wider watchlist built around clear financial qualities.
- If you care most about quality at a reasonable entry point, start with companies that screen for value and fundamentals by reviewing the 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you, narrow the field to businesses that pass strict risk filters with the 30 resilient stocks with low risk scores.
- If balance sheet strength is your first checkpoint, build a shortlist around financial resilience using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com